
What is AML Screening?
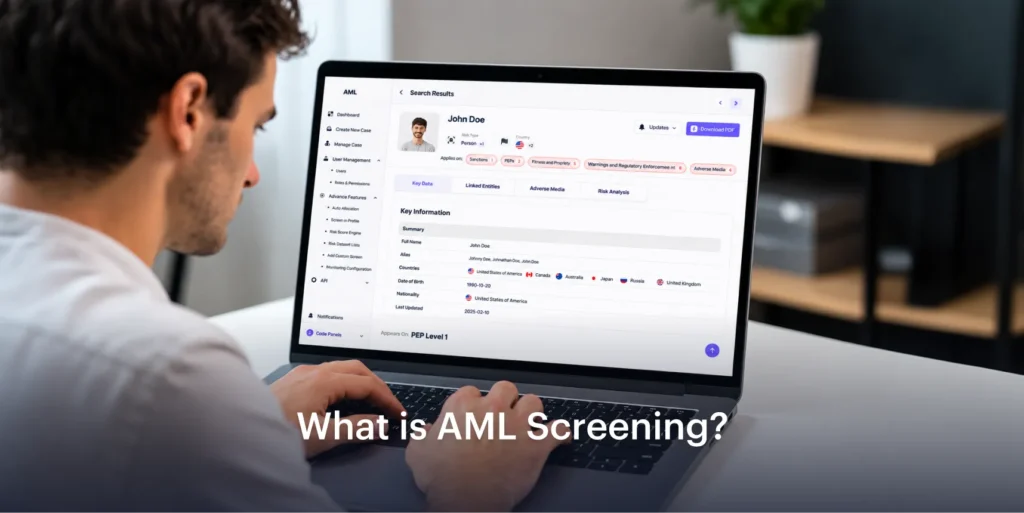
Anti Money Laundering (AML) screening is a preventive and investigative measure against the crimes of money laundering and involves financial risk assessment of the entities through global watchlist screening, sanctions lists and risk databases. To clearly understand AML screening, we need to understand what money laundering actually is. Money laundering is a criminal offence that involves blurring the trail between funds and a criminal act e.g., extortion, drug trafficking or human trafficking that generated those funds. So, AML screening is potentially looking for a link between an individual/entity being screened and financial crimes that can produce criminal proceeds. However, AML screening is usually used in a broader sense that also includes sanctions and PEP screening.
Who is screened during AML screening?
Depending on the business relationship and applicable requirements, the screening may cover:
- Individuals: Customers, directors, beneficial owners, authorised representatives, and other relevant parties.
- Business entities: Companies, organisations, and other corporate customers.
- Connected parties: Ultimate Beneficial Owners (UBOs), shareholders, family members, close associates, and counterparties where relevant.
- Payment parties: Senders, beneficiaries, and other parties involved in a transaction, where payment screening is required.
The screening results are assessed by the compliance teams to determine whether to perform further investigation, enhanced due diligence, escalation, or action under applicable laws and internal policies.
AML Screening vs. Transaction Monitoring
Transaction monitoring appears as a similar term to AML screening as both address the financial crime risks, however the two terms differentiate with each other in terms of the scope, timing and checks performed.
| Dimension | AML screening | Transaction monitoring |
| Primary purpose | Identify potential connections to listed or otherwise high-risk parties | Identify unusual transaction activity and behavioural patterns |
| Main inputs | Names, aliases, identifiers, ownership details, sanctions records, PEP data, adverse media | Transaction amounts, frequency, counterparties, geography, expected activity, historical behaviour |
| Typical timing | Onboarding, relevant list updates, changes in customer information, periodic reviews, and payment execution where required | During or after transactions, continuously or at defined intervals, depending on the system and control |
| Typical output | Potential matches, screening alerts, and risk findings | Unusual-activity alerts, rule breaches, and investigation cases |
| Possible response | Clear the alert, investigate, escalate, apply restrictions, or conduct EDD | Investigate activity, update risk assessments, request information, restrict activity, or report where required |
What Does AML Screening Include?
AML screening solution commonly combines several categories of risk information. The precise screening scope depends on the business model, customer type, jurisdiction, risk assessment, and applicable legal requirements.
1. Sanctions Screening
Sanctions screening checks customers, beneficial owners, counterparties, and payment parties against relevant government and multilateral sanctions lists, such as OFAC, UN, EU, and UK lists.
2. Watchlist Screening
Watchlist screening checks individuals and businesses against a broader set of such risk related databases that may or may not necessarily be a list issued by legal authorities. Information about individuals and organisations in these lists may require additional checks These databases may include politically exposed persons (PEPs), individuals mentioned in negative news, and people flagged by regulatory or law enforcement authorities.
3. Politically Exposed Person (PEP) Screening
PEP screening identifies individuals that hold prominent public functions either in the past or at present, such as senior politicians, government officials or executives of state-owned enterprises. PEP screening is also used to identify immediate family members and close associates of PEPs as FATF recommends application of corresponding measures to relatives and close associates of a direct PEP.
4. Adverse Media Screening
Adverse media screening covers the risk information of the entity that may not appear on formal sanctions or PEP lists, but appears with a negative reputation on media sources. Reviewers assess the source’s reliability, the relevance of the information and whether it describes an allegation, investigation or established finding.
5. Offshore Disclosure Databases
These databases carry the information of exposed entities, alleged mostly for illicit offshore financial activities. These lists are exposed either in the form of anonymised leaked records or the records published through international investigative journalism. Famous examples include panama papers and pandora papers, which were the investigative records and exposed offshore financial arrangements linked to individuals and organisations worldwide.
6. Insolvency Screening
Insolvency screening checks individuals and businesses against records of bankruptcy, insolvency, and financial distress. The purpose of this screening is to assess the financial reliability of individuals and businesses and identify potential risks before establishing or continuing a business relationship.
How Does the AML Screening Process Work?
1. Collect and Verify Customer Information
Screening begins with the information needed to identify the subject reliably.
For individuals, this may include the full legal name, date of birth, nationality, identification details, and other available identifiers.
For businesses, it may include the registered legal name, registration number, incorporation jurisdiction, incorporation date, and ownership information.
Identity verification and KYB checks can help establish whether the submitted information is reliable. The exact data requirements depend on the screening use case and available records.
Where key identifiers are missing, the screening result may be less conclusive. A name-only match, for example, may be difficult to distinguish from records belonging to other people with similar names.
2. Define the Screening Scope
The business must determine which sources and parties need to be screened.
It may involve all three sources, i.e, sanctions screening, PEP screening or adverse media screening, or other watchlists, or any of these screenings, depending upon the regulatory requirements, risk categories defined by the businesses themselves, or information received from either sources upon first screening.
Screening coverage should reflect the relevant parties and available data, rather than relying exclusively on the primary customer’s name. For example, a corporate onboarding workflow may need to screen the company and its UBOs separately.
3. Standardise the Screening Data
Before matching begins, customer information should be complete and consistently formatted.
Data preparation may include standardising name order, removing formatting inconsistencies, and resolving duplicate or conflicting records. Businesses should also keep check of transliterations or non latin scripts constraints.
4. Apply Name Matching and Generate Alerts
Screening systems use matching logic to identify records that resemble the submitted information.
- Exact matching identifies records that correspond closely to the supplied data.
- Fuzzy matching identifies approximate similarities, including spelling variations, differences in name order, aliases, and other discrepancies.
- Phonetic and transliteration matching can help identify names that sound similar or are represented differently across languages and writing systems.
5. Review Alerts and Document Decision:
After an alert is generated or name is matched with a list, a compliance officer reviews the alert and decides whether it can be closed as a false match or can be categorised as a true match or requires contacting customer for further details if a decision can’t be reached in either direction.
A customer’s name matches a sanctions-list entry, but the dates of birth differ. The analyst compares the full entry with verified customer information, records the evidence and rationale, and escalates under the applicable procedure if the match remains plausible.
The system may assign a match score to indicate the degree of similarity between the submitted information and a source record. Businesses should not automatically consider a match score as a finding of definitive criminality. Similarly, a result with no matches should not automatically establish that a customer is low risk. The overall assessment must consider other risk indicators and the effectiveness of the organisation’s controls.
6. Re-Screen and Monitor the Relationship
Re-screen customers to identify new potential matches and changes in their risk exposure. This helps keep customer risk assessments current throughout the business relationship.
Screening does not end once onboarding is complete. Relevant records can change when sanctions lists are amended, a person takes on a public function, new adverse information emerges, or customer ownership changes.
When Should AML Screening Be Performed?
Customer information and screening sources can change after onboarding. For example, a customer who was not a PEP at the time of onboarding may hold a public office subsequently that requires classification of that customer as a PEP. Similarly, a person onboarded as low risk may be alleged to be involved in fraud at a later stage, requiring monitoring of customer relationship and re-rating as required by new developments on that allegation/case proceedings.
Commonly AML screening is performed at following stages:
- When establishing a customer relationship or opening an account
- When new counterparties like payers or beneficiaries of a transaction are detected
- When material change in customer information occurs like change in beneficial owners
- When new sanctions/designations are added
- After general elections when PEP statuses change in large numbers
- When new appointments updates to government owned enterprises are made
- When regulations require periodic screening (for example annually)
Rescreening frequency should be determined by the applicable rules, risk exposure, source-update arrangements, and internal policy. There is no single interval that is appropriate for every business and screening category.
Common AML Screening Challenges
Incomplete or Inconsistent Customer Data
Missing dates of birth, incorrect names, incomplete corporate records, and outdated ownership information can make accurate matching difficult.
High Volumes of False-Positive Alerts
Common names, incomplete identifiers, and broad matching thresholds can generate alerts for unrelated individuals or entities. Excessive false positives consume analyst capacity and may delay the resolution of relevant cases.
Missed Matches and Inadequate Source Coverage
A screening system may fail to identify relevant exposure if the selected data sources are incomplete, required parties are omitted, or matching logic does not handle name variations effectively.
Changing Sanctions and Risk Information
New designations, amendments, removals, regulatory actions, and adverse media can change a customer’s risk profile after the initial screening.
Complex Ownership Structures and International Names
Cross-border businesses may involve multiple legal entities, layered ownership, aliases, transliterated names, and records in different languages. Screening only the registered business name may therefore leave relevant exposure unidentified.
Inconsistent Alert Resolution and Weak Audit Trails
Different reviewers may reach different conclusions when procedures are unclear or decisions are not supported by sufficient evidence. Missing notes can make later audits and reviews difficult.
Frequently Asked Questions
How Does AML Screening Differ From KYC?
KYC (Know Your Customer) establishes and verifies a customer's identity, while AML screening helps assess risks associated with that customer. Both form part of broader customer due diligence requirements for regulated businesses.
What Happens After an AML Screening Match?
An AML screening match generates an alert for review; it does not automatically confirm wrongdoing. The alert may be closed as a false positive, confirmed as a true match, or escalated for further investigation. The decision and supporting evidence should be documented. Confirmed sanctions matches require action according to applicable legal restrictions, while PEP and adverse media matches generally require a risk-based assessment.
How Can Businesses Reduce False-Positive Screening Alerts?
Businesses can reduce false positives by using accurate customer information, standardising names across different languages, and applying matching methods that account for spelling variations, aliases, and transliterations. Comparing additional identifiers, such as dates of birth, nationality, and identification numbers, helps distinguish customers from similarly named individuals. Screening thresholds should also be calibrated and regularly tested to reduce unnecessary alerts without increasing the risk of missing genuine matches.
What Are the AML Screening Requirements in the US?
US AML requirements primarily arise under the Bank Secrecy Act (BSA), applicable FinCEN regulations, and sanctions programmes administered by the Office of Foreign Assets Control (OFAC). Covered financial institutions must maintain risk-based AML programmes, conduct customer due diligence, monitor for suspicious activity, and fulfil applicable reporting obligations. OFAC sanctions restrictions also apply to persons subject to US jurisdiction. US regulations do not impose one universal screening method, list combination, or frequency on every business. Requirements depend on the institution's regulatory category, applicable sanctions, and assessed risks.
Are PEP and Adverse Media Checks Mandatory in the US?
No, not as universal screening requirements for every customer. FinCEN's CDD Rule does not categorically require covered financial institutions to conduct adverse media searches or particular screenings for all customers. Similarly, US banking regulators clarify that PEP status alone does not automatically require additional due diligence under the general CDD Rule. However, institutions must still assess customer risks and apply appropriate controls.