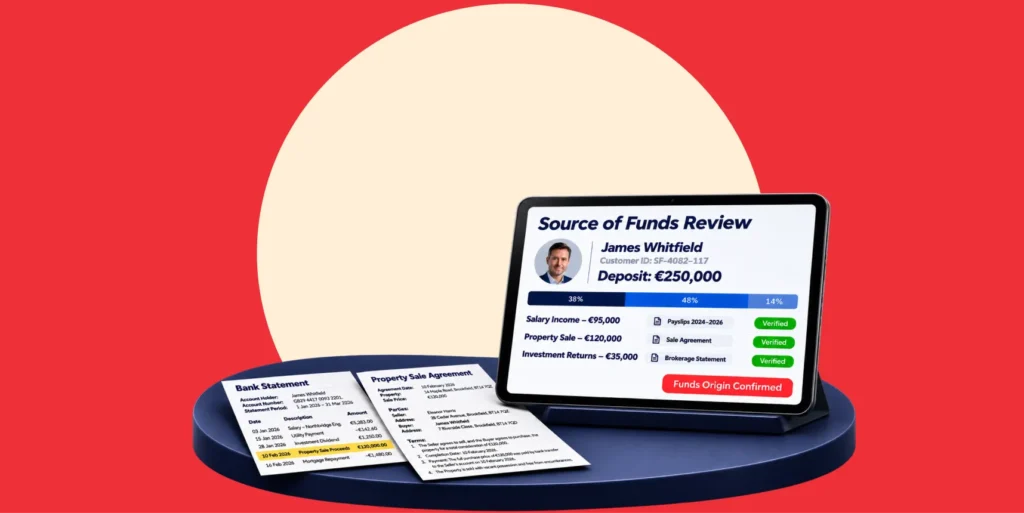

Source of funds (SoF) explains how a customer obtained the money or assets used in a particular transaction. Establishing that source helps businesses assess whether a payment fits the customer’s circumstances and identify inconsistencies that may require further investigation.
SoF doesn’t mean identifying a bank account through which money was transferred. It connects the customer’s explanation of such funds, such as salary, business income, or a property sale, to the relevant evidence shared by the customer and the funds involved.
This guide explains when further enquiries may be needed, how to assess supporting documents, and when to escalate unresolved concerns.
What is a Source of Funds?
Source of funds refers to how and where the money or assets involved in a particular transaction were obtained. It is not simply the account used to send the payment. The account shows where the transfer came from, while the source of funds explains the underlying activity that generated the money, such as salary, business income, investment returns, a property sale, inheritance, or a gift. Source of funds remains the main focus of the assessment, but it may sometimes need to be considered alongside the customer’s source of wealth.
| Source of Funds | Source of Wealth | |
| What it explains | Where the money or assets involved in a particular transaction came from | How the customer accumulated their overall wealth |
| Scope | A specific payment, transfer or investment | The customer’s wider financial position |
| Examples | Salary, property sale, dividend, loan, inheritance or gift | Business ownership, long-term income, investments, property holdings or inherited wealth |
For example, a customer may have built their wealth through a long-established business but fund a particular investment with the proceeds from the recent sale of a property. The SoF and SoW are different, but they can still form a consistent financial picture when supported by suitable evidence.
FATF’s official guidance also distinguishes the two concepts. Source of wealth concerns the origin of a person’s total wealth, while source of funds concerns the particular money or assets involved in a transaction or business relationship. FATF further notes that knowing which financial institution transferred the money is not enough to establish its underlying origin.
Within the EU, Regulation (EU)2024/1624 which applies from 10 July 2027, includes obtaining additional information on the source of funds and source of wealth of the customer and beneficial owners among the enhanced due diligence measures for higher-risk situations.
However, determining the source of funds can be complex, specifically when transactions are carried out via shell or offshore companies. In these instances, companies must dig deep to comply with AML standards, developing facts ranging from how the company’s financial workflow works, who the beneficial owners are, and where they invest funds.
Despite the complexities in establishing the source of funds, companies need to have rigid verification checks at their disposal that are sufficient to determine the source of funds as well as to meet AML obligations. However, failure to cope with these situations could lead to legal proceedings, hefty fines, sanctions, and reputational damage.
Why Are SoFs Important?
Source of fund checks plays a critical role in the fight against money laundering, terrorist financing, and other financial crimes since it helps businesses establish better understanding of their customers, and resolve any suspicions they may have or reach a conclusion in an investigation.
FATF Recommendation 10 requires financial institutions to scrutinise transactions throughout a business relationship and, where necessary, examine the source of funds. For higher-risk relationships, the FATF requires enhanced measures proportionate to the risk. Its guidance on Recommendation 12 explains the requirement to take reasonable measures to establish the source of wealth and source of funds for foreign politically exposed persons.
Diving deep, SoF can provide compliance teams with a clear picture of risk profile of a customer, helping them investigate proceeds of crime and suspicious activities while making informed decisions.
How to Conduct Source of Funds Checks
Businesses should take a risk-based approach to determining the source of funds. Companies can make optimal use of their resources by requesting SoF only on a risk basis, rather than a blanket requirement for every customer. Higher-risk relationships and transactions may require more detailed enquiries and stronger supporting evidence.
There is no universal transaction value that automatically determines when an SoF check is required. A check may instead be appropriate where a transaction is unusually large or complex, forms part of an unusual pattern, involves an unexpected third party, has no clear economic or lawful purpose, or does not fit what the business already knows about the customer.
The starting point is the customer’s explanation. The business should understand what generated the funds, when they were obtained, who was involved, and how the money reached the customer. Supporting evidence can then be used to determine whether that explanation holds together.
If the stated source of funds conflicts with the customer’s profile or other available information, investigate and document the discrepancy. Where the applicable legal reporting threshold is met, submit the required report within the relevant deadline. Do not delay reporting solely while awaiting further documents
Common SoF Examples and What Counts as Good Evidence
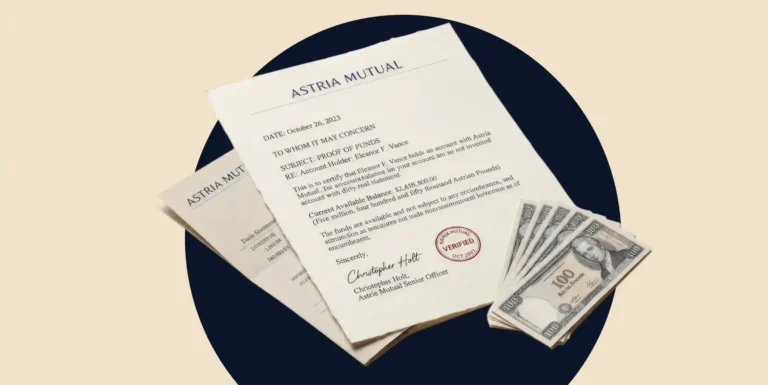
Evidence should relate to the source the customer has claimed. Depending on the circumstances, this may include:
- Bank statements
- Payslips or tax returns
- Investment or capital gains statements
- Loan agreements
- Probate or inheritance records
- Business ownership records
- Property sale and purchase agreements
- Signed documentation supporting gifted funds
AUSTRAC’s official guidance identifies these as examples of information that may help verify SoF and SoW. The aim is not simply to collect more documents. Compliance teams should consider whether the evidence is:
- Relevant: Does it relate to the source the customer has claimed?
- Reliable: Does it come from a credible or independent source where appropriate?
- Sufficient: Does it explain the amount involved rather than only a small part of it?
- Consistent: Does it align with the customer’s profile, transaction history, and other information?
- Traceable: Can the funds be linked from the stated event to the customer and the transaction?
For example, if a customer says that a €500,000 investment came from selling a property, a sale agreement can show that the sale took place. However, it may not, on its own, show that the customer received the money now being invested. Relevant bank records can help connect the sale proceeds to the customer and the transaction under review.
In some cases, understanding the particular funds also requires context about the customer’s wider wealth. If a customer receives a large gift from a relative, the gift may be the immediate source of funds, but the firm may also need to understand whether the relative had the financial means to provide it.
AUSTRAC illustrates this through an official example in which a customer stated that funds were a gift from a relative who had sold an investment property. An unsigned note was not sufficient. The adviser requested a signed gift declaration, the sender’s bank statement showing receipt and transfer of funds, and a property sale record corroborating the involved funds. It also shows that reporting should not be delayed while waiting for additional documents if a reportable suspicion has been formed.
Escalate When the Explanation Does Not Hold Together
Further action may be required where:
- Evidence is missing or incomplete
- Documents conflict with transaction data
- The customer changes their explanation
- The amount does not fit the customer’s known income or business activity
- An unexpected third party cannot be reasonably explained
- The customer is unable or unwilling to provide satisfactory information
The business may first request clarification or additional evidence. If the concern remains, it may need to reassess the customer’s risk, apply enhanced due diligence, increase ongoing monitoring, or escalate the case to the appropriate compliance officer or Money Laundering Reporting Officer.
A discrepancy is not automatic proof of money laundering. It is a reason to investigate. Where the explanation remains unsatisfactory, and the firm forms a reportable suspicion, it should consider whether a suspicious transaction or activity report is required under the law that applies to it. AUSTRAC similarly advises considering a suspicious matter report where a customer cannot or will not provide a satisfactory explanation and a reportable suspicion is formed.
When Should You Establish Source of Funds (SoF)
To implement SoF checks on a risk-based approach, businesses need to establish and implement appropriate know your customer checks to better understand who their customers are and what type of business activities they are involved in. Under the FATF’s risk-based approach recommendations, KYC measures must be proportionate to the level of risk customers pose. This means high-risk entities are subject to enhanced KYC compliance and AML checks, while clients with lower-risk levels should undergo simplified due diligence.
The following are different components of KYC process during which a firm may need to perform an SoF check based on the risk involved:
- Enhanced Due Diligence: At the time of establishing a relationship with a customer, businesses need to conduct due diligence, and if a customer is deemed to be at high risk of money laundering, enhanced due diligence should be conducted. SoF check is an important part of that enhanced due diligence process that requires additional evidence and scrutiny as part of increased scrutiny of high-risk customers.
- Transaction Monitoring: Companies are obliged to monitor financial activities and transactions of their customers to ensure that it matches with customers’ declared purpose and intention of opening that account and declared source of income shared with the company. If a transaction deviates from that known information about a customer, it should be investigated, and SoF should be requested to clear that suspicion.
- High Risk Countries: Transactions with links to high-risk countries for money laundering and highly sanctioned jurisdictions should go through enhanced due diligence due to their potential exposure to sanctions evasion and money laundering. Sanctioned entities from such jurisdictions may attempt to evade restrictions by involving third parties to conduct a transaction on their behalf. Hence, where a transaction is linked to such a jurisdiction, and there’s no apparent economic or legal purpose for it, SoF checks should be conducted. However, where a connection with a sanctioned entity is directly established, apply applicable restrictions and report to relevant authorities.
- Politically Exposed Persons (PEPs): People with a prominent public function and positions that fall in PEP categories are more exposed to money laundering risks, so businesses should assess their source of funds according to applicable regulations as part of enhanced due diligence. These obligations usually extend to their close associates and family members as well.
How Shufti Supports Source of Funds Document Review
SoF checks are an important component of the AML compliance process; however, manually reviewing every SoF document takes a lot of time and keeps legitimate transactions on hold because not every SoF check turns into a suspicious activity.
Shufti’s document verification solution not only checks for authenticity and potential fabrication but also extracts and analyses relevant financial information from the documents and offers actionable insights to enable quick decision-making. Shufti’s coverage spans 240+ countries and territories, helping businesses automate compliance operations and prevent fraud throughout the customer lifecycle.
Book a demo to see how Shufti’s Glocal compliance platform can streamline your operations and enable growth.
Frequently Asked Questions
What is the difference between source of funds and source of wealth?
Source of funds explains where the money for a particular transaction came from, such as salary, a property sale, business income, or a loan. In contrast, source of wealth explains how the customer built their overall wealth over time through employment, business ownership, investments or other means.
Can a business use a customer’s tax return to verify the source of funds?
Yes, a tax return can support income, business earnings, or capital gains, but bank statements or transaction records may still be needed to connect that income to the specific funds being reviewed. AUSTRAC lists tax returns among the evidence that may be used, but the evidence must still be relevant, reliable, and sufficient.
How do source of funds checks differ for individuals and businesses?
For businesses, the review usually checks how the company generated or received the funds, such as trading revenue, an asset sale, investment, or shareholder funding. Supporting evidence may include company accounts, invoices, contracts, and bank statements, whereas for individuals, the reviewer may focus on salary, savings, property sales, gifts, or inheritance.