

 AMLR Solutions
 AMLR Consultation
 EUDI Wallet
 Onboarding
 Ongoing Monitoring
 FRAML
 KYC
 KYB
 KYI
 Age Assurance
 Workforce IAM
 Candidate Verification
 Account Takeover
 Bonus/ Promotion Abuse
 Chargeback Fraud
 Deepfake
 Document Fraud
 Fraud Networks
 Impersonation Fraud
 Money Mule Activity
 Multi-Accounting
 Party Fraud
 Regulatory & Compliance Risks
 Synthetic Identity Fraud
 Adult Content
 Banking
 Crypto
 Fintech
 Forex
 Compliance
 Fraud prevention
 Trust & safety
 Global expansion
 Compliance Officers
 Developers
 Fraud Analysts
 Product Managers
 Journey Builder
 Global Trust Platform
 Customer Profiles
 Vendor Comparison
 IDV Case Management
 AML Case Management
 Regulatory Reporting
 Agentic Rule Builder
 AI Compliance Co-Pilot
 Fraud Analytics
 Fraud Hub
 OCR
 Shufti AI
 Bank Account Verification
 Biometric Duplication
 Database Checks
 Document Intelligence
 Government ID
 Mobile Driver's License
 NFC
 Selfie Liveness
 Brand Personalisation
 Deployment Options
 Identity Methods
 IDV Modes
 Multi-tenancy
 On-Premise IDV
 Secure Capture
 Shufti MCP


Know Your Customer
Verify Customers Faster Without Opening CDD Gaps
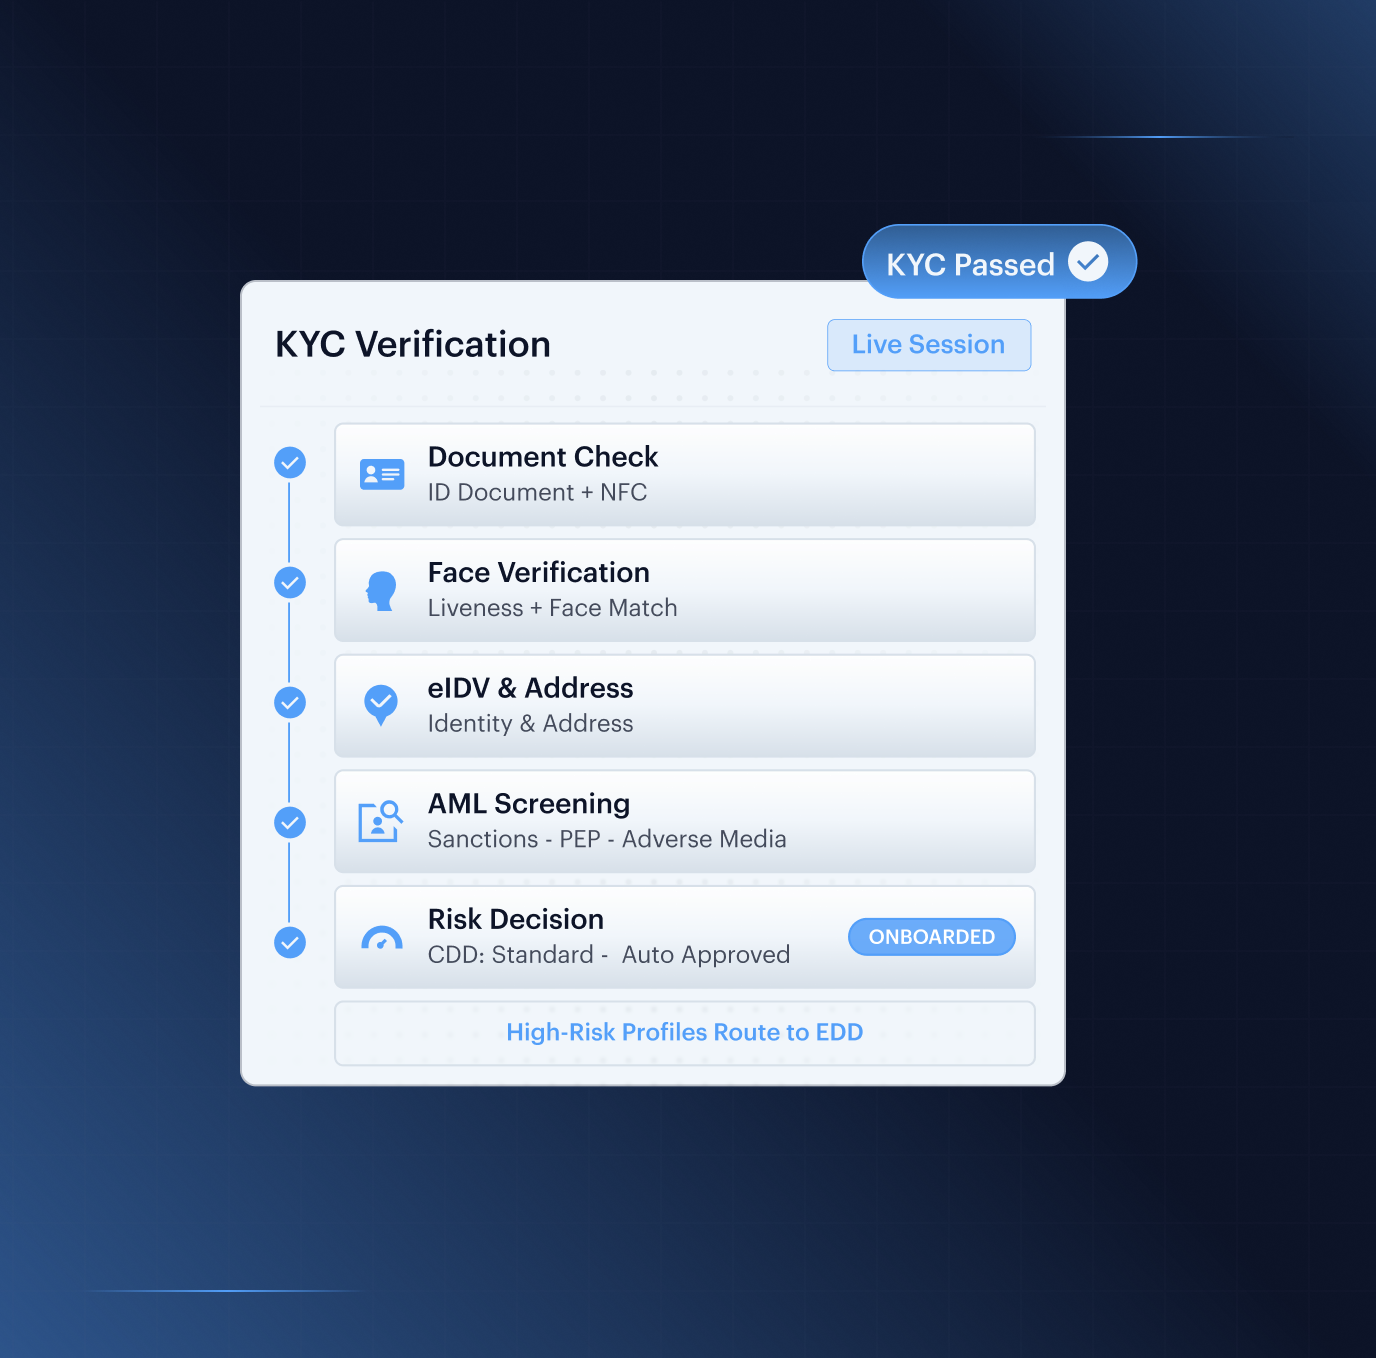
Shufti unifies document, facial, eIDV, NFC, address verification, and AML screening in one KYC workflow. It helps businesses verify customers faster, screen risk at onboarding, and escalate high-risk cases through an AI Compliance Co-Pilot, without relying on multiple vendors.
VERIFIED AT SCALE
The World’s Largest KYC Verification Network


One Platform For The Entire KYC Lifecycle
Synthetic Fraud Stopped Early
AI-generated documents and synthetic identities are raising onboarding risk. Shufti checks Synthetic Identity Fraud, originality, tampering, GenAI signals, replay attempts, & face liveness to detect deepfakes, injection, and synthetic document fraud before approval.
Tiered CDD Without Drop-Off
Risk-based CDD should not force every customer through the same checks. Shufti’s KYC platform lets teams configure thresholds and routing, so low-risk users move faster while higher-risk profiles step up to NFC, eIDV, AML, or Customer Due Diligence software review.
Audit Trails With Context
Fragmented KYC stacks weaken evidence and slow compliance teams down. Shufti’s identity verification software connects identity checks, AML screening, alerts, reason codes, and case context into audit-ready records analysts can act on quickly.
EXPLORE THE STACK
Build A KYC Stack Without Stitching Multiple KYC Vendors
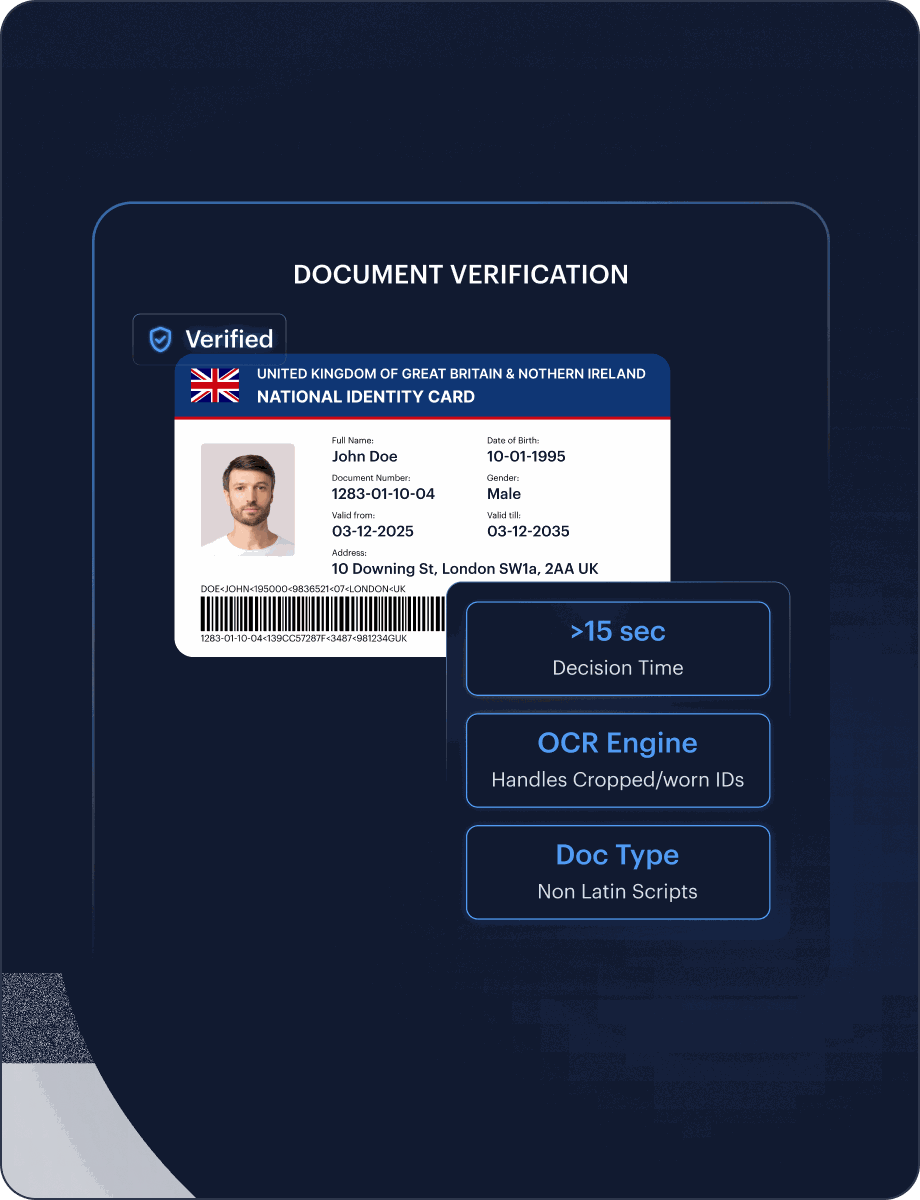
Verify customers with the right identity checks
Confirm real users with document, biometric, NFC, address, and doc-less checks, then step up verification when risk or regulation requires it.
-
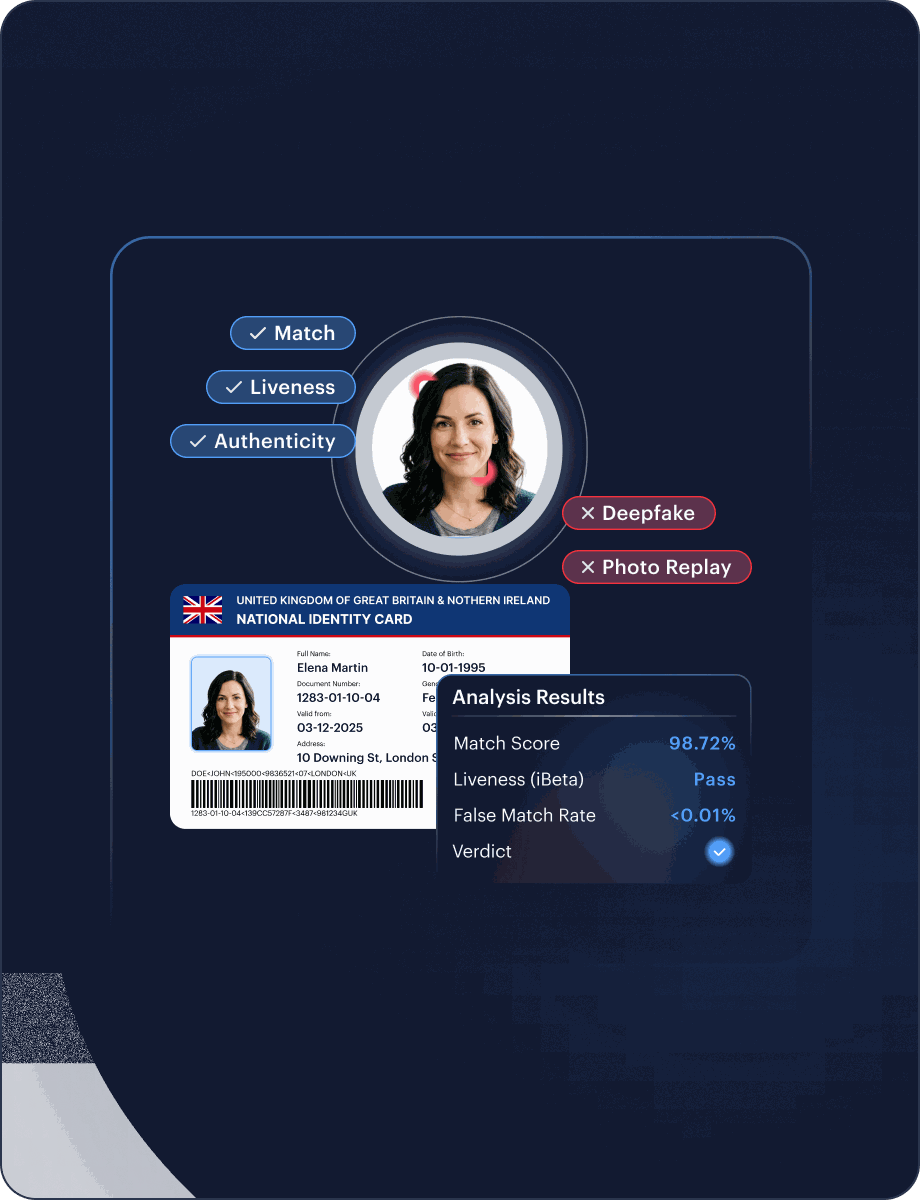
Verify government-issued IDs and supporting documents with in-house OCR, originality checks, tamper detection, and review-ready reason codes. Source-backed public metrics include <15s decision time, 150+ languages, 99% OCR accuracy, and 240+ regions actively processed covered.
-
Match a live selfie to the ID photo and use iBeta-certified liveness, 3D depth/shape analysis, and deepfake/replay/injection defense to confirm real user presence.
-
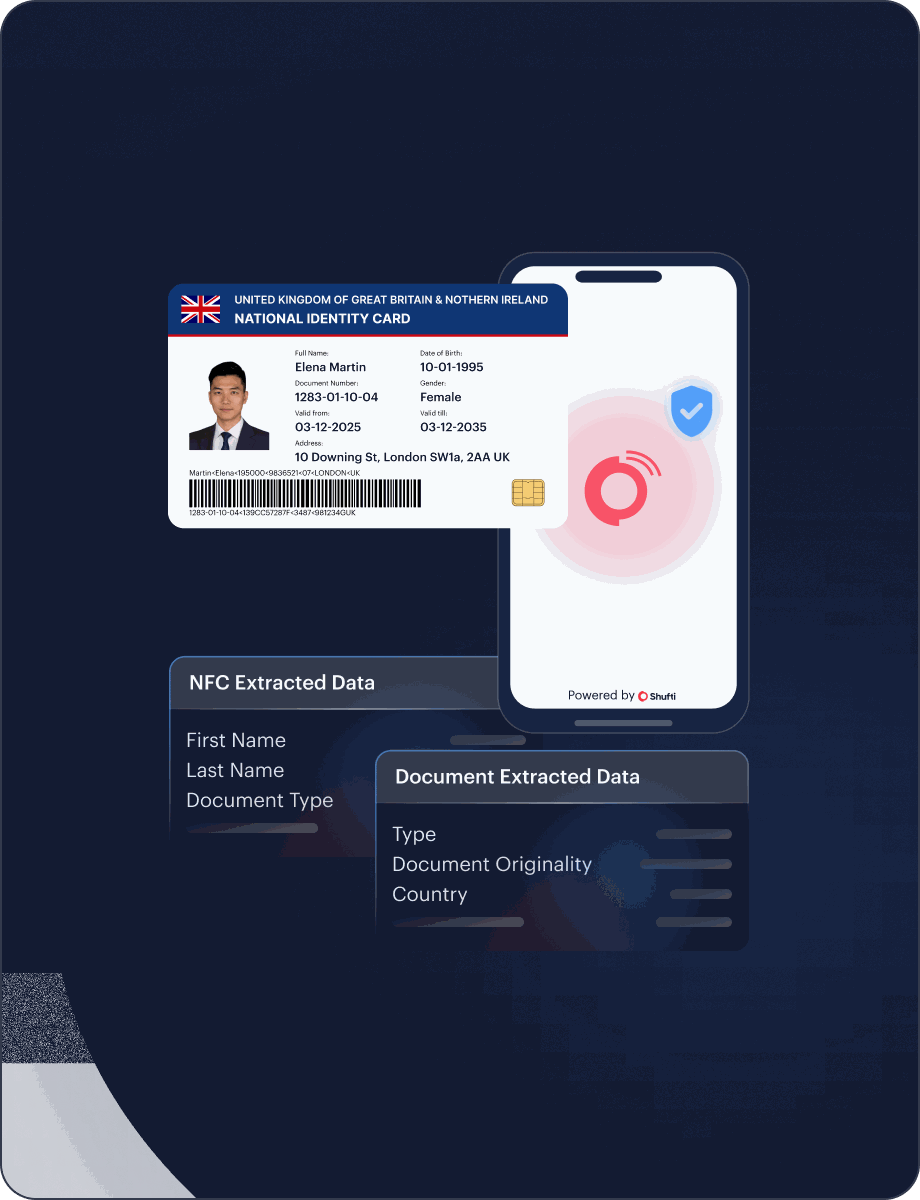
Read chip-stored identity data from supported ePassports and NFC IDs for chip-level credential assurance, then compare the secure chip data against the user and document flow.
-
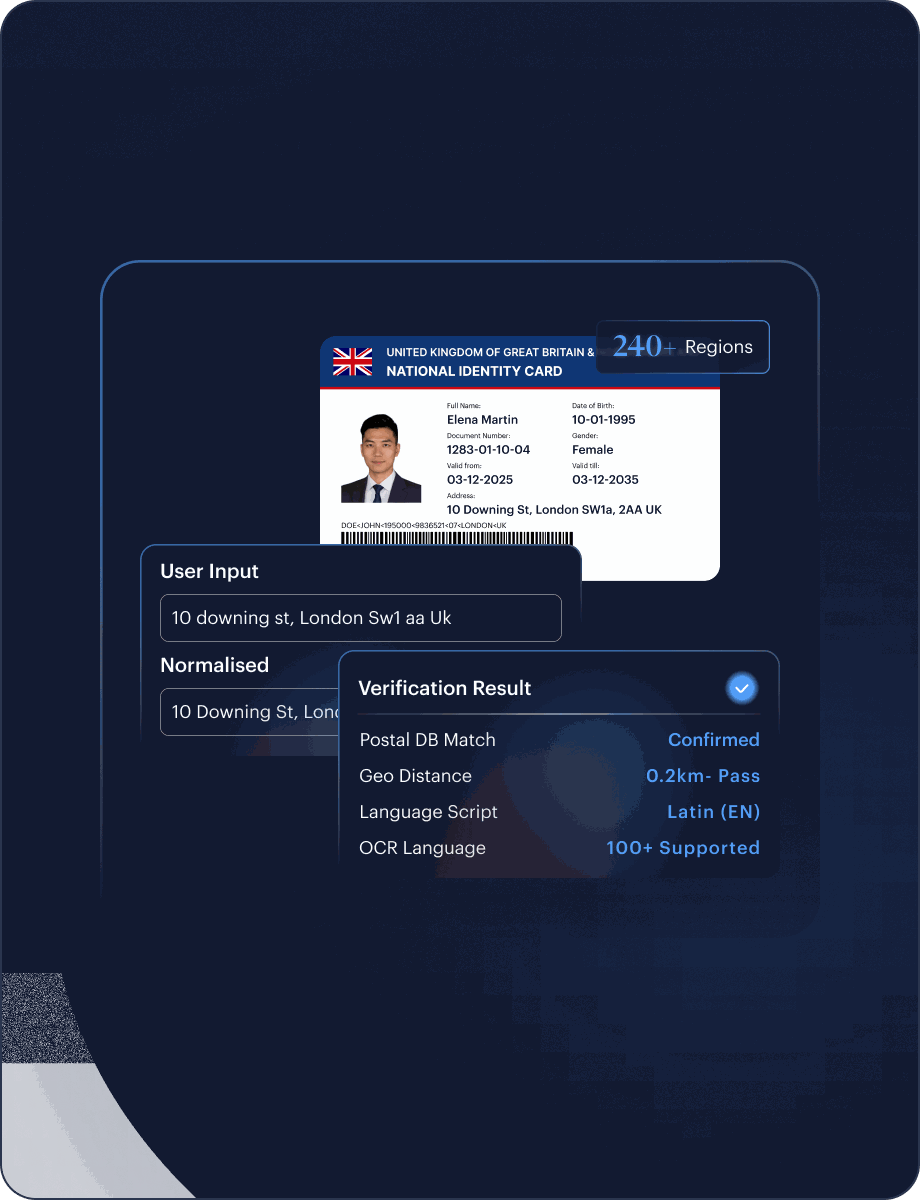
Validate proof of address as part of KYC for jurisdictions or risk tiers that require residential address evidence.
-
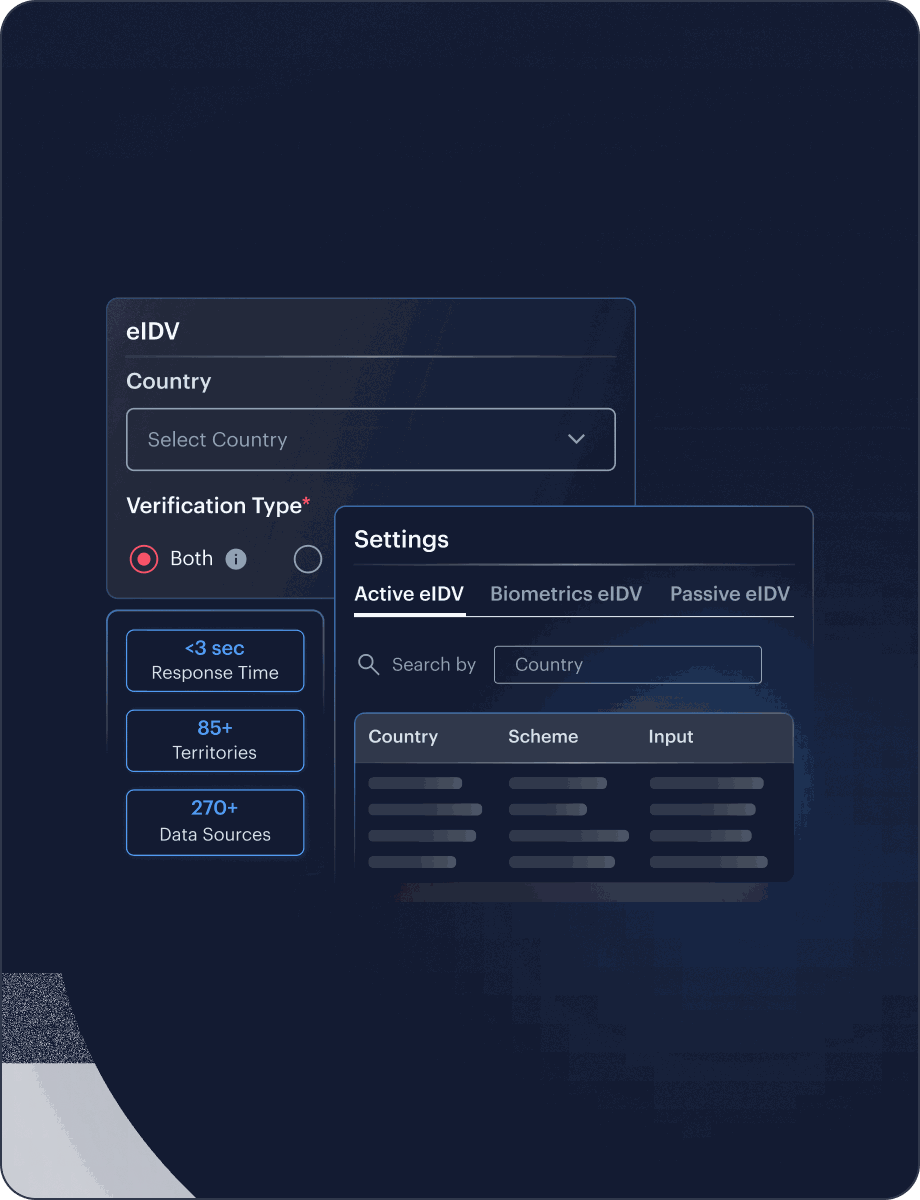
Verify users through doc-less identity checks connected to eIDs, mobile wallets, and authoritative data sources; Shufti lists <3s response time, 85+ territories, and 270+ data sources.


Escalate high-risk customers and business relationships into deeper checks
Use this tab for higher-risk individual customers, corporate customers, UBO checks, investor onboarding, or EDD cases where standard KYC is not enough.
-
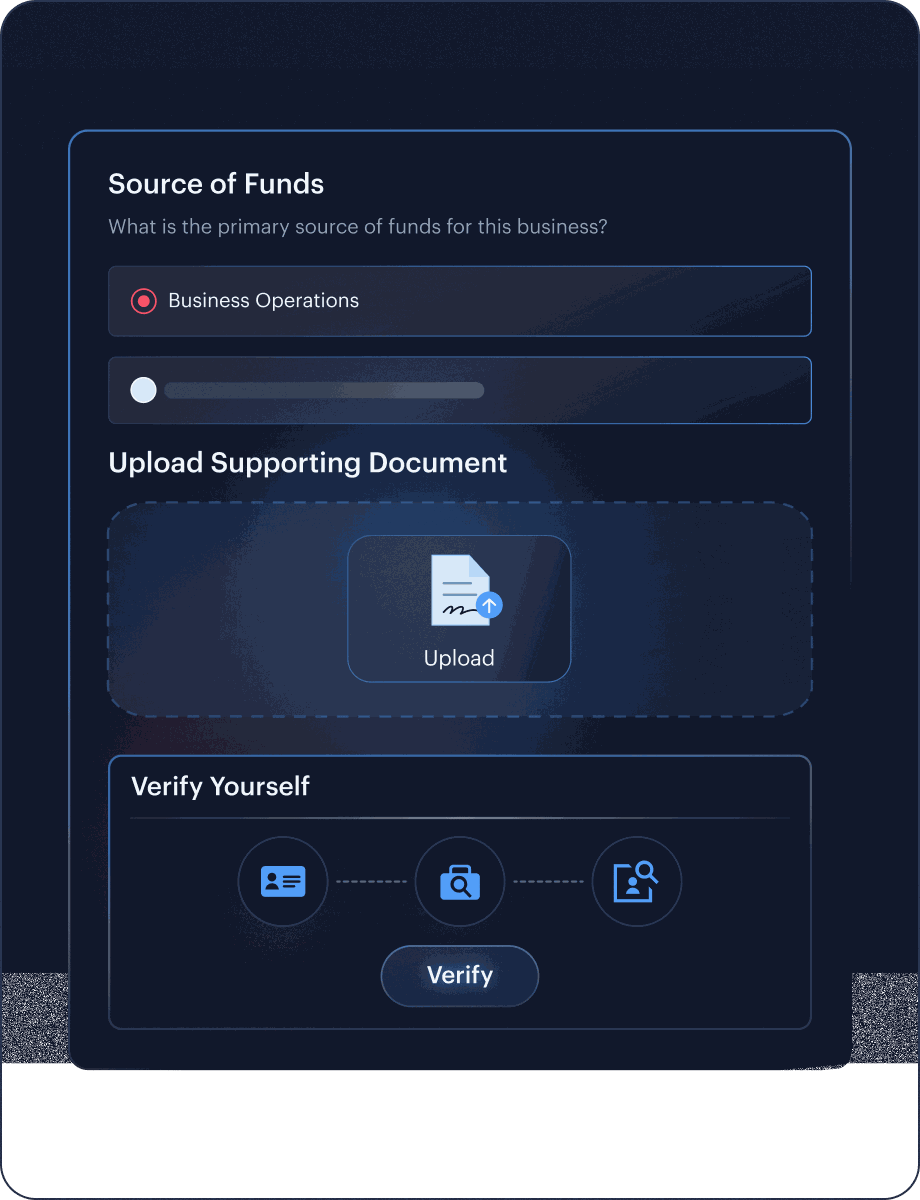
Route high-risk customers to EDD software workflows that can include additional documents, source-of-funds/source-of-wealth evidence, adverse media review, and analyst decisioning.
-
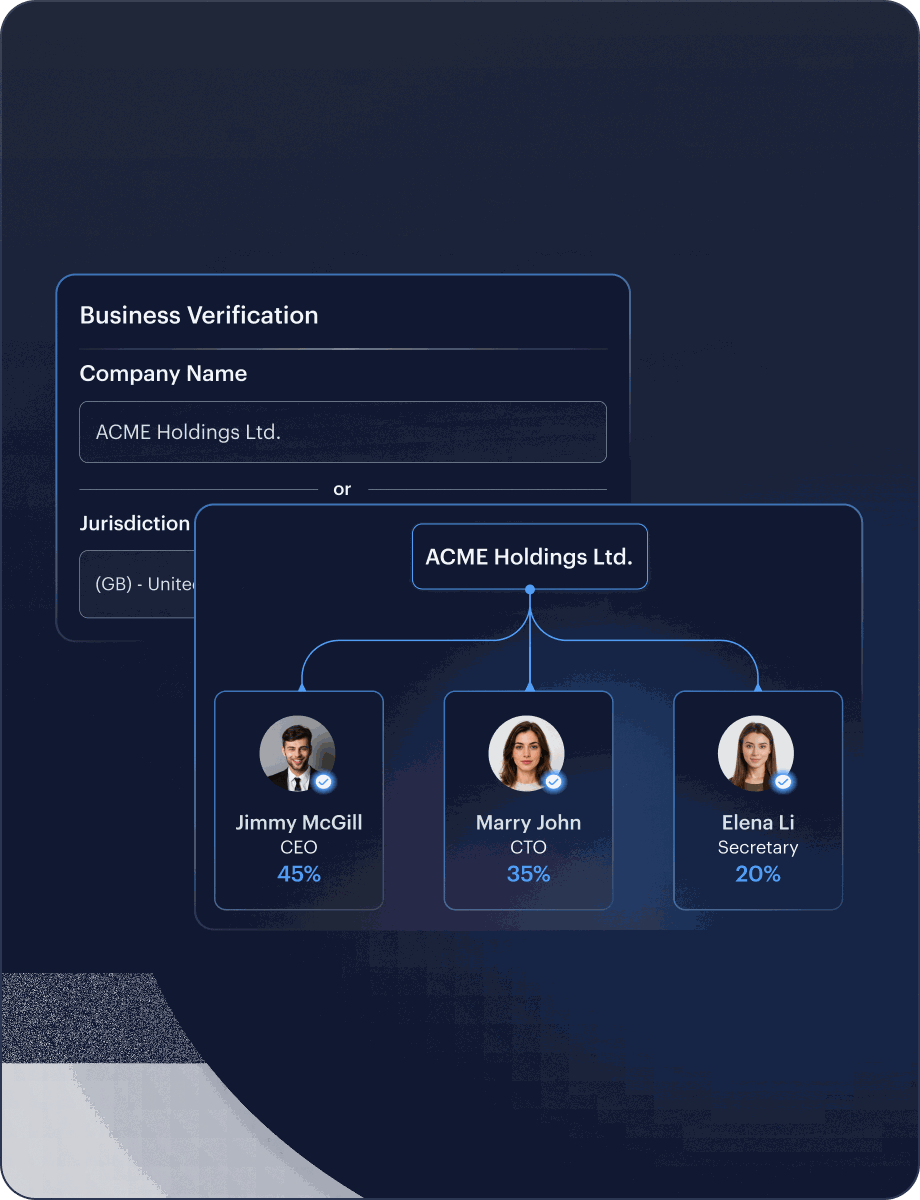
For corporate customers, verify business registration, ownership/control structures, directors, and UBO evidence before opening the relationship.
-
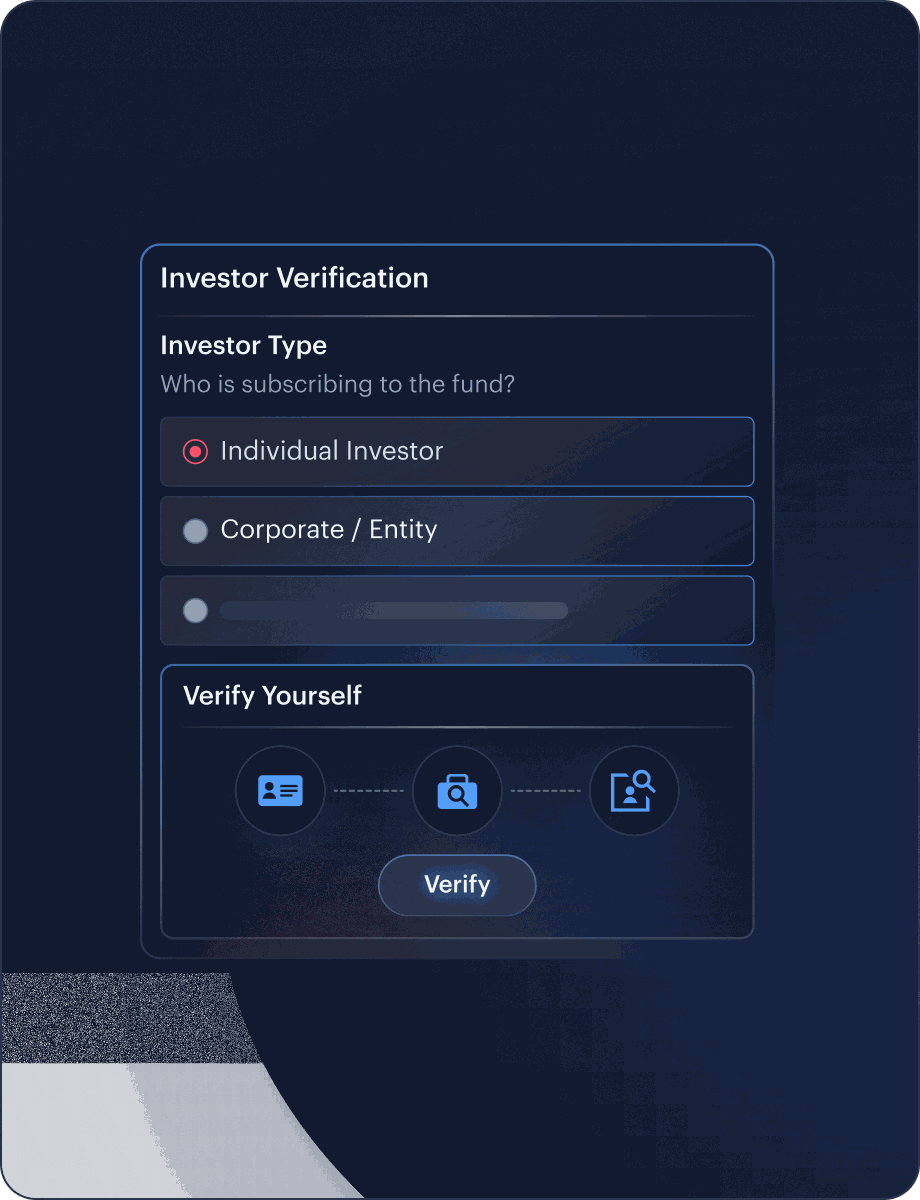
For funds and investment platforms, combine investor KYC, business/entity checks, and AML screening in one onboarding path.


Screen at onboarding, monitor after approval
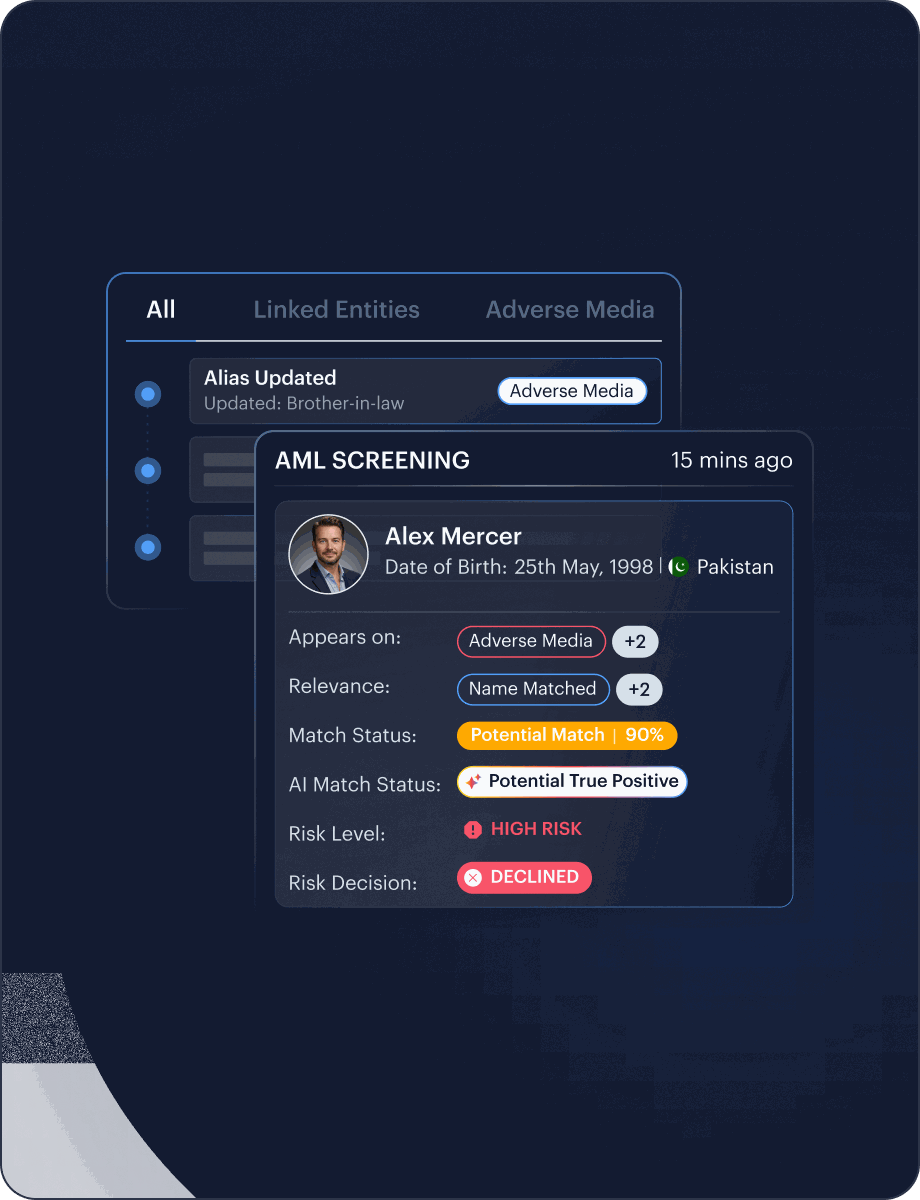
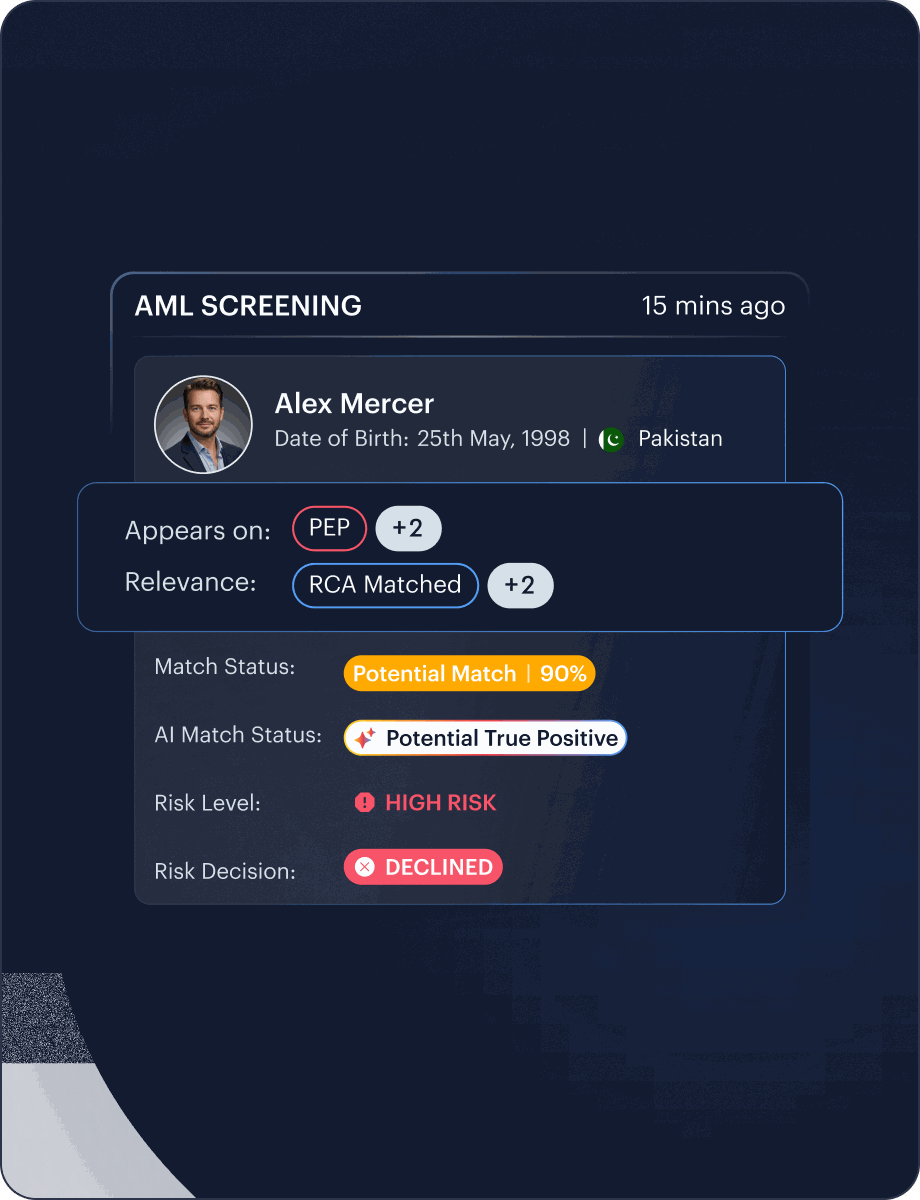
KYC should not stop after document capture. Run sanctions, watchlist, PEP/RCA, and adverse media checks alongside identity verification, then continue monitoring when regulations or internal policy require it.
-
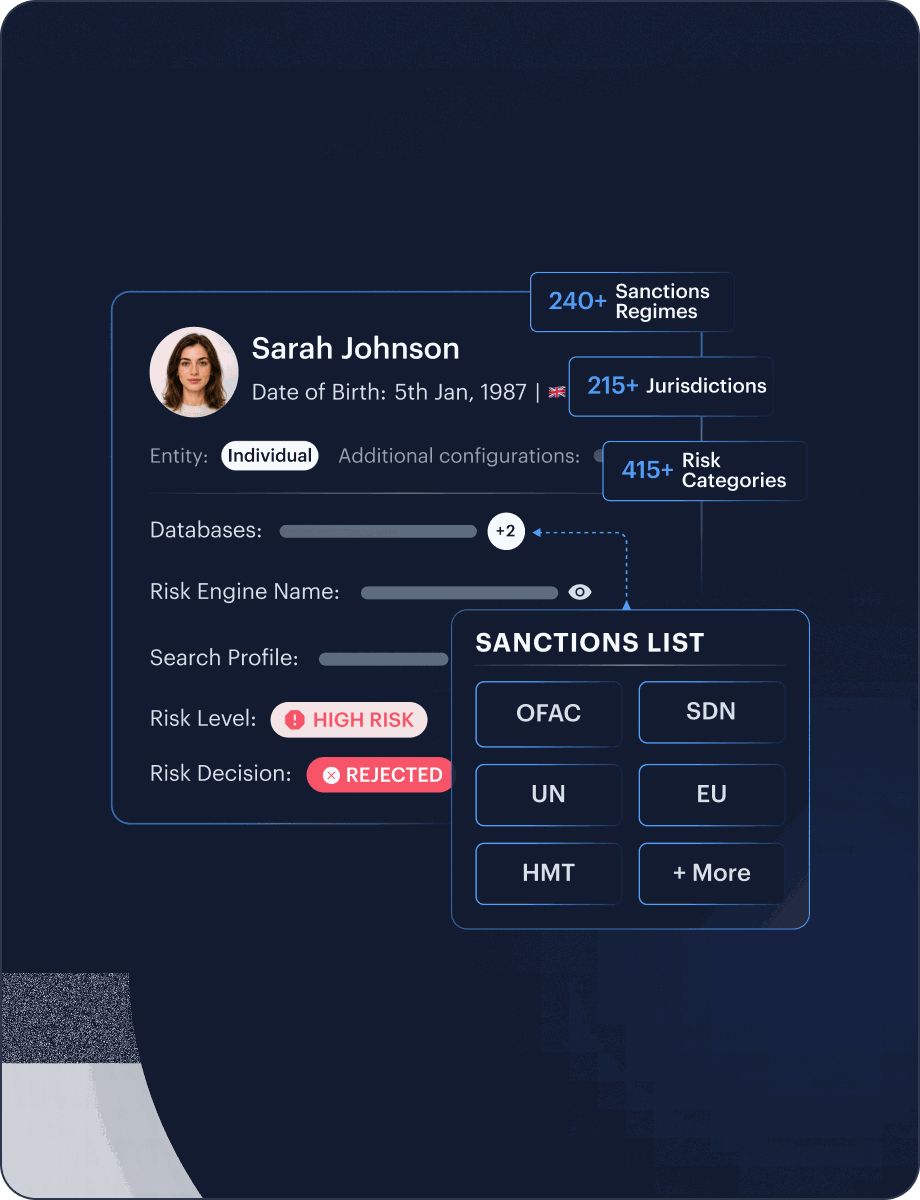
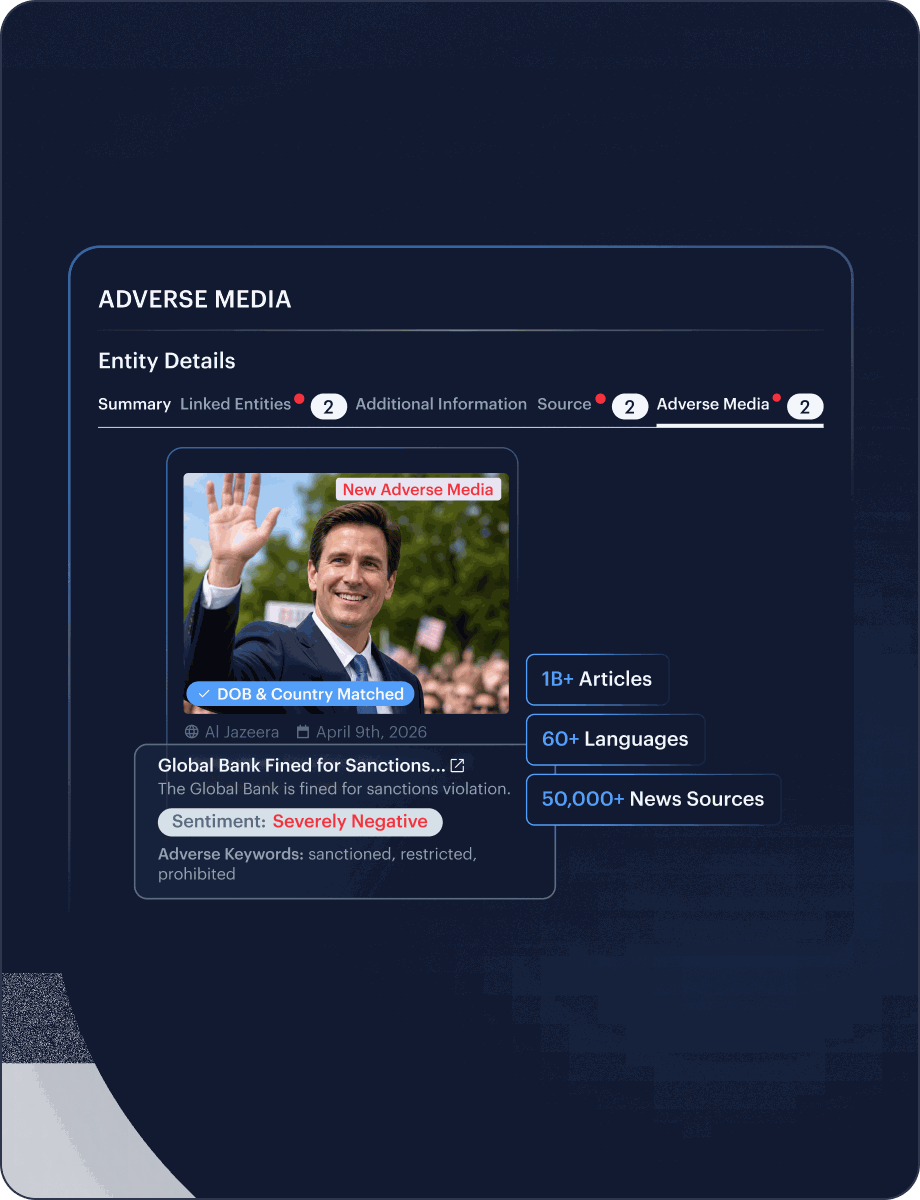
Screen individuals and entities with identity-aware matching, sanctions, watchlists, PEP/RCA intelligence, adverse media, case context, and audit-ready alert information. Shufti lists 3,500+ watchlists, 200+ sanctions regimes, and 50,000+ media sources.
-
Identify politically exposed persons, relatives, and close associates during onboarding and monitor changes after approval.
-
Screen against global sanctions coverage, including UN, OFAC, EU, HMT, DFAT, SECO, and additional sanctions regimes.
-
Surface relevant negative news across global and local sources and classify media exposure by risk theme.
-
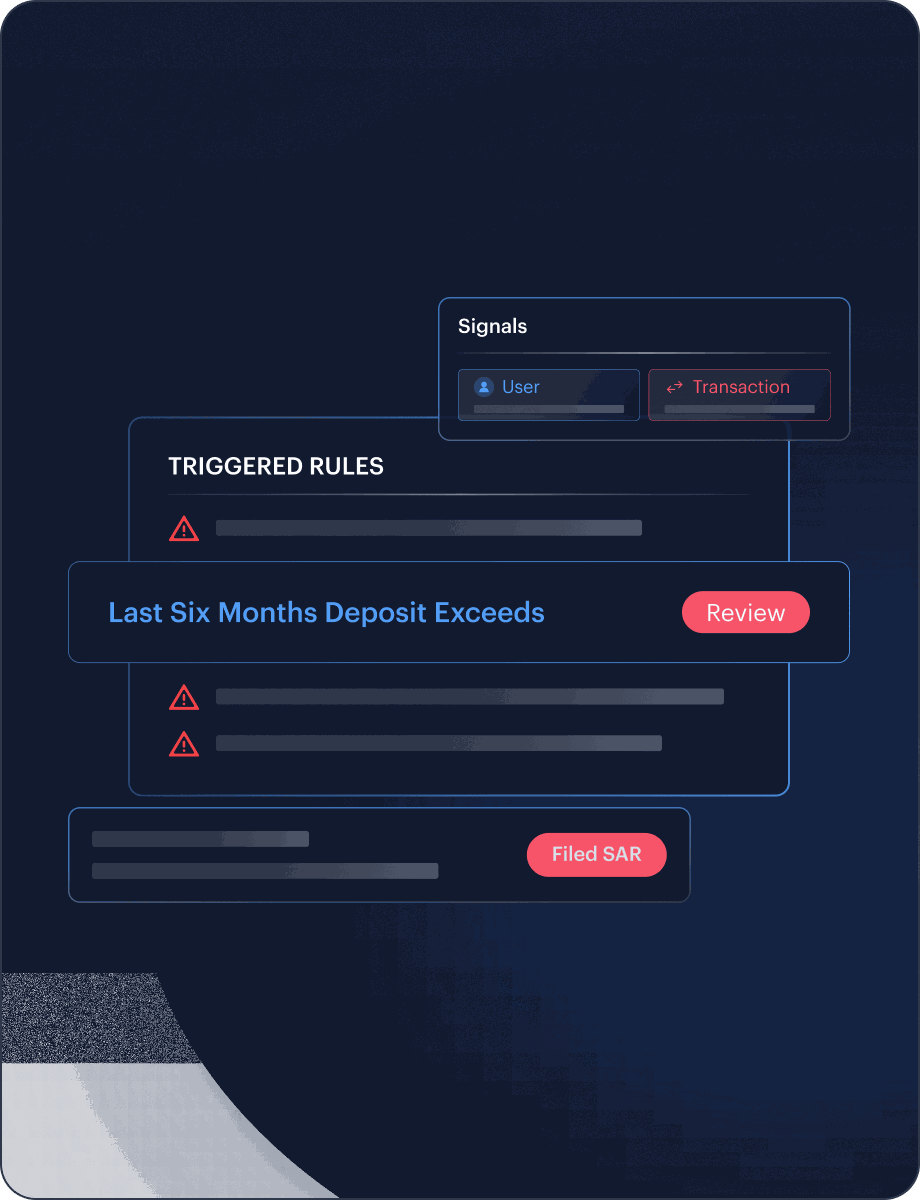
Extend the KYC risk profile into post-onboarding monitoring for suspicious transaction behavior and evidence-led reporting.


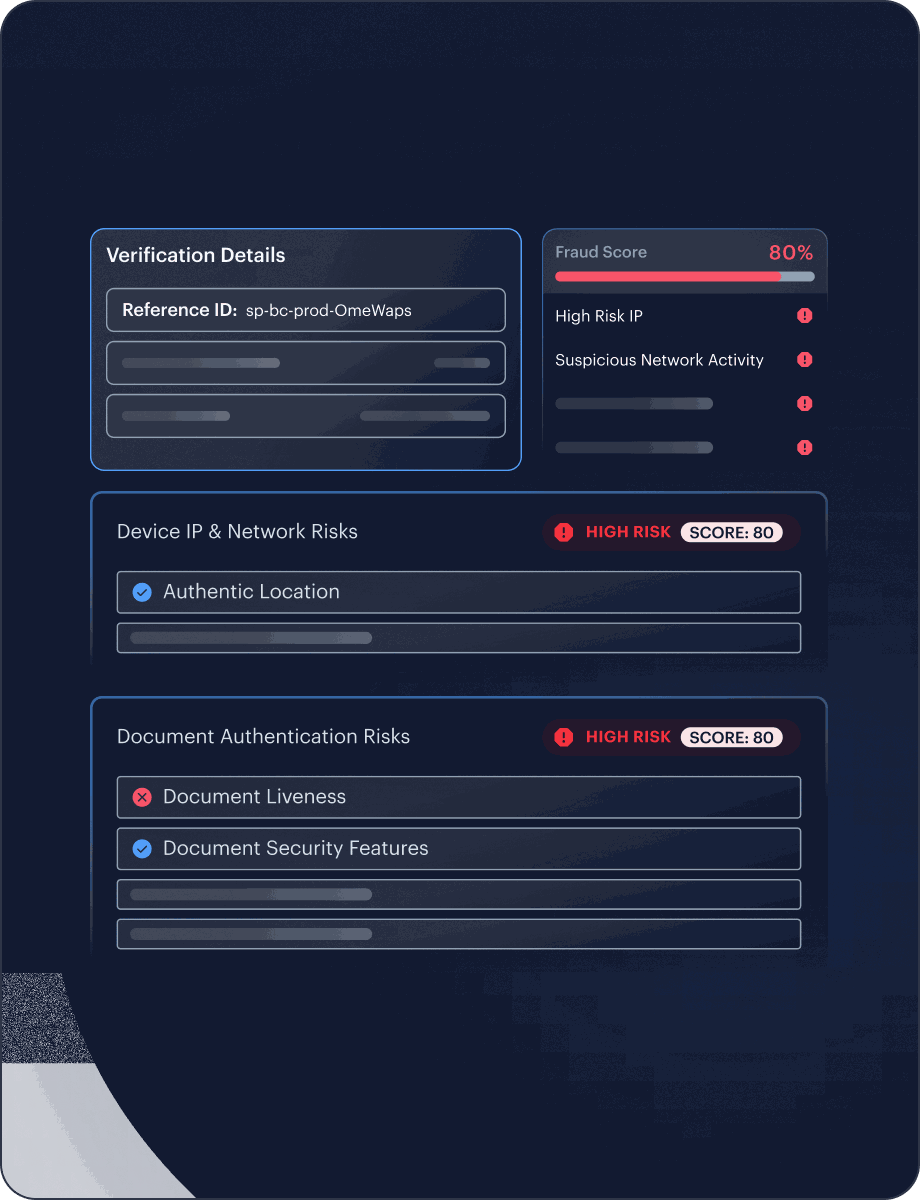
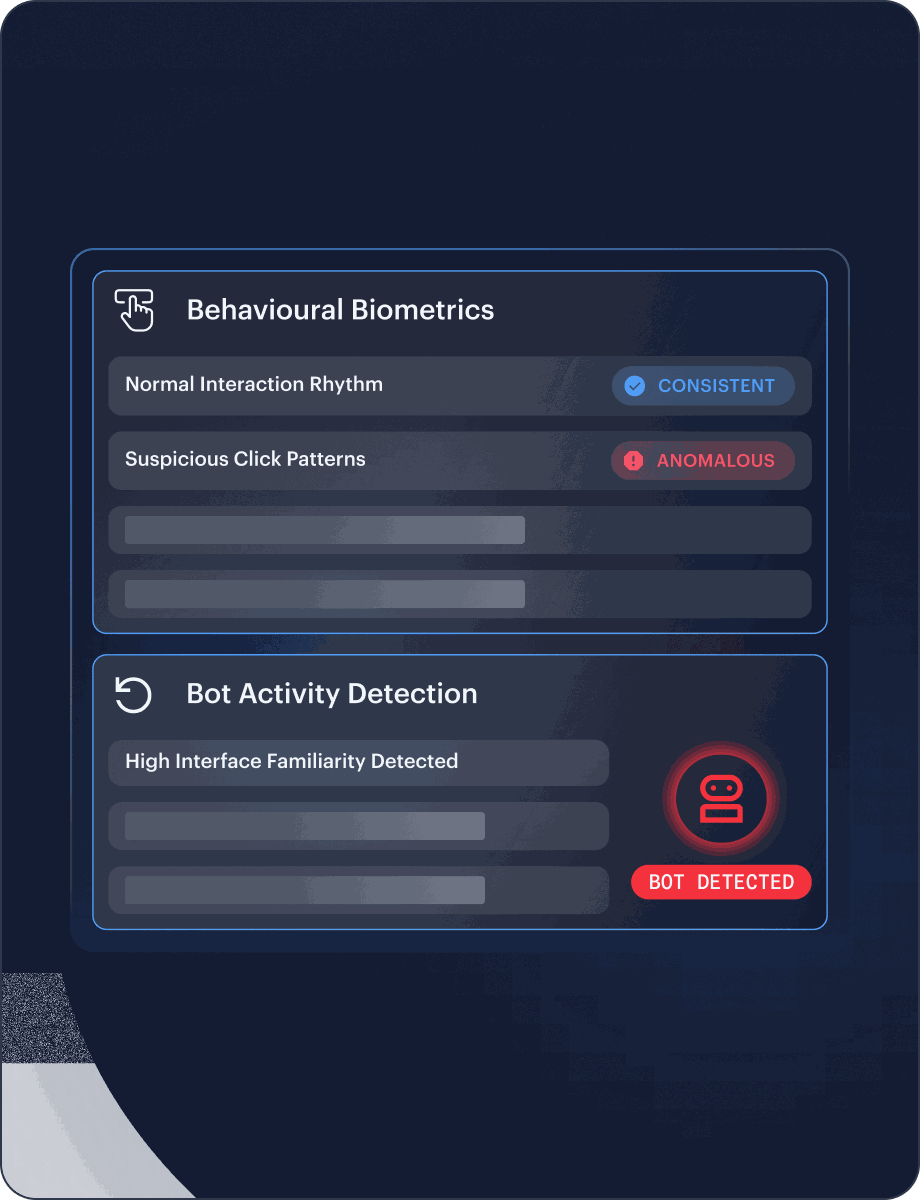
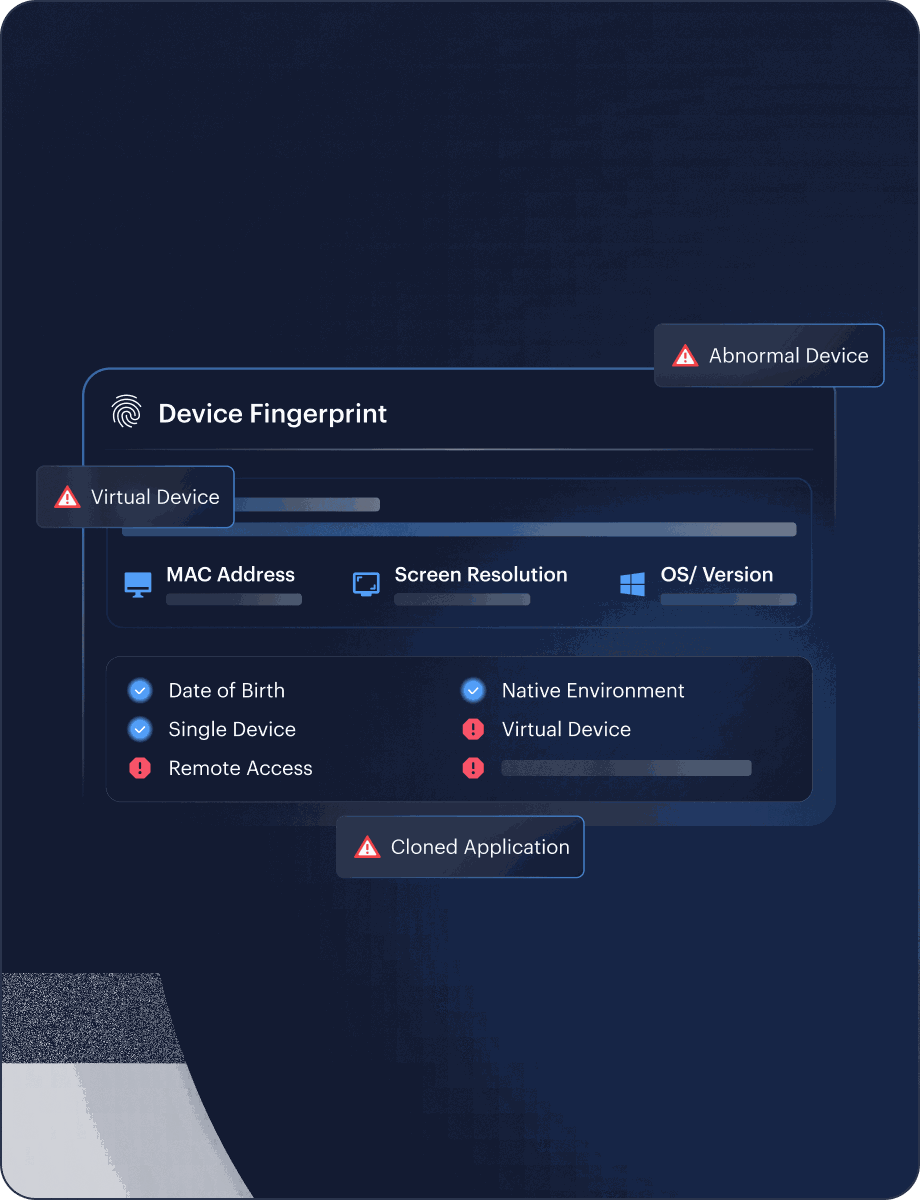
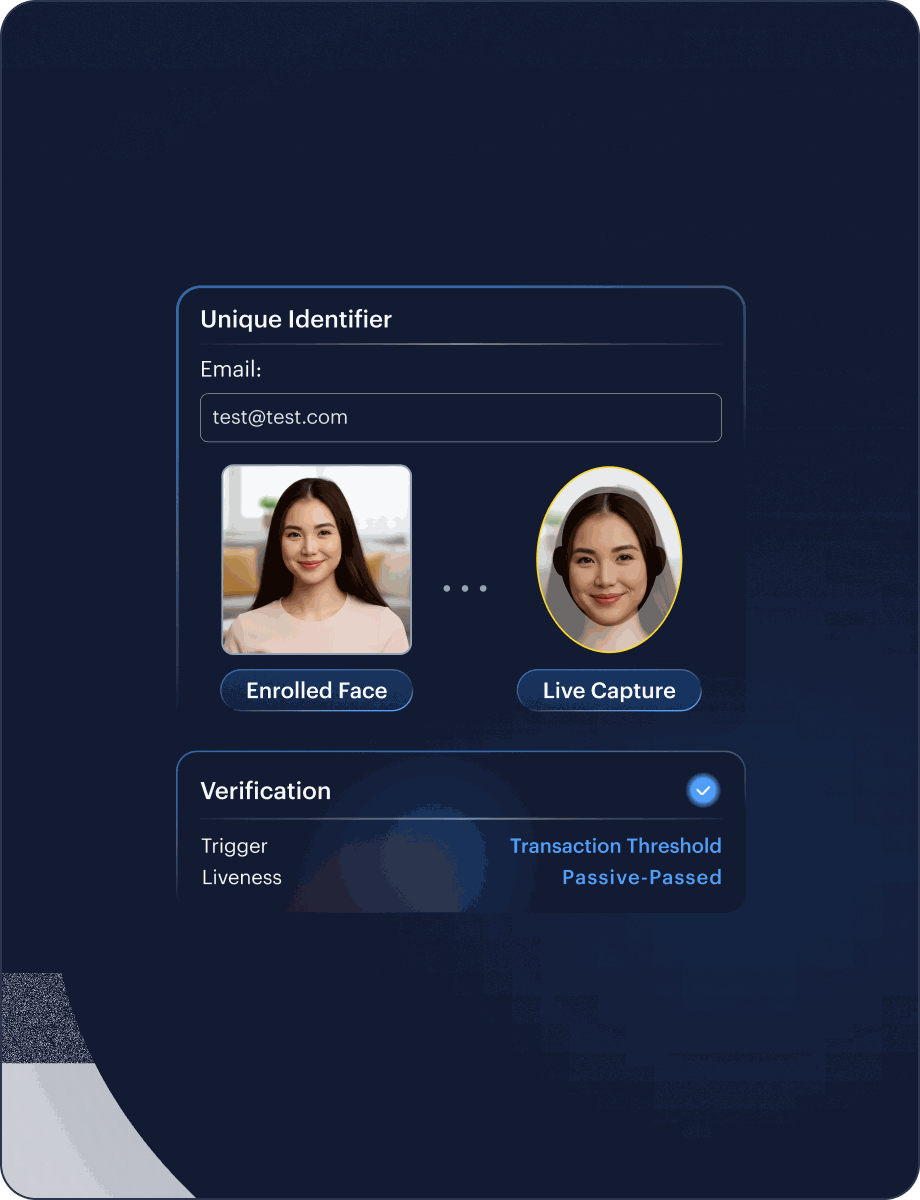
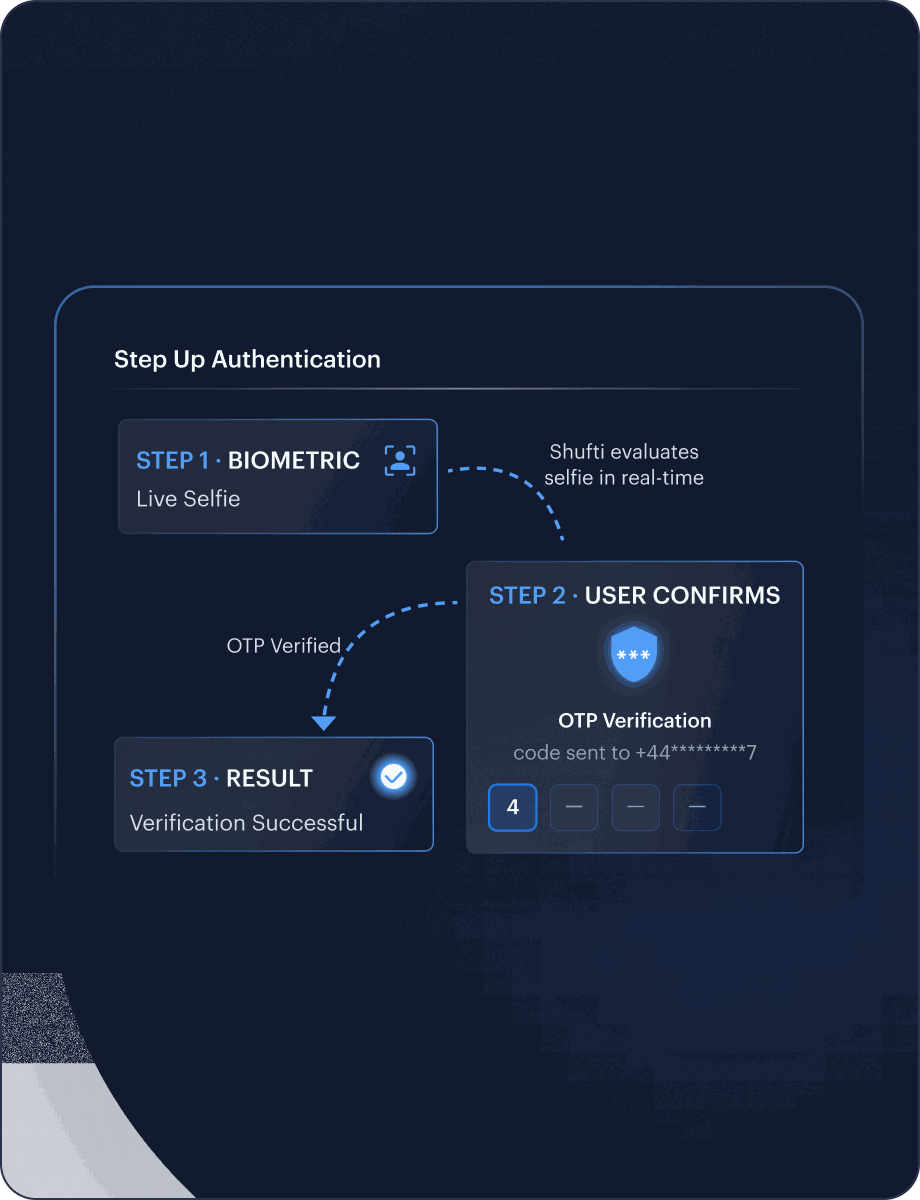
Stop identity fraud before the account is activated
Layer device, behavior, replay, liveness, and re-authentication controls over the KYC flow to catch fraud that a document-only check can miss.
-
Bring fraud signals from document forensics, biometrics, device, behavior, and injection defense into the verification journey.
-
Detects suspicious interaction patterns, bots, and automated submissions during the verification session.
-
Assess whether the onboarding device looks genuine, spoofed, virtualized, or connected to prior risky behavior.
-
For returning users, compare a live selfie against the enrolled profile to support re-KYC, account recovery, or step-up verification.
-
Trigger OTP or biometric step-up when a risk score, jurisdiction, or transaction context requires stronger assurance.


Everything You Need To Know About Your Customer
Build a compliant KYC stack from a single integration. One KYC solution combines document verification, biometric checks, AML screening, and ongoing monitoring across every jurisdiction you operate in.
Compliance Officer
Audit-ready evidence on every verification, structured for regulatory inspection across every jurisdiction you operate in.
Product Manager
Configurable verification flows that balance speed against risk tolerance, without rebuilding the integration each time.
Developer
REST API, mobile SDKs, and sandbox access. First verification call within hours of integration start.
Fraud Analyst
Pre-scored evidence and fraud signals on every flagged case, so your team reviews decisions, not raw submissions.
Detect Every Fraud Type Targeting Your Platform
Deepfake
AI-generated faces and synthetically forged documents bypass legacy liveness checks at scale. Shufti's passive liveness & document forensics detects synthetic media before it reaches your onboarding flow.
Identity Fraud
Credential theft, blended synthetic identities, and manipulated documents exploit gaps in manual review. Shufti's layered verification surfaces fraud signals before accounts are created.
Account & Platform Abuse
Duplicate registrations, bot-driven sign-ups, and referral exploits erode platform economics. Shufti links device, identity, and behavioural signals to flag abuse rings at scale.
Transaction & Payment Fraud
False chargeback claims, money mule networks, and sanctions evasion expose your business to financial and regulatory risk. Shufti ties identity verification directly to transaction context.
HOW IT WORKS
How Shufti Processes KYC Checks Without Extra Vendor Handoffs
01
STEP 01
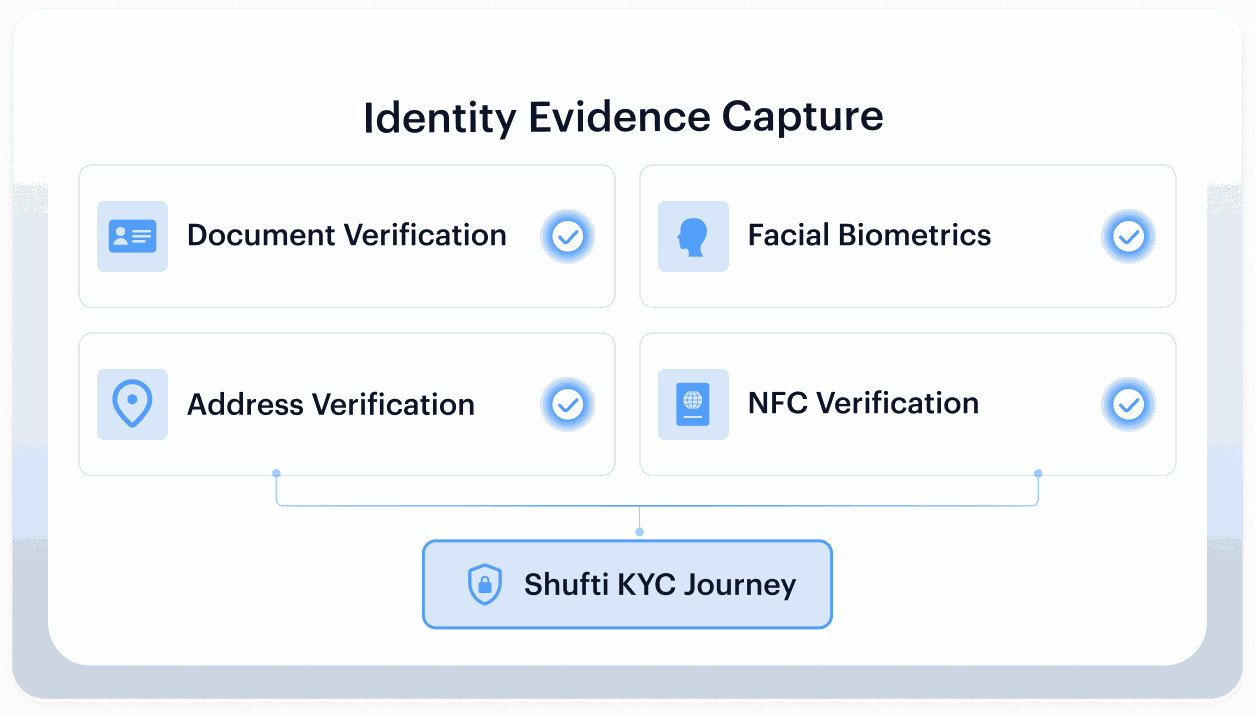
Customer Submits Identity Evidence
The user captures or uploads an ID document, selfie, address proof, eID credentials, or other required evidence through the configured Shufti journey.
02
STEP 02
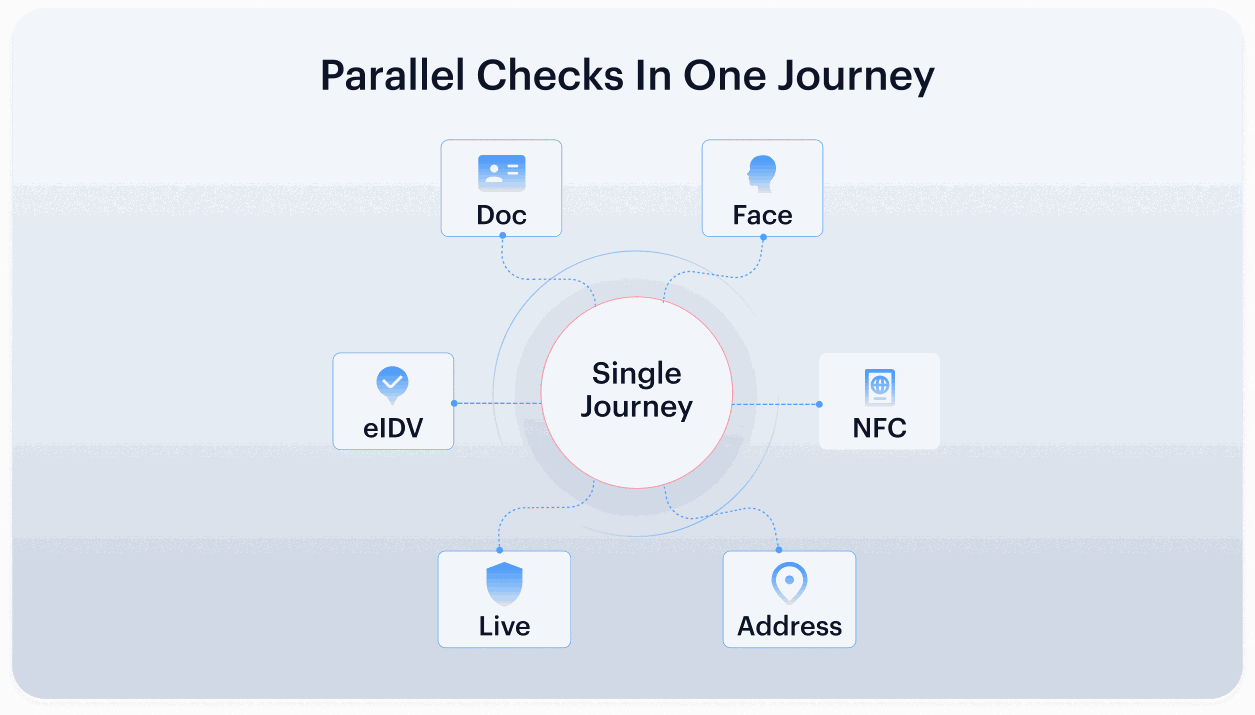
Document, Biometric, and Data Checks Run in the same Journey
Shufti checks document quality, authenticity, field extraction, face match, liveness, and optional NFC/eIDV signals based on the risk tier and jurisdiction.
03
STEP 03
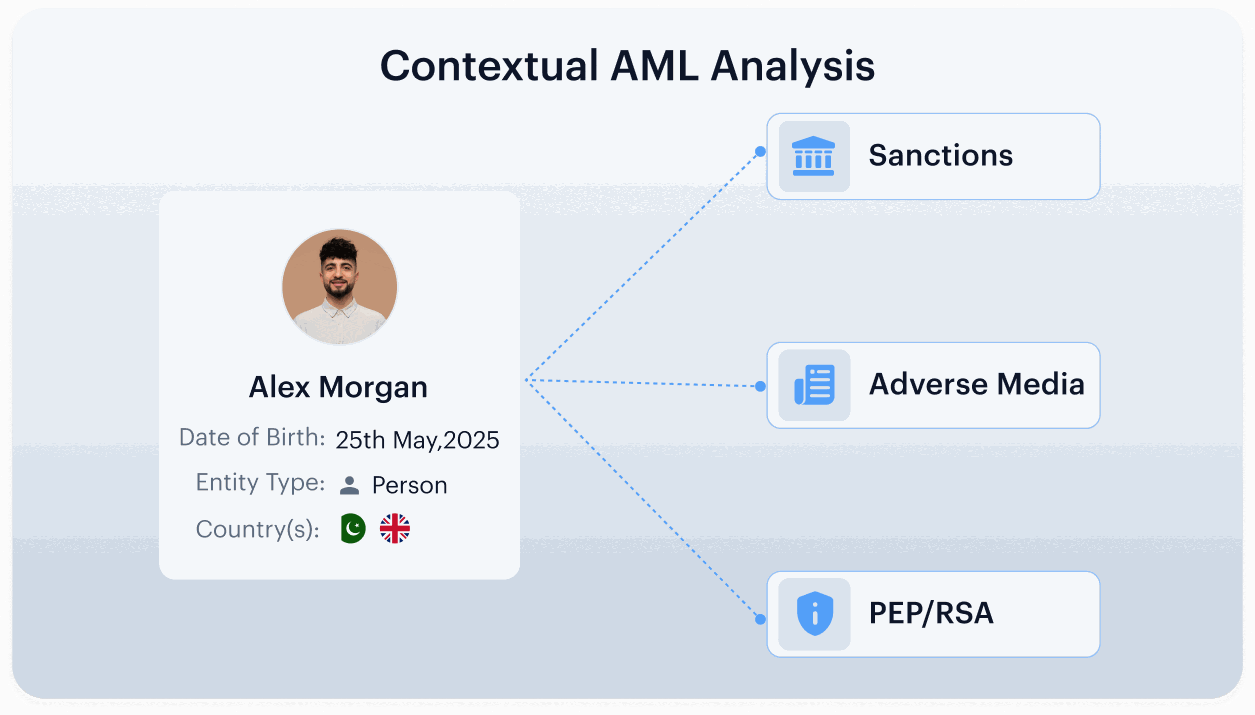
AML Screening Attaches Risk Context
Sanctions, watchlist, PEP/RCA, and adverse media checks create an identity-aware AML profile instead of a disconnected alert.
04
STEP 04
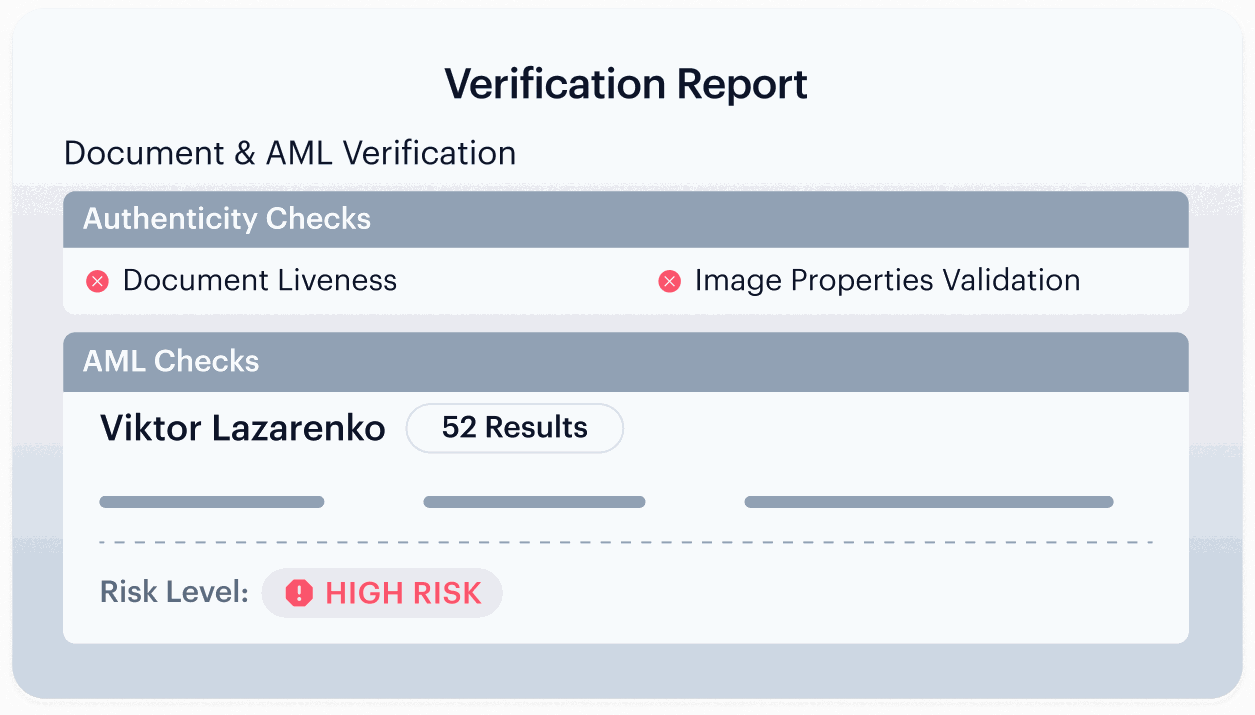
Evidence is Ready for Review
Analysts see reason codes, match signals, document integrity checks, AML context, and case records, reducing the need to rebuild the decision trail manually.
Validated By Leading Analysts And Certification Bodies
Ranked Top 5 in the DHS RIVR 2025 for identity validation
Read Blog
Ranked Exceptional for age verification by Liminal Index 2026
View Report
Recognised as a Leader in G2 Summer 2026 reports
View Reviews
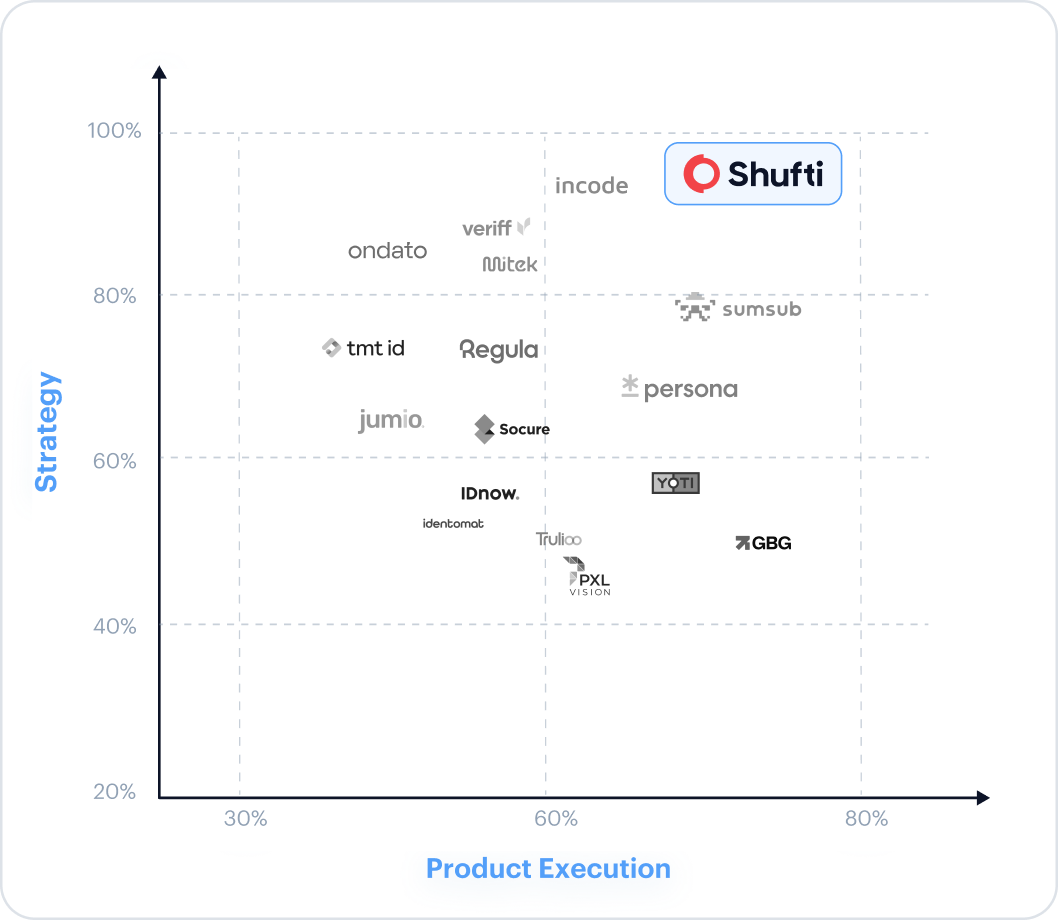
Differentiated by Gartner on document diversity and country coverage
Read more
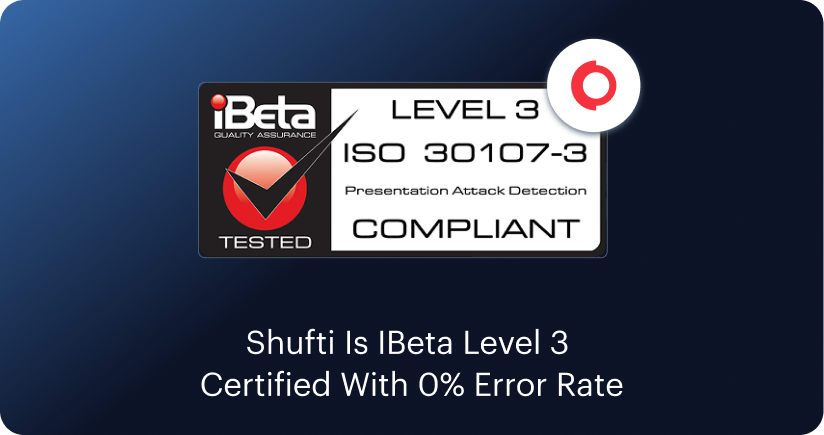
Certified at iBeta Level 3 PAD with 0% APCER
Read Blog
BUILT FOR YOUR INDUSTRY
KYC Built For Regulated Customer Onboarding
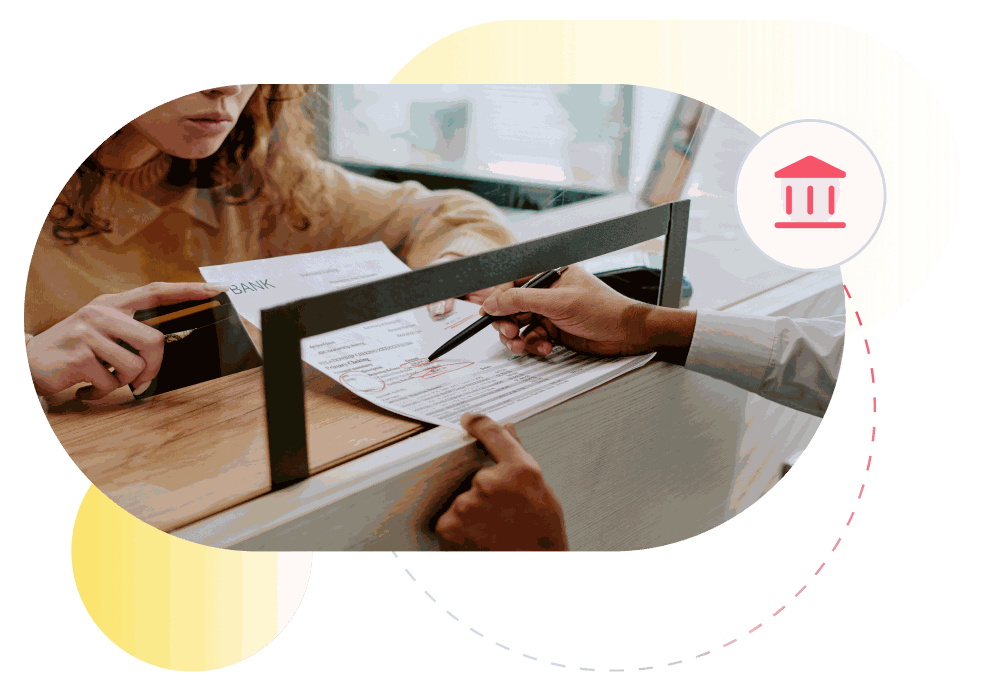
Meet CDD And EDD Requirements From Account Opening
Verify customers, beneficial owners, and high-risk profiles before account activation. Shufti KYC solution for banks helps banks runs document verification, biometric checks, AML screening, and enhanced due diligence in one KYC flow, reducing manual review while keeping audit-ready records for every decision.


Assess Your KYC Stack Against Current Fraud and CDD Requirements
Digital document forgery, synthetic identity fraud, and AML enforcement risk are still material. Review whether your KYC architecture verifies identity, screens AML risk, escalates high-risk customers, and preserves review-ready evidence without manual vendor stitching.
Frequently Asked Questions
What KYC checks does Shufti perform?
A standard Shufti KYC flow can include document verification, face verification with liveness, eIDV, NFC chip verification, address verification, AML screening, and ongoing monitoring. Teams can configure which checks run by geography, product, and customer risk tier.
Does AML screening run inside the KYC flow?
Yes. Shufti positions KYC/AML as a combined workflow, and the AML Screening product supports sanctions, watchlists, PEP/RCA intelligence, adverse media, case context, and audit-ready alerting.
Which regulations does the KYC flow help support?
The flow is designed to support CDD, risk profiling, AML screening, and ongoing monitoring workflows relevant to frameworks such as FinCEN CDD in the US, EU AMLD6/AML package requirements, and MAS Notice 626 for Singapore banks. Final regulatory mapping should be reviewed by legal/compliance for each client jurisdiction.
How does Shufti detect AI-generated documents and deepfakes?
Document verification checks originality, tampering, replay/recapture, GenAI/synthetic patterns, and quality signals. Face verification adds iBeta-certified liveness, 3D depth/shape analysis, and deepfake, replay, and injection defense.
How fast is KYC verification?
Shufti Document Verification lists <15s decision time; Shufti Face Verification is built to confirm a real user in seconds; Shufti eIDV lists <3s response time. Avoid broad page-level timing claims unless confirmed by product.
What happens when a verification is high risk or fails?
Cases can be rejected, routed to manual review, or escalated to EDD depending on the configured risk policy. Shufti returns review-ready reasons and supporting signals so analysts can understand why the case was flagged.
How does Shufti reduce manual review?
The platform surfaces structured reasons, identity-aware AML context, and supporting signals. Shufti AML Screening publicly references fewer manual reviews and fewer false positives as impact metrics.
How do developers integrate the KYC flow?
Developers can integrate via API, SDKs, Journey Builder, and Back Office workflows.