

DATABASE CHECKS
Database Checks Against Authoritative Sources. No Document Upload.
Shufti's Database Checks connect your onboarding flow to 237 government registries, credit bureaus, telco records, and national digital IDs. Users complete verification silently in the background, from the moment they enter their details.
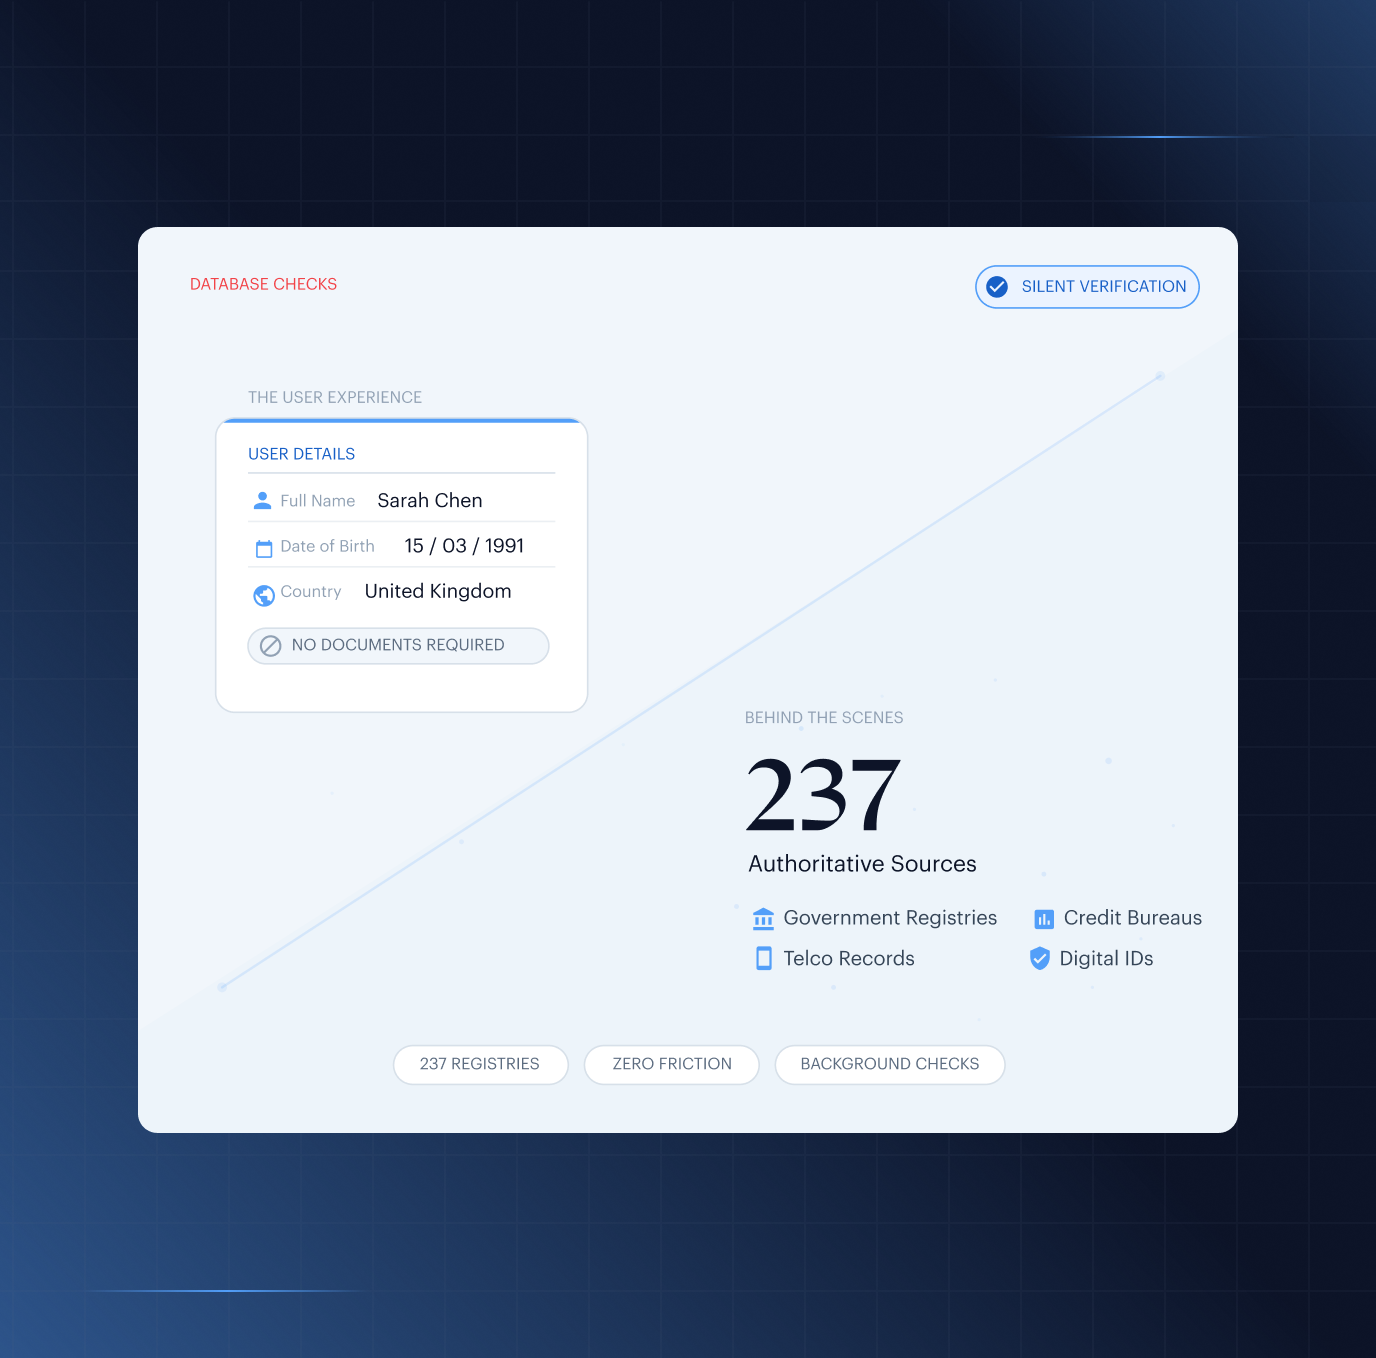
Database Checks Built for Confident Identity Decisions


Why Shufti Database Checks
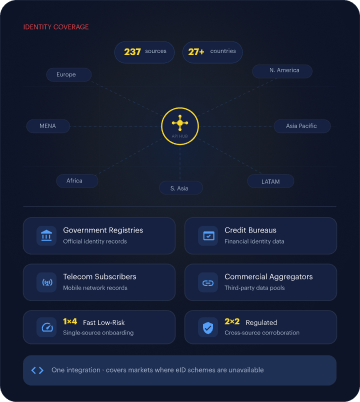
Expand Identity Coverage Through a Single Integration
Access 237 active data sources across 27+ countries, including government registries, credit bureaus, telecom subscriber records, and commercial aggregators through one API.
Cover markets where government eID schemes are unavailable without adding vendors, managing multiple contracts, or maintaining separate integrations.
Choose 1x1 verification for fast, low-risk onboarding or 2x2 verification to corroborate identity across independent data sources for regulated use cases.
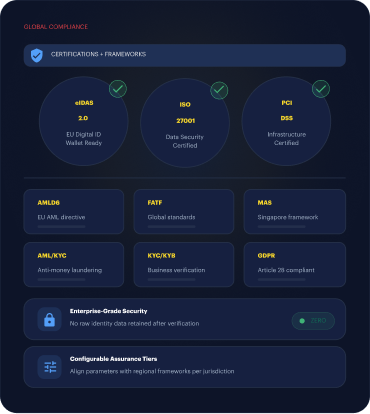
The Right Level of Identity Assurance for Every Journey
Verify identity in the background against authoritative data sources with no user interaction beyond entering basic details.
Authenticate users directly with government-issued digital identity schemes where available, confirming credentials with the issuing authority in real time.
Access passive checks, active eID, and biometric verification through a single API, contract, and tamper-evident audit trail.
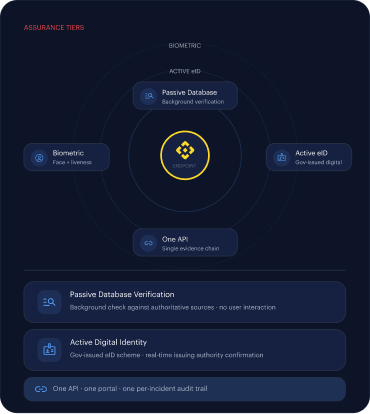
Built for Global Compliance from Day One
Support high-assurance digital identity verification with compatibility for eIDAS 2.0 and future-ready integration with the European Digital Identity Wallet.
Align verification requirements with regional frameworks including AMLD6, FCA, MAS, AUSTRAC, and FinCEN through configurable assurance tiers.
Protect identity data with ISO 27001:2022 and PCI DSS-certified infrastructure, GDPR Article 28 compliance, and no raw identity data retained after verification.
Keep More Users Moving Through Verification
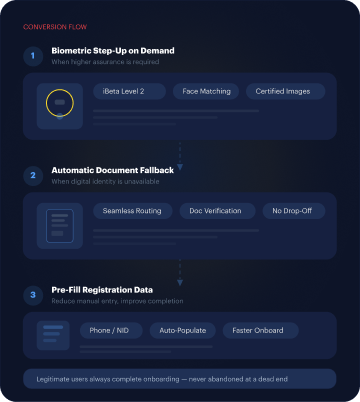
Add iBeta Level 3 certified liveness and face matching when higher assurance is required, using verified images from authoritative identity sources.
Route users seamlessly to document verification when digital identity data is unavailable, ensuring legitimate users can complete onboarding.
Auto-populate forms using a phone number or national ID to reduce manual entry, shorten onboarding time, and improve completion rates.
Verification Modes
Three Layers. One API. Every Assurance Level.
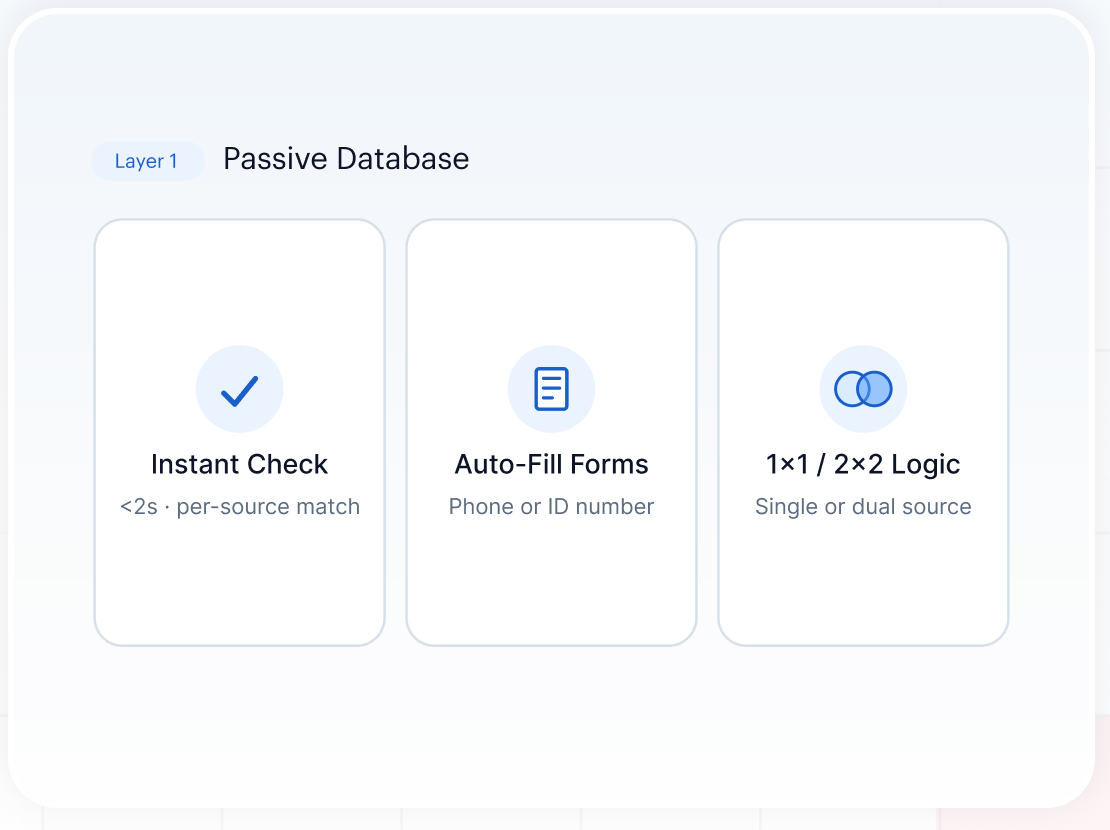
Passive Database
- Passive Database Verification: Instant background check. Verify with no user interaction in under 2 seconds. Results include per-source attribution and attribute-level match scores.
- Pre-fill Services: Auto-populate registration forms using a phone number or national ID number to reduce typing friction at point of entry.
- 1x1 & 2x2 Logic: Single-source for low-risk flows; dual-source cross-referencing for regulated financial services onboarding.
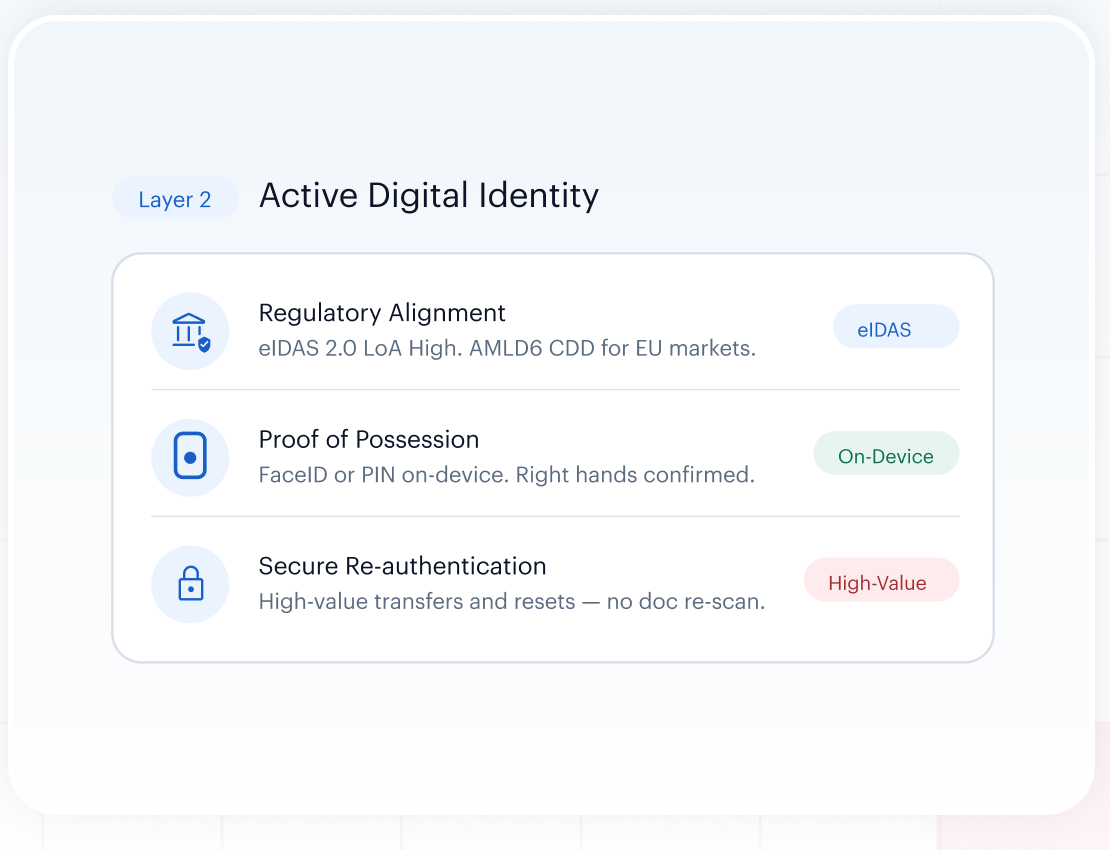
Active Digital Identity
- Regulatory Alignment: Meets eIDAS 2.0 Level of Assurance High. Designed for AMLD6 substantial and high-assurance CDD requirements in EU markets.
- Proof of Possession: User authenticates on their own device via FaceID or PIN. Confirms the credential is in the right hands.
- Secure Re-Authentication: Authorise high-value transfers, password resets, or sensitive data changes without asking for a document scan again.
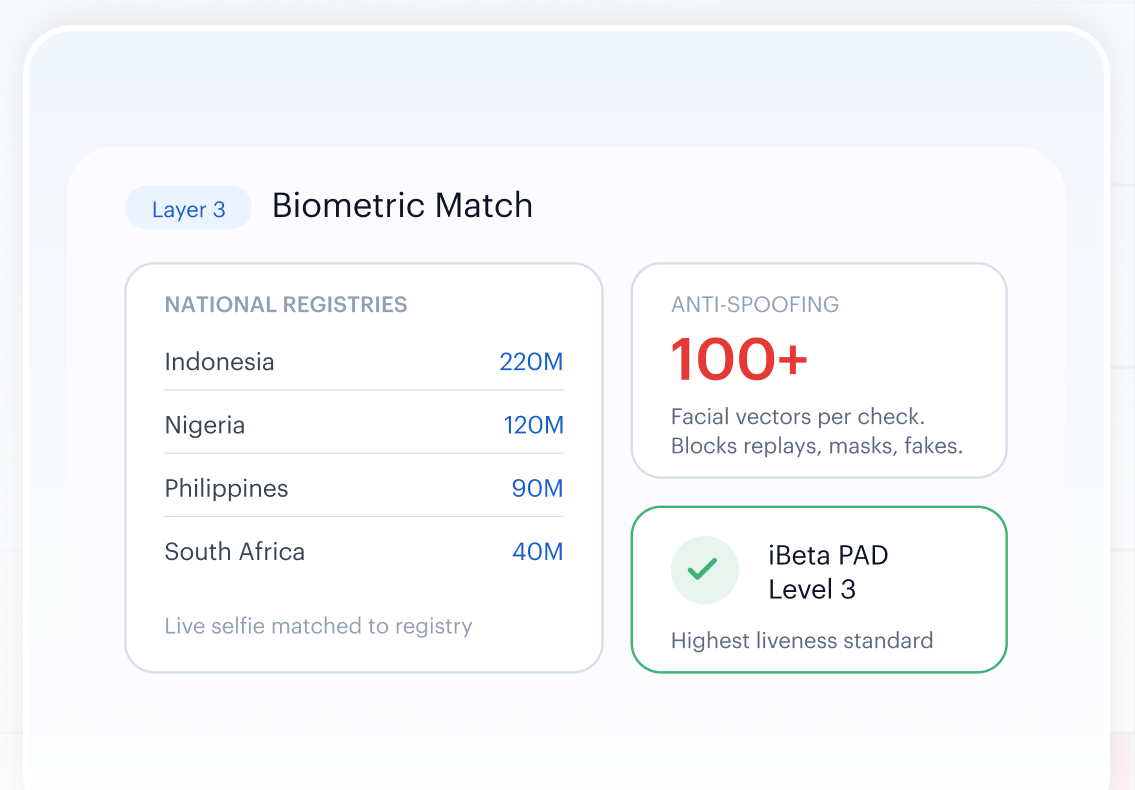
Biometric Match
- National Biometric Registries: Shufti verifies identity by matching live selfies against trusted government facial records, with coverage spanning 470M+ verified identities across Indonesia, Nigeria, the Philippines, and South Africa.
- Anti-Spoofing Defenses: Stop presentation attacks before they succeed. AI-powered liveness detects screen replays, printed photos, 3D masks, deepfakes, and other sophisticated impersonation attempts in real time.
- iBeta PAD Level 3: Protect high-risk workflows with independently tested biometric assurance. Shufti's Presentation Attack Detection (PAD) is iBeta Level 3 certified, delivering enterprise-grade protection against advanced spoofing attacks.
Worldwide Identity Coverage Through a Single Network
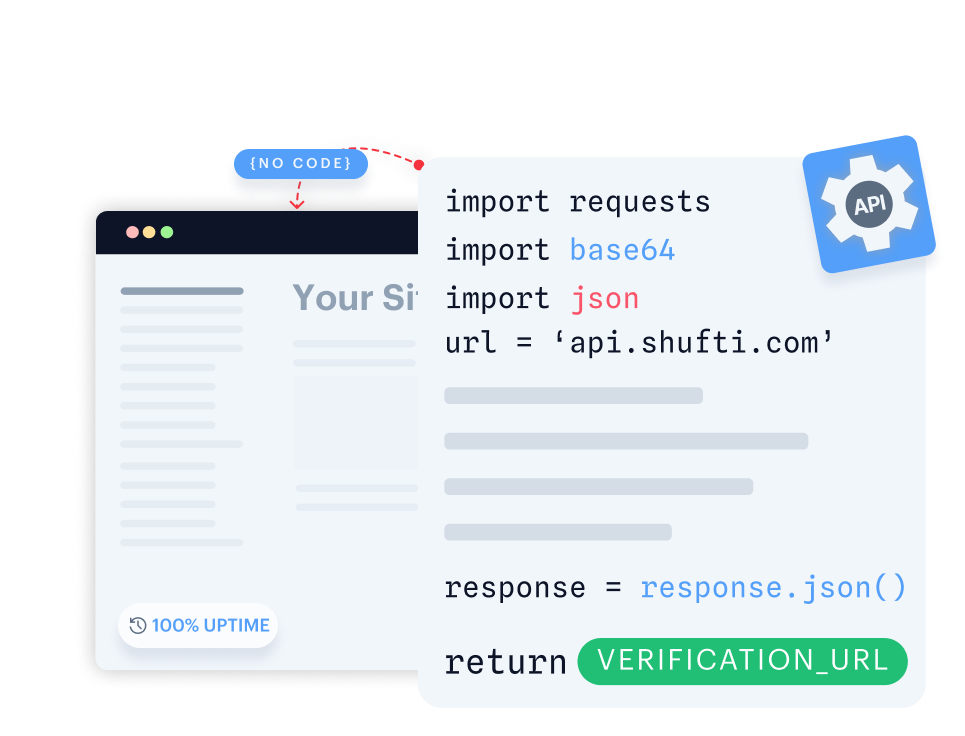
Single API, Seamless Integration
Build fully customisable verification flows with seamless backend integration.
- Gain full control by customising verification flows end-to-end.
- Integrate seamlessly with your backend for quick implementation.
- Design flexible verification journeys tailored to your users.
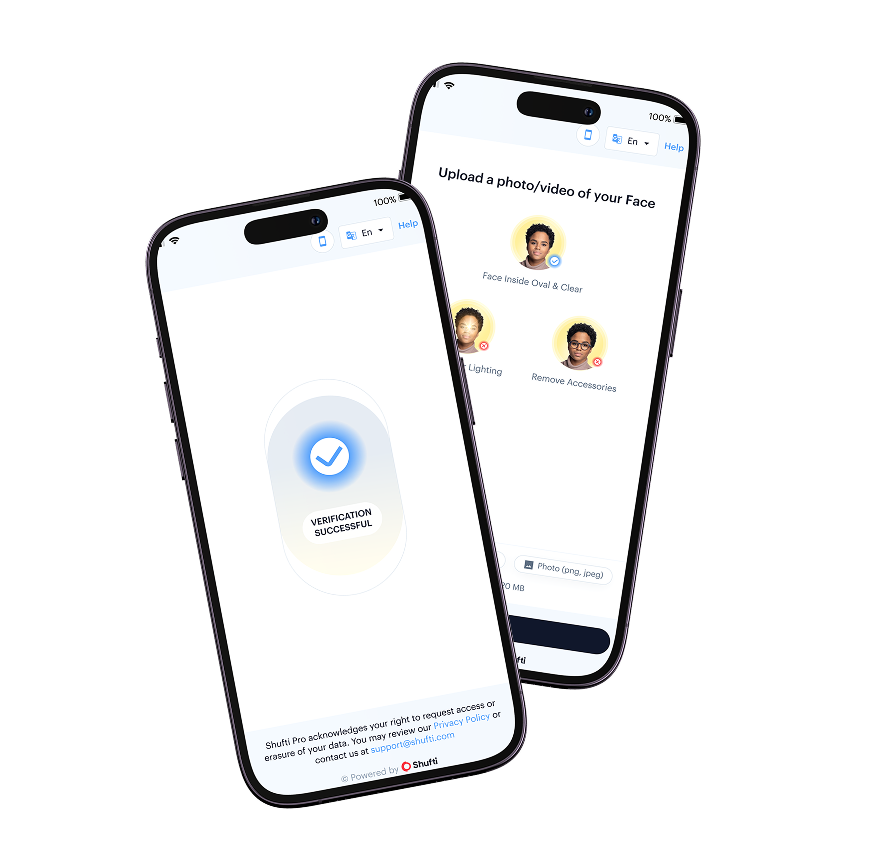
Launch a native verification experience in your mobile app within minutes.
- Launch native verification within minutes on iOS or Android.
- Use ready-made UI with camera, capture, and real-time feedback.
- Customise flows to fit seamlessly into your mobile app.
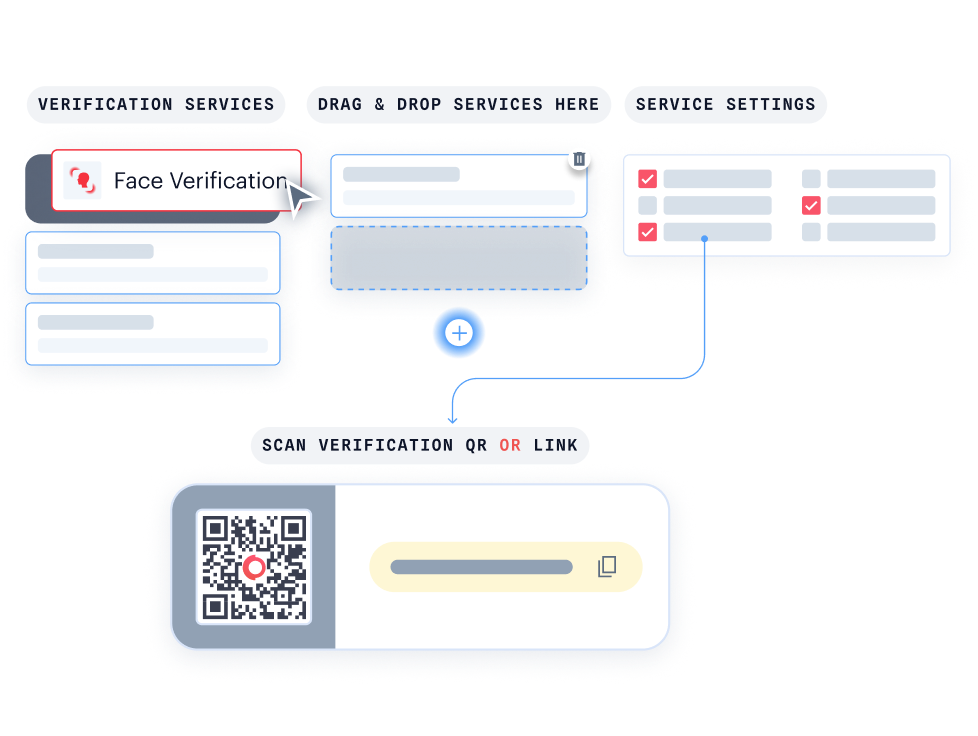
With KYC Journey Builder, create personalised verification journeys without writing a single line of code.
- Customise your journey effortlessly with drag-and-drop functionality.
- Instantly see how your verification flow looks for your users.
- Easily connect with Hosted Verification for a consistent, branded experience.
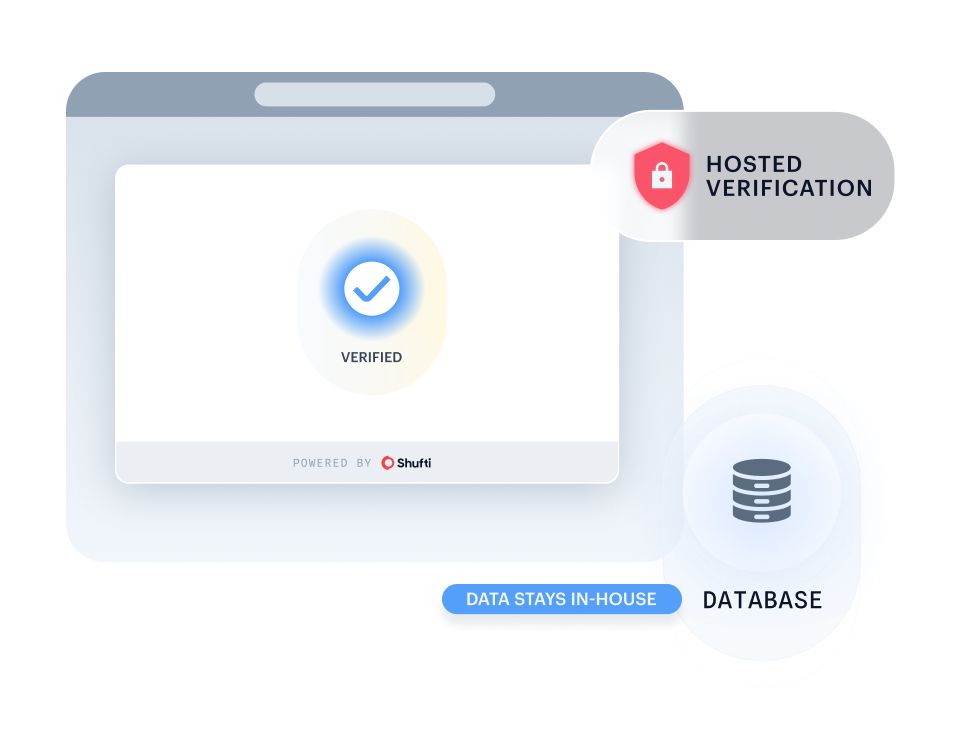
Run Shufti within your own identical-capability infrastructure for maximum data control and privacy.
- Keep all sensitive information in-house to meet strict governance and data residency requirements.
- Keep sensitive information fully private and secure in-house.
- Deploy in highly regulated sectors without compromising compliance.
BUILT FOR YOUR INDUSTRY
Investor Qualification for Every Regulated Industry
Verification That Matches Trading Speed
Document capture at sign-up is the leading cause of marketplace onboarding abandonment. Shufti verifies both parties in the background, with address confirmation against 180+ sources and biometric step-up for high-value

COMMON QUESTIONS
Frequently Asked Questions
What are Database Checks and how do they differ from document verification?
Database Checks verify identity by cross-referencing submitted attributes against authoritative third-party databases including government registries, credit bureaus, and telco records. No document photograph is required. Document verification asks users to photograph a physical ID, then applies OCR and authenticity checks. Database Checks are faster, have higher completion rates, and eliminate the attack surface created by document image upload.
Which countries and sources does passive database verification cover?
Shufti’s passive database check network covers 237 active sources across 27+ countries. Source types include government population registries, national credit bureaus, telco subscriber records, commercial aggregators, utility databases, and consumer data sources. Key markets include Australia (95%), Costa Rica (99%), India (95%), Chile (98%), Spain (95%), Germany (75%), and 20+ additional countries across Europe, LATAM, APAC, and Africa.
What is the difference between passive and active database verification?
Passive verification checks submitted identity attributes against structured databases in the background with no user action required beyond entering their details. Active verification accepts a digital credential issued by a government authority and validates it against the issuing source in real time. Where the authority supports biometric matching, active verification confirms the correct person is presenting the credential.
Are Database Checks accepted for KYC compliance?
Database-level identity verification is accepted under KYC frameworks in multiple jurisdictions including the UK (FCA), EU (AMLD), Australia (AML/CTF Act), Singapore (MAS), and UAE (CBUAE). Active eIDV at eIDAS Level of Assurance High meets EU Substantial and High assurance CDD requirements. Acceptance varies by jurisdiction and use case.
What happens if a user is not covered by passive database sources?
The verification flow automatically routes to the next available layer: active eIDV if the country has a supported digital identity scheme, or standard document verification as a fallback. No user is lost to missing coverage. Fallback routing rules are configurable via the Journey Builder without API changes.
What is 1x1 and 2x2 verification logic?
1x1 logic verifies identity against a single data source, suitable for low-risk flows where speed is the priority. 2x2 logic cross-references two independent data sources and requires both to confirm the same attribute, suitable for regulated financial services onboarding where corroborated evidence is required.
How quickly does a database check return a result?
Passive database checks against structured government and credit bureau APIs typically complete in under two seconds. Active eIDV response time depends on the issuing authority’s infrastructure. Shufti’s end-to-end verification time is under 15 seconds across all supported markets.
How long does API integration take?
Standard REST API integration takes 2–5 days. SDK integration (iOS, Android, Web) takes 1–3 days. Sandbox access is available within 24 hours without a commercial agreement. All three verification layers route through the same API endpoint, so adding coverage after initial integration requires no additional development work.
Evaluate Whether Your Stack Covers the Full Spectrum
Compare passive, active, and biometric coverage across target markets in a single evaluation call.
Your Go-To for KYC/AML & Fraud
Resources

11 September, 2026
Enterprise Guide to Docless Identity Verification in Latin America
A practitioner's guide to docless onboarding across Brazil, Mexico, Argentina, Chile, Colombia and Peru, covering the registry and the remote onboarding rule in each.
Guide