AMLR Solutions
 AMLR Consultation
 EUDI Wallet
 Onboarding
 Ongoing Monitoring
 FRAML
 KYC
 KYB
 KYI
 Age Assurance
 Workforce IAM
 Candidate Verification
 Account Takeover
 Bonus/ Promotion Abuse
 Chargeback Fraud
 Deepfake
 Document Fraud
 Fraud Networks
 Impersonation Fraud
 Money Mule Activity
 Multi-Accounting
 Party Fraud
 Regulatory & Compliance Risks
 Synthetic Identity Fraud
 Adult Content
 Banking
 Crypto
 Fintech
 Forex
 Compliance
 Fraud prevention
 Trust & safety
 Global expansion
 Compliance Officers
 Developers
 Fraud Analysts
 Product Managers
 Journey Builder
 Global Trust Platform
 Customer Profiles
 Vendor Comparison
 IDV Case Management
 AML Case Management
 Regulatory Reporting
 Agentic Rule Builder
 AI Compliance Co-Pilot
 Fraud Analytics
 Fraud Hub
 OCR
 Shufti AI
 Bank Account Verification
 Biometric Duplication
 Database Checks
 Document Intelligence
 Government ID
 Mobile Driver's License
 NFC
 Selfie Liveness
 Brand Personalisation
 Deployment Options
 Identity Methods
 IDV Modes
 Multi-tenancy
 On-Premise IDV
 Secure Capture
 Shufti MCP



Know Your Agent (KYA) is the process of verifying an AI agent’s identity, the person or business accountable for it, and the actions it is authorized to take before it can act on your platform.
A customer can now use an AI shopping assistant to purchase products. The merchant now needs to know whether the purchase is made by software on behalf of a real customer or whether it even has the permission to complete that purchase.
KYA answers three questions about that software: whether the agent is authorized, which verified person or business is behind it, and whether the action the agent is performing falls within the permissions it was given. It does not replace KYC or KYB since the principal behind it is accountable and still has to be verified the same way any customer would be.
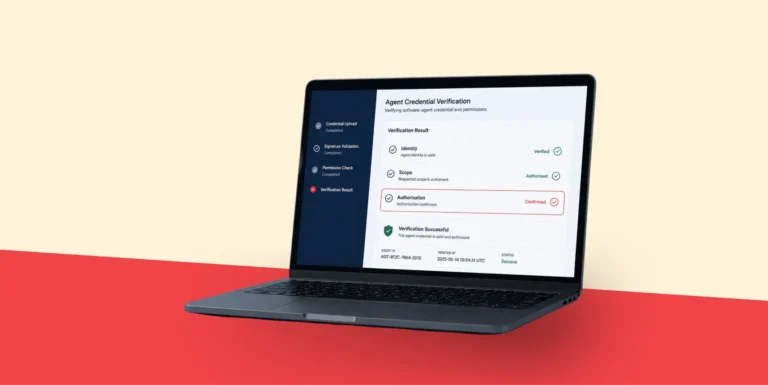
KYA verification process:
KYC tells about who the customer is, not about the agent. It doesn’t tell whether the agent acting in their name belongs to them or what it may do.
KYA actually closes that gap:
- Agent Identity: a unique credential that is bound to the agent
- Principal (Owner): a verified person or business legally accountable for the agent
- Delegated Authority: checks the permissions that are given to the agent
- Audit Trail: a log that links every action back to the agent and its principal
A common failure that exists is treating the agent as the customer. An agent that has a valid token but with no verified principal is considered an anonymous account.
Difference between Non-human identity, machine identity, and agentic identity:
Each term has a different meaning and covers a different layer of risk.
| Term | What it covers | Example |
| Non-human identity (NHI) | Any credential used by software rather than a person | API keys, service accounts, access tokens |
| Machine Identity | Credentials that authenticate devices and workloads, handled through machine identity management | TLS certificates, workload identities |
| Agentic Identity (AI agent identity) | The identity of an autonomous agent acting on a principal’s behalf | A shopping agent paying with a user’s card |
Machine identity confirms the software is genuine. Only agentic identity confirms who is accountable for it.
AI agent fraud and KYC:
AI agent fraud happens because traditional KYC was built for verifying people (customers), not autonomous software agents. Agents act at machine speed with whatever credentials they hold, so fraud often looks legitimate.
Common examples of AI Agent Fraud:
Stolen Agent Credentials: Someone steals an AI agent’s access key or login. They would act like moving money or accessing accounts. This activity may look normal, but it comes from a valid credential.
AI Agent opening fake accounts: Fraudsters use the automated accounts to create different accounts using fake or stolen identities. The volume and speed make the detection harder.
Prompt Injection Attacks: Fraudsters usually manipulate an AI agent with hidden instructions. The agent would be trained to perform actions it was not supposed to do. For instance, an AI assistant approved a refund though rules did not allow refunds above a certain amount.
Fake agents pretending to be trusted agents: A malicious agent imitates a legitimate one. It attempts to convince systems to approve payments or access sensitive information.
Related rules and standards:
KYA is a practical control framework, not a requirement named in the rules. The existing rules may affect the AI disclosure, payment authentication, automated decisions or risk assessment, depending on the services, jurisdiction, and the company’s role.
| Provision | What it requires | |
| EU AI Act, Article 50(1) | Providers of AI systems intended to interact directly with people must generally ensure those people are informed that they are interacting with AI, unless this is obvious in context. This is a disclosure rule, not an agent identity requirement. | |
| PSD2 Article 97 | Payment service providers must apply strong customer authentication in the circumstances set out in Article 97, subject to applicable exemptions. Whether and how this applies to a purchase made through an agent depends on the payment flow. | |
| GDPR Article 22 | This provision concerns decisions based solely on automated processing that have legal or similarly significant effects on a person. It sets out exceptions and safeguards; it does not apply to every decision involving an AI agent. | |
| FATF Recommendation 15 | Countries and financial institutions should assess money laundering and terrorist financing risks from new technologies. For financial institutions, the assessment should take place before launch. FATF recommendations are international standards implemented through national measures. | |
A practical KYA check runs in five steps:
- Register the agent and issue it a unique, revocable credential
- Verify the principal through KYC or KYB checks that are applicable to the service and risk.
- Link the agent to the principal and record a mandate specifying permitted actions, limits, expiry, and who may revoke it.
- Before each requested action, check the agent’s credentials and the current mandate, including its limits and revocation status. Seek fresh customer approval when the action falls outside the mandate or meets a defined risk threshold.
- Record the decision and monitor subsequent activity for misuse.
KYA check at checkout allows or blocks the payment:
When the shopping agent is trying to pay, the merchant first checks the agent’s credentials, then links them to the verified customer who authorized it. It then compares the purchase against that customer’s mandate. These are approved by the merchant: the spending limit and when the permission given to the AI agent will expire.
When Allowed: The agent buys an item that is approved by the merchant within the customer’s $100 limit, before the mandate expires. The payment goes ahead, and the decision is logged.
When Declined: On the other hand, if the agent tries to spend $250, or pay a merchant the customer never approved. The payment is either blocked or sent to the customer for approval.
The customer can revoke the agent’s access at any time, and every decision is recorded against the agent and the customer.
Frequently Asked Questions
What is Know Your Agent (KYA)?
Know Your Agent (KYA) is the process of identifying, verifying, and managing AI agents before they can access systems, data or carry out actions.
What is non-human identity (NHI)?
A non-human identity (NHI) is a digital identity assigned to machines, applications, bots, service accounts or AI agents so their access and activity can be managed.
What is AI agent authentication?
AI agent authentication is the process of confirming that an AI agent is legitimate before giving it access to systems, data or specific permissions.
How do you verify the identity of an AI agent?
An AI agent can be verified by checking its digital credentials, authentication keys or certificates, ownership, permissions, and authorised purpose.
How is KYA different from KYC?
KYC verifies an individual customer; KYB verifies a business. KYA addresses the agent acting for that person or business, its assigned permissions, and the actions it attempts.