Stablecoin AML Compliance Guide For Your Business
Stablecoins settle in seconds, but the rules behind them change with every market a payment crosses and every sector that handles it, so this guide maps the AML duties your business carries in each.
Schedule a DemoStablecoins Are Bridging Traditional and Decentralised Finance
For years traditional finance and decentralised finance ran on separate tracks because moving funds from a bank account onto a blockchain took several steps. Stablecoins are closing that gap since a fiat-backed stablecoin follows the value of a currency such as the US dollar while it moves on a blockchain at any hour. Its holder can still swap it back into ordinary money whenever they need to.
Instant settlement has turned that design into a practical medium for remittances and cross-border payments, which is why stablecoins are fast becoming a household name well beyond crypto trading.
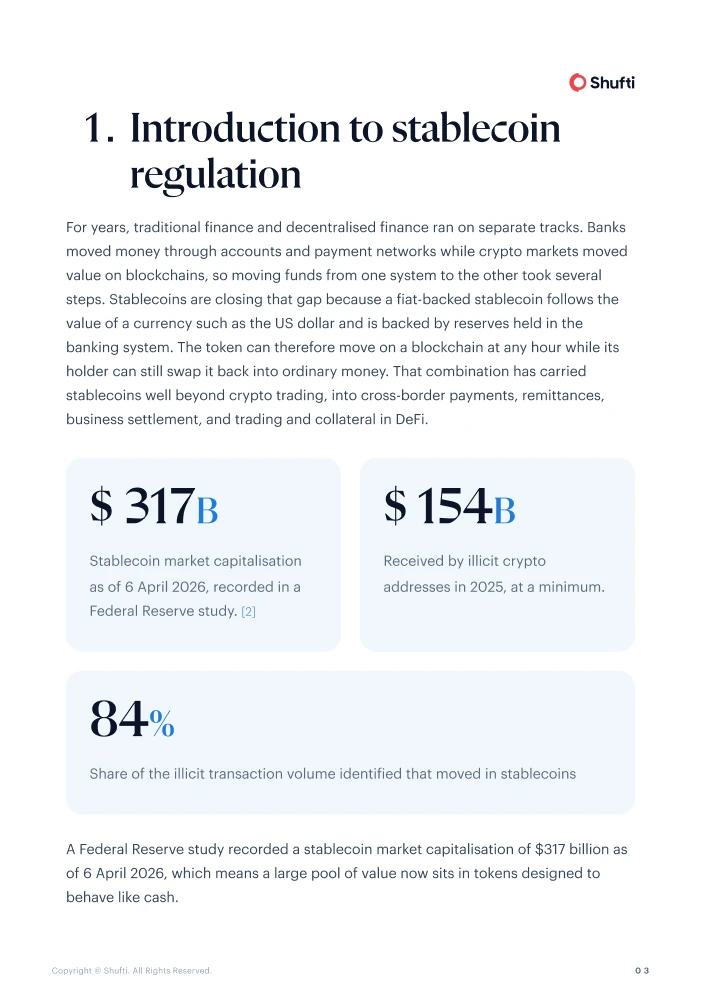
- $ 317B
A Federal Reserve study recorded a stablecoin market capitalisation of $317 billion as of 6 April 2026.
Federal Reserve FEDS Notes, 2026
- 69
The Financial Action Task Force (FATF) July 2026 update tracks 69 jurisdictions that together account for about 97% of the global market.
FATF targeted update, July 2026
- 71%
Stablecoin issuers must be licensed or registered in 71% of those jurisdictions when they qualify as VASPs.
FATF targeted update, July 2026
One of the major challenges businesses face with stablecoin regulatory compliance is that regulations differ across markets and compliance challenges can also vary from one sector to another. FATF standards call on countries to bring businesses that exchange, hold or transfer stablecoins under AML rules that include the Travel Rule. Each jurisdiction then layers its own stablecoin rules on top of those AML/CFT compliance duties.
The treatment of foreign-pegged stablecoins shows how far those rules can differ from one market to the next. In the UAE licensed dirham payment tokens can be used for lawful payments whereas foreign payment tokens from registered issuers may be used as payment for virtual assets and their derivatives. Hong Kong requires a licence to issue a Hong Kong dollar-referenced stablecoin even from outside Hong Kong. Brazil treats many stablecoin transactions as foreign exchange, which means the same token can face very different rules in each corridor a business serves.
The Four Main Types of Stablecoins
What sits behind a token shapes its risks and often decides how the law classifies it. Regulators therefore begin every stablecoin regulatory compliance assessment by establishing which type of token they are looking at.
01Fiat-Backed Stablecoins
A fiat-backed stablecoin holds reserves of cash, bank deposits and approved short-term investments. This structure makes it the type most often used to move money between people and businesses.
02Crypto-Collateralised Stablecoins
A crypto-collateralised stablecoin is backed by other digital assets that are often worth more than the tokens issued. Automatic liquidations protect that cushion when the value of the collateral falls.
03Commodity or Asset-Backed Stablecoins
A commodity- or asset-backed stablecoin tracks gold or a basket of assets. What the holder can actually claim depends on the terms of each arrangement.
04Algorithmic and Hybrid Stablecoins
An algorithmic or hybrid stablecoin uses code to expand or shrink its supply. The stablecoin label alone says little about whether such a token qualifies under payment stablecoin rules.
Central bank digital currencies and tokenised bank deposits are different products that regulators assess separately.
How Stablecoins Are Regulated Across Eight Major Markets
Only a relatively small number of jurisdictions have written stablecoin-specific rules so far while AML/CFT coverage has moved much faster. A business that serves customers in several countries therefore usually answers to several regimes at once.
| Market | Stablecoin rules | AML/CFT highlight | Status |
|---|---|---|---|
| European Union | MiCA stablecoin rules have applied since 30 June 2024 and MiCA has been fully in force since the transition ended on 1 July 2026. | The Travel Rule applies to every crypto transfer between providers with no minimum amount. | In force |
| Hong Kong | The Stablecoins Ordinance took effect on 1 August 2025 and the HKMA granted the first issuer licences on 10 April 2026. | Issuers screen unhosted wallet addresses and apply the Travel Rule to stablecoin transfers. | In force |
| UAE | The CBUAE has regulated payment token services since 31 August 2024 and VARA rules apply in Dubai. | Providers screen transaction parties against sanctions lists and report to the UAE Financial Intelligence Unit. | In force |
| Brazil | BCB Resolutions 519, 520 and 521 have applied since 2 February 2026 and bring many stablecoin transactions under foreign exchange rules. | The Travel Rule phases in with domestic procedures due by 2 February 2027 and the international phase due by 2 February 2028. | In force |
| United States | The GENIUS Act became law on 18 July 2025 and takes effect on 18 January 2027. | The Act will treat permitted issuers as financial institutions under the Bank Secrecy Act. | Not yet in force |
| Canada | The Stablecoin Act received Royal Assent on 26 March 2026 and its proposed regulations were published on 24 October 2026. | FINTRAC duties already apply to businesses that exchange or transfer stablecoins. | Not yet in force |
| United Kingdom | The new regime applies from 25 October 2027 and the FCA published its final rules on 30 June 2026. | Many stablecoin businesses already need FCA registration under the Money Laundering Regulations. | Not yet in force |
| Singapore | MAS finalised its stablecoin framework in 2023 and its consultation on the implementing legislation closed on 16 October 2026. | MAS expects regulated issuers to follow existing AML/CFT standards that cover due diligence, screening and the Travel Rule. | Draft legislation |
 European Union
 Hong Kong
 UAE
 Brazil
 United States
 Canada
 United Kingdom
 Singapore
The table reflects each market’s status as of November 2026 while several markets are still writing their detailed rules. Businesses should therefore confirm current obligations with qualified advisers in each market they serve.
Some of the Stablecoin Payments AML Risks According to the Financial Action Task Force
The FATF published its Targeted Report on Stablecoins and Unhosted Wallets: Peer-to-Peer Transactions on 3 March 2026 and listed four warning signs for stablecoin payments in it. A monitoring team can turn each of these warning signs into specific alerts that it configures and tests against its own customer activity.
| FATF warning sign | Example alert signal |
|---|---|
| Fast cross-border movements that do not fit a customer’s profile | Funds received and sent on to another country within hours or days of arriving |
| Cash-to-stablecoin switches with no clear explanation | Fiat to stablecoin to fiat round trips that recur with no payment or treasury purpose |
| Transfers between seemingly unrelated senders and recipients | Many senders with no visible link paying the same recipient or wallet |
| Refunds sent to wallets unconnected to the original payer | A refund address that differs from the wallet that funded the original payment |
These alert signals are illustrative, so each team should calibrate and test them against actual customer activity.
Stablecoin Compliance Requirements by Sector
Stablecoin compliance requirements vary by sector because they depend on what a business actually does with the tokens it handles. Issuers, custodians, exchanges, payments platforms and remittance providers each carry AML/CFT duties alongside stablecoin rules in the jurisdictions where those duties apply.
Stablecoin issuers need to check customers before issuing or redeeming tokens because a token may have changed hands many times before someone asks to turn it back into cash. Some regimes also expect issuers to monitor tokens after they leave the issuer and to keep the technical means to block, freeze and reject unlawful transactions.
Banks deal with stablecoins as issuers and reserve holders as well as providers of settlement accounts. Industry guidance therefore expects them to understand each issuer’s business and the fund flows its account should carry, and in higher-risk cases a bank may also review the on-chain history of tokens before they are redeemed into fiat.
Custodians and wallet providers must verify customers and apply the Travel Rule to transfers between providers, which in the EU applies with no minimum amount. EU rules also call for a check that the customer owns or controls a self-hosted wallet whenever a transfer above EUR 1,000 goes to or from it.
Crypto exchanges now treat stablecoin listings as compliance decisions because a growing number of markets restrict which stablecoins exchanges can list and which customers can trade them. Exchanges also share Travel Rule data on transfers and run due diligence on the foreign crypto service providers they deal with where the rules require it.
Crypto card issuers convert a stablecoin balance into regular currency before or during each payment, which is why they screen funding wallets for sanctions exposure. They also monitor top-up, conversion and spend together so that unusual funding and fast conversions can be linked to the cardholder’s profile.
Stablecoin payments and infrastructure platforms provide virtual accounts, on- and off-ramps and settlement to other financial firms. The central question for these platforms is who knows the end users moving money through them, so they run KYB on each client business and own end-user due diligence unless reliance on a regulated client is lawful.
Money service and remittance providers use stablecoins in two ways for stablecoin remittances. In a settlement model the sender pays in fiat and the provider settles with partners in stablecoins before the recipient receives local currency. In a direct transfer model the sender sends stablecoins straight to the recipient’s wallet instead. A payments licence does not automatically cover the cryptoasset side of either model, so providers still register with their AML supervisors and screen every party and wallet address as well as apply the Travel Rule on qualifying transfers.
How to Build an AML Program for Stablecoin Payments
An AML program for stablecoin payments starts with the obligations that repeat across every sector, because the same tokens pass between issuers, wallets, exchanges and payment providers. Four of these obligations create most of the operational work and form the core of the program.
Customer Due Diligence
Remote onboarding makes identity, ownership and control harder to prove, which is why document checks, face matching and liveness detection support remote KYC. A new stablecoin service may also call for an updated risk assessment.
Travel Rule Data Exchange
Counterparties may use different Travel Rule messaging protocols, so data has to move securely between their systems. Every missing field or failed delivery then needs a documented decision on the transfer.
Wallet Ownership and Screening
A wallet address does not show who controls it, so sending and receiving addresses are screened before a transfer is released. Control of self-hosted wallets also has to be evidenced where the rules require it.
Multi-Rail Transaction Monitoring
A single stablecoin payment often moves through a fiat deposit, an on-chain transfer and a bank payout. Crypto transaction monitoring has to link every leg to the same customer in order to reveal unusual routes.
Crypto AML Compliance Solutions for Stablecoin Businesses
Compliance obligations arise at every point in a stablecoin’s life from issuance and transfer to conversion and payout. The right stablecoin compliance solution therefore needs controls at each of those points that keep identities and screening results linked to one customer record.
Identity Verification Before Issuance and Redemption
Issuers need to know who buys tokens directly and who cashes them out, including holders who first appear at redemption with no history on the platform. Document verification, facial matching and liveness establish identity at both points while geolocation checks support access restrictions where a token cannot be offered in a customer’s location.
KYB for Platforms, Distributors and Payout Partners
Stablecoin arrangements depend on businesses in the middle such as client fintechs on infrastructure platforms and the distributors of an issuer’s token as well as conversion and payout partners in each corridor. KYB, UBO verification and business AML screening establish the entities and individuals behind each of them. Due diligence workflows then collect the purpose and expected activity of higher-risk relationships.
Reusable KYC Reduces Friction in Closed-Loop Stablecoin Ecosystems
Many stablecoin businesses operate within a closed-loop ecosystem particularly around on-ramp and off-ramp conversion where the same customer moves between an issuer and a wallet and then on to an exchange or payout partner. Each of these businesses usually carries its own customer due diligence duty, so the same person can be asked for the same identity document and selfie several times before one payment completes.
A reusable KYC approach removes much of that friction because a business can rely on identity evidence already verified within the ecosystem where that evidence is still valid and the applicable rules permit its reuse. The new service still needs its own risk assessment and fresh sanctions and PEP screening where required. A business that simply has a partner run onboarding on its behalf also remains responsible for the checks.
Consent-based identity reuse within a configured business and partner ecosystem makes this possible, while biometric re-verification connects returning customers to their verified records. Risk-based step-up checks then request more evidence wherever a new product needs it.
Crypto Wallet Screening and Unhosted Wallet Ownership Checks
Stablecoins sent to a self-hosted wallet leave the regulated perimeter, which is why wallet screening checks addresses against sanctions lists and watchlists before a transaction is processed. Lists of sanctioned wallets change over time, so screening needs regular list updates and each match should link back to the customer verified at onboarding. Cryptographic signatures and specified micro-transactions also provide evidence of customer control over self-hosted wallets.
Crypto Travel Rule Data Exchange for Every Qualifying Transfer
Stablecoin transfers between providers carry the same Travel Rule duties as other virtual assets. Platforms that act for their clients’ end users also need to establish whose details travel with each transfer. Connectivity to direct VASP messaging and to protocols such as TRP, CODE and Global Travel Rule (GTR) supports that exchange through one integration using IVMS101, while status tracking with hold or escalation workflows handles incomplete exchanges.
Crypto Transaction Monitoring Across Fiat, On-Chain and Payout Legs
In settlement and remittance models one payment can pass through a fiat deposit and a stablecoin transfer before it reaches a local-currency payout, so those legs need to be assessed as one customer journey. Transaction monitoring then assesses the linked records against customer profiles, beneficiary history and corridor risk through configurable scenarios such as rapid conversion followed by withdrawal. AI-assisted rule builders also let teams draft new scenarios and test them on historical data.
Continuous AML Screening for Holders and Partners
A customer or payout partner who was clear at onboarding can become a sanctions, PEP or adverse media match later, which is why screening has to continue for the life of the relationship. Continuous AML screening identifies new matches involving enrolled customers and businesses and links the results to verified customer records so analysts can decide whether further investigation or enhanced due diligence is warranted.
Alert Investigation with Full Payment Context
An alert is harder to resolve when identity records, screening results and payment history sit in separate systems because analysts then spend their time gathering evidence instead of assessing it. Case management brings those records into one case where an AI assistant can explain screening-hit classifications while analysts and the MLRO keep the final decision. The same case then feeds SAR and STR preparation, with direct submission where a jurisdiction-specific connection exists.
Compliance Workflows That Adapt as Stablecoin Services Expand
New stablecoin services bring new flows, so a workflow builder lets teams configure separate verification steps and evidence requests as well as manual review for issuance, redemption, wallet and payout flows. APIs and SDKs connect these workflows to existing systems while deployment and data residency options support information-governance requirements.
Shufti Supports Stablecoin Businesses from Onboarding to Payout
Shufti brings these controls together for every type of stablecoin business from issuers and banks to exchanges, payments platforms and remittance providers. A business can therefore add stablecoin products and corridors on the same compliance foundation.
Onboard with Full Customer Due Diligence
Shufti verifies individuals and businesses and identifies beneficial owners before the first issuance, trade or transfer. It also assesses AML risk through sanctions, PEP and adverse media screening.
Monitor Customer Risk After Onboarding
Shufti’s ongoing AML screening and transaction monitoring show when a verified customer becomes a risk, with fraud and account takeover signals linked to each customer profile.
Assure Transfers and Payouts Before Funds Move
A crypto-collateralised stablecoin is backed by other digital assets that are often worth more than the tokens issued. Automatic liquidations protect that cushion when the value of the collateral falls.
Stablecoin AML Compliance Checklist for Choosing a Solution
Stablecoin issuers, banks, custodians and wallet providers, crypto exchanges, card issuers, payments platforms and remittance providers can use this stablecoin AML compliance checklist to assess whether a solution covers what their business needs before they launch a service or expand into another corridor. Tick each statement that a solution already meets because any empty box points to a gap that the solution leaves open.
Grow your business with confidence using the right Stablecoin AML Compliance Solution.
Request a demo
Certifications
Independently audited and certified for enterprise-grade security and data protection.
Frequently asked questions
The GENIUS Act is the US federal law for payment stablecoins, and it became law on 18 July 2025. Once it takes effect only a permitted issuer may issue a payment stablecoin in the United States, and issuers must back every token at least one-to-one with eligible reserve assets and publish the make-up of those reserves every month. The Act also treats permitted issuers as financial institutions under the Bank Secrecy Act, which means they need a compliance programme that covers customer identification, due diligence, suspicious activity reporting and sanctions.
The GENIUS Act takes effect on 18 January 2027, 18 months after it became law, because the final rules came too late to bring that date forward and regulators are still finishing some of them. From 18 July 2028 exchanges and custodians generally may only offer payment stablecoins to US customers if the tokens come from permitted US issuers or from foreign issuers that meet the Act’s requirements.
MiCA is the EU’s Markets in Crypto-Assets Regulation, and it applies directly in every member state. Its stablecoin rules have applied since 30 June 2024 and separate e-money tokens tied to a single official currency from asset-referenced tokens that reference other values or baskets. Only banks and licensed electronic money institutions may issue e-money tokens, and those issuers must redeem them at face value whenever a holder asks without paying interest on them.
Stablecoin payments move value in tokens that track a currency such as the US dollar, which lets funds settle on a blockchain at any hour. In a settlement model the sender pays in fiat and the provider settles with partners in stablecoins before the recipient receives local currency, so neither customer holds tokens. In a direct transfer model the sender sends stablecoins straight to the recipient’s wallet, where they can be held or converted into local currency.
Banks can take on stablecoins as issuers, reserve custodians, settlement account providers or recipients of redemption funds, and each of these roles carries permissions that differ from one market to the next. A bank that provides crypto custody or transfers must meet the same AML/CFT and Travel Rule duties as other crypto service providers. In certain jurisdictions banks also need specific central bank approval before converting stablecoins and may not deal with crypto firms that are not authorised.
Industry guidance expects a bank or partner to understand an issuer’s business and controls along with the purpose of each account and the fund flows it should carry. In higher-risk cases the review extends to the on-chain history of tokens before they are redeemed into fiat and to the source of large fiat deposits made to obtain newly issued tokens. Reserve arrangements matter as well, since regimes such as the GENIUS Act and Hong Kong’s Stablecoins Ordinance require full reserve backing and regular reserve disclosure.
Stablecoin issuers face stablecoin-specific rules on licensing, reserves, redemption and disclosure, such as MiCA in the EU, the GENIUS Act in the United States and the Stablecoins Ordinance in Hong Kong. AML law applies alongside those rules, and in certain jurisdictions issuers count as financial institutions whose programmes must cover customer identification, due diligence, suspicious activity reporting and sanctions. The currency a token is pegged to can also bring an issuer under another country’s licensing regime wherever the issuer is based.
An unhosted wallet, also called a self-hosted wallet, is a crypto wallet that the customer controls directly rather than through a provider. Transfers to and from these wallets need extra care because no provider sits on the other side to receive or confirm the customer’s details. In the EU a provider must assess whether its customer owns or controls a self-hosted wallet for transfers above EUR 1,000, and the accepted methods include a signed message and a small test transfer.
The Travel Rule requires sender and recipient information to travel with each qualifying crypto transfer between providers, and FATF standards apply it to businesses that exchange, hold or transfer stablecoins for customers. The FATF’s June 2025 update requires cross-border payments between individuals above USD or EUR 1,000 to carry names, addresses and dates of birth, and countries have until the end of 2030 to adopt it. In the EU the Travel Rule already applies to every crypto transfer between providers with no minimum amount.
Stablecoin infrastructure providers supply virtual accounts, on- and off-ramps and settlement to other financial firms, and each of their licensed entities needs the registration and AML programme that its market prescribes. These providers run KYB on every client platform and own end-user due diligence unless reliance on a regulated client is lawful. They also apply the Travel Rule including any duties for intermediaries and screen parties and wallet addresses while they monitor third-party pay-ins.