

 AMLR Solutions
 AMLR Consultation
 EUDI Wallet
 Onboarding
 Ongoing Monitoring
 FRAML
 KYC
 KYB
 KYI
 Age Assurance
 Workforce IAM
 Candidate Verification
 Account Takeover
 Bonus/ Promotion Abuse
 Chargeback Fraud
 Deepfake
 Document Fraud
 Fraud Networks
 Impersonation Fraud
 Money Mule Activity
 Multi-Accounting
 Party Fraud
 Regulatory & Compliance Risks
 Synthetic Identity Fraud
 Adult Content
 Banking
 Crypto
 Fintech
 Forex
 Compliance
 Fraud prevention
 Trust & safety
 Global expansion
 Compliance Officers
 Developers
 Fraud Analysts
 Product Managers
 Journey Builder
 Global Trust Platform
 Customer Profiles
 Vendor Comparison
 IDV Case Management
 AML Case Management
 Regulatory Reporting
 Agentic Rule Builder
 AI Compliance Co-Pilot
 Fraud Analytics
 Fraud Hub
 OCR
 Shufti AI
 Bank Account Verification
 Biometric Duplication
 Database Checks
 Document Intelligence
 Government ID
 Mobile Driver's License
 NFC
 Selfie Liveness
 Brand Personalisation
 Deployment Options
 Identity Methods
 IDV Modes
 Multi-tenancy
 On-Premise IDV
 Secure Capture
 Shufti MCP


ComplyAdvantage vs Shufti
The ComplyAdvantage Alternative for Complete Risk Lifecycle
From Transaction Monitoring and AML Screening to Fraud Prevention
Bring identity verification, AML screening and transaction monitoring into one Shufti platform. Connect transaction alerts with available identity and device evidence so analysts can review the customer and the activity together. Compare that approach with ComplyAdvantage's monitoring and screening platform below.
DETAILED CAPABILITY COMPARISON
Compare the Risk Context Behind Each Monitoring Decision
Both platforms apply rules and machine learning to transaction risk. For businesses evaluating alternative to ComplyAdvantage and its cloud-based Mesh platform, the difference lies in the evidence available for each decision. This comparison shows which identity, device, behavioural, AML, and investigation capabilities are native, integrated, or customer-supplied, and how well they perform across the compliance lifecycle.
Built-in identity verification. Document verification and liveness operate within the same platform used to assess transaction risk.
Partner-integrated identity verification. ComplyAdvantage lists identity and KYC providers as partner categories rather than native products.
Native device and behavioural signals. Device fingerprinting, behavioural biometrics, geolocation, document forensics and liveness can feed the risk decision.
Customer-supplied event data. Device, login and account-change events must be captured and sent into the platform.
Unified first-party stack. Identity, device, screening, and monitoring capabilities operate within a single platform.
Monitoring-led platform with partner integrations. Identity capabilities are provided through external integrations.
Identity-anchored risk context. Transactions are assessed alongside verified identity, device, behaviour, screening and counterparty signals.
Transaction and event-data context. Rules and machine learning assess the fields supplied through the monitoring schema.
Preconfigured fraud and AML typologies. Coverage includes structuring, smurfing, mule activity, corridor risk, beneficiary risk and linked-account patterns.
Prebuilt and configurable scenarios. Published coverage includes more than 50 fraud scenarios; confirm the scenarios, data requirements and tuning available for your use case.
AI can draft and back-test rules, but a compliance reviewer approves them before production deployment.
AI-assisted rule creation and testing. Rules can be drafted, validated and tested within a sandbox environment.
Explicit Not Assessable outcome. Missing fields remain visible instead of being treated as low risk.
Not publicly documented. Current product pages do not state how incomplete fields are classified.
Per-customer behavioural baselining. Current activity is compared with the customer's own 90- day history.
Historical pattern analysis. Behavioural rules and dynamic thresholds compare activity with previous patterns.
End-to-end investigation and filing workflow. Supports escalation, four-eyes review, regulator- ready exports and audit history.
Case-management and reporting support. Includes multi-stage review, alert-to-case grouping and selected regulatory-report formats.
Identity-to-transaction fraud detection. Covers account takeover, mule activity, synthetic identities, multi-accounting and abuse patterns using identity and device context.
Payment- and transaction-fraud detection. Supports more than 50 scenarios across APP, BEC, ACH, wire and real-time payments.
Native deepfake and injection-attack detection. Identity controls cover both compressed and re- uploaded media, as well as multiple injection-attack vectors.
No equivalent native capability publicly listed. Current product materials do not show deepfake, liveness or injection-detection products.
Independent testing includes iBeta Level 3 PAD conformance (0% errors across iOS and Android) and the DHS Remote Identity Validation Rally, where Shufti met all performance goals.
No like-for-like biometric product publicly available for comparison. Its published portfolio does not include biometric or liveness products.
Identity- and device-linked network detection. Accounts can be linked through face, device, email, phone, IP, and beneficiary overlap.
Transaction-graph network detection. Identity clustering and graph analysis identify relationships across transaction flows.
Cross-layer risk inputs. Models analyse identity, document, device, behavioural and transaction signals.
Customer-provided transaction and event inputs. Models analyse the records and fields supplied to the platform.
AI-assisted, analyst-controlled decisions. AI classifies hits and produces rationale, while analysts retain final decision authority and MLROs approve production rules.
Automated false-positive resolution with escalation. AI agents resolve routine alerts and escalate exceptions with written rationale.
Cross-layer investigation context. Identity, device, location, screening, counterparty, and previous case information appear in a single view.
Transaction-centred investigation context. Its 360- degree risk view combines counterparties, amounts, timing and behaviour.
First-party MCP integration available. Supported AI clients can initiate IDV, KYB and AML checks.
No first-party MCP integration publicly documented.
Flexible deployment. SaaS, private cloud, on- premises, and air-gapped options are available.
Cloud deployment publicly documented. No on- premises option appears in current public product materials.
Regional residency options across the EU, UK, US, APAC and MENA, including the UAE and KSA, plus on-premises and air-gapped deployment for stricter localisation.
Its public login guide lists European, UK, US, Australian and Canadian regions.
One record for identity, ownership and screening; eIDV across 40+ schemes; KYB UBO mapping at 25%; 15-minute sanctions/PEP updates; compliance review before rules apply; EU residency or on-premise hosting.
Screening covered; identity verification, ownership evidence and UBO discovery via partners. Sanctions update in minutes; four PEP classes; full EU PEP mapping roadmap through 2027. Cloud-only.
Sandbox access on the day you sign up for identity and screening, and within 24 hours for transaction monitoring.
Self-serve for screening, sales-led for monitoring. Starter-plan buyers receive sandbox and production credentials within 24 hours, but Transaction Monitoring and Payment Screening are Enterprise-only and quoted through sales.
Identity verification and AML screening: 10 free checks/month, then $1.50/check on self-serve Essentials (20,000 checks). Transaction monitoring: volume-based pricing during evaluation. (Shufti pricing page)
100 monitored entities for $99/month billed annually ($119 monthly); 2,000 for $319/month. Transaction Monitoring and Payment Screening: custom-priced Enterprise only. Median annual spend: $52,900 (Vendr, February 2026).
/5
Praised for speed and a simple flow.
/5
Unclaimed profile with a single review, too few to draw a conclusion from.
/5
Reviewers cite ease of use and flexible onboarding journeys.
/5
Reviewers flag false positives, missed adverse media and cluttered alert displays.
/5
Fast checks and easy device switching.
/5
Only two reviews, from 2018 and 2023. The 2023 review flags false positives.
Review scores were taken from Trustpilot, G2 and Capterra on 9th September 2026. Trustpilot reflects end users of Shufti's verification flows, while G2 and Capterra reflect B2B buyers and carry far fewer reviews for both vendors. ComplyAdvantage plan names and prices are from complyadvantage pricing page. Deployment and hosting statements are from complyadvantage mesh page and docs page. Partner-delivered identity verification is from partner page and the Sumsub partnership release of 26 March 2026. Fraud scenario coverage is from fraud-detection page of complyadvantage. Agentic alert handling is from agentic-workflows and ComplyAdvantage's support article on Agentic AI Auto-remediation. Contract benchmarks are from vendr.com/marketplace/complyadvantage, last updated February 2026. Shufti liveness testing is from iBeta's ISO 30107-3 confirmation letters page (Level 3, 24 April 2026). DHS RIVR 2025 results are anonymised by DHS; Shufti was one of the systems that met all performance goals in the selfie-to-document track. Shufti product, pricing and deployment figures are from shuftipro.com. All ComplyAdvantage pages were checked on 9th September 2026.
LET'S GET SPECIFIC
Test Us With Your Edge Cases
Alert queue growing faster than your team? False positives eating analyst hours? Screening and monitoring in two systems that never talk? Send us a sample of your alerts and we will show you the same cases with identity evidence attached.
Request A Customised Demo
PLATFORM ARCHITECTURE
Unified Platform or Integrated Stack: Where the Difference Appears
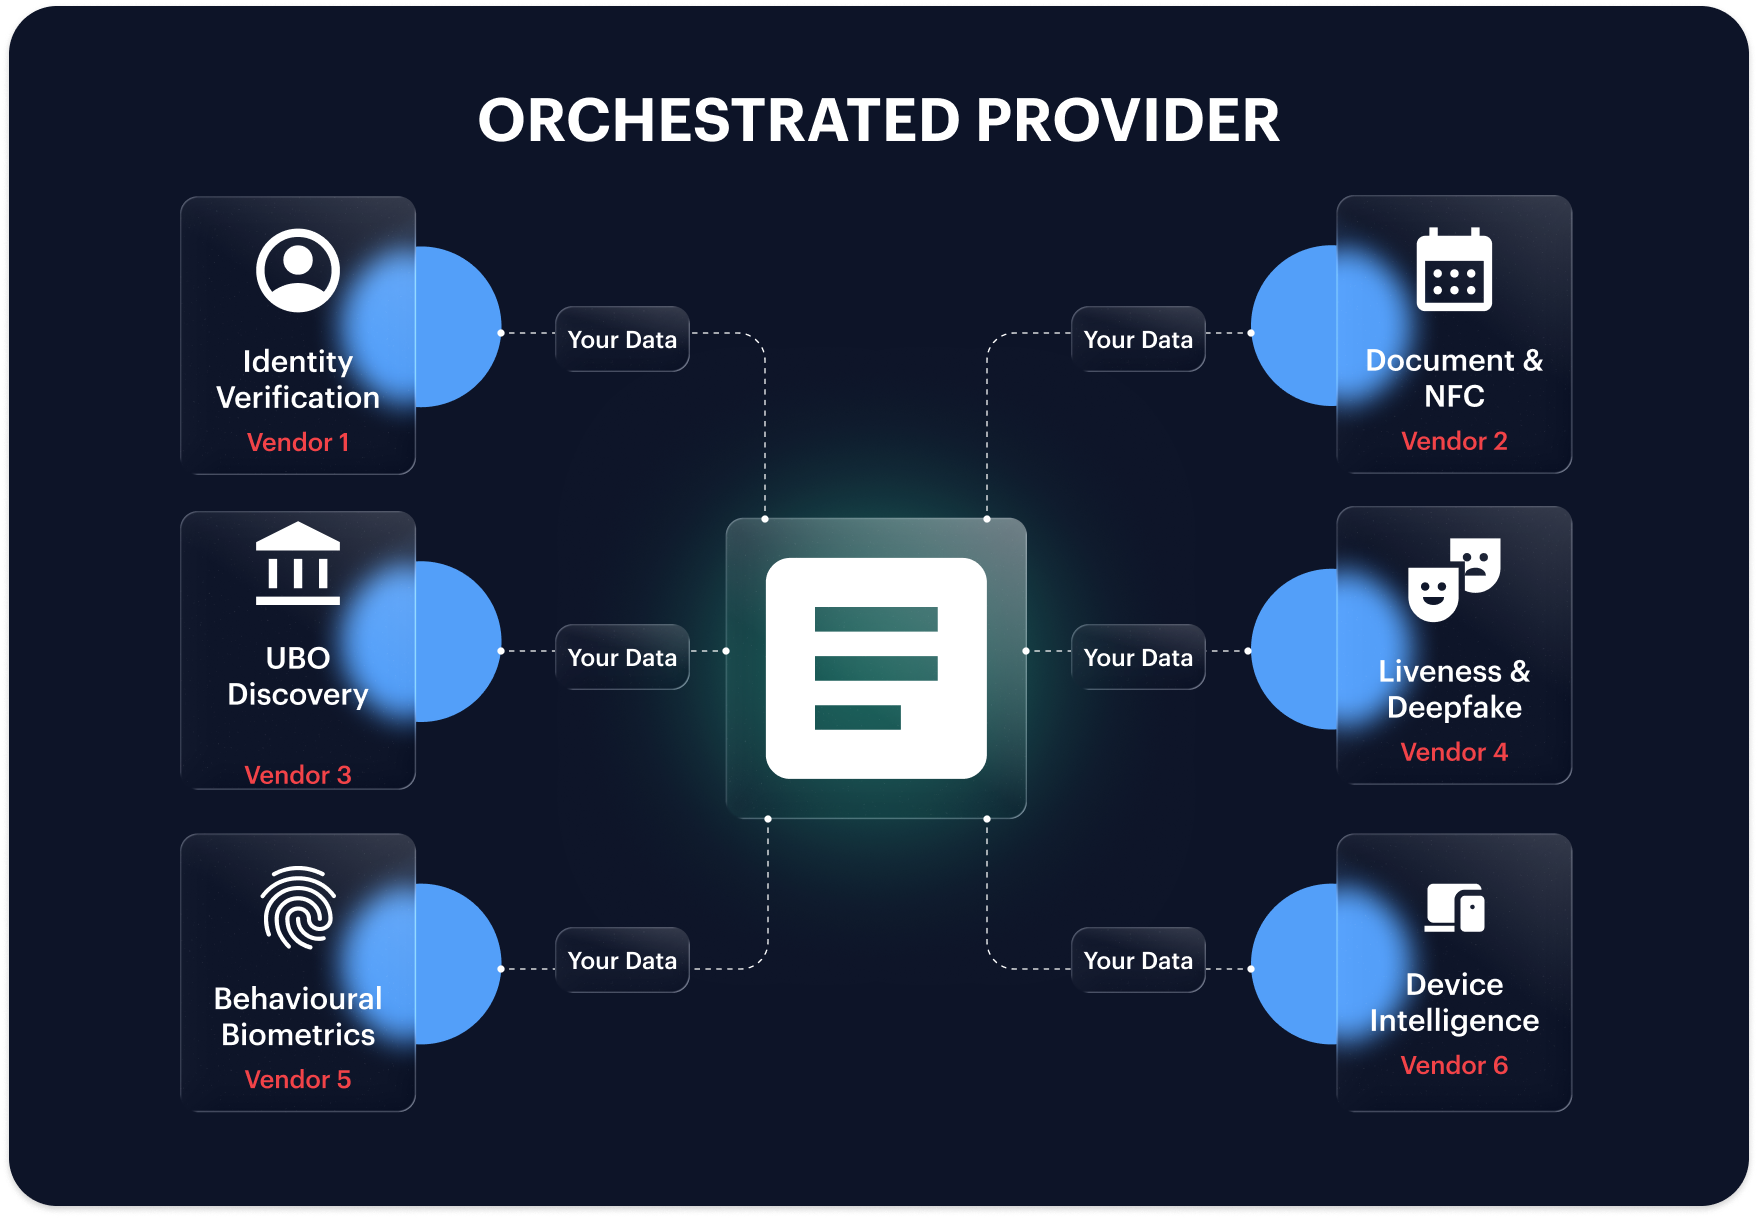
With ComplyAdvantage, identity, device and transaction context may be supplied by separate systems. That can preserve an existing vendor stack, but each added system brings integration effort, data mapping and vendor governance. And every handoff between systems is another place where evidence can drop out of the risk decision.
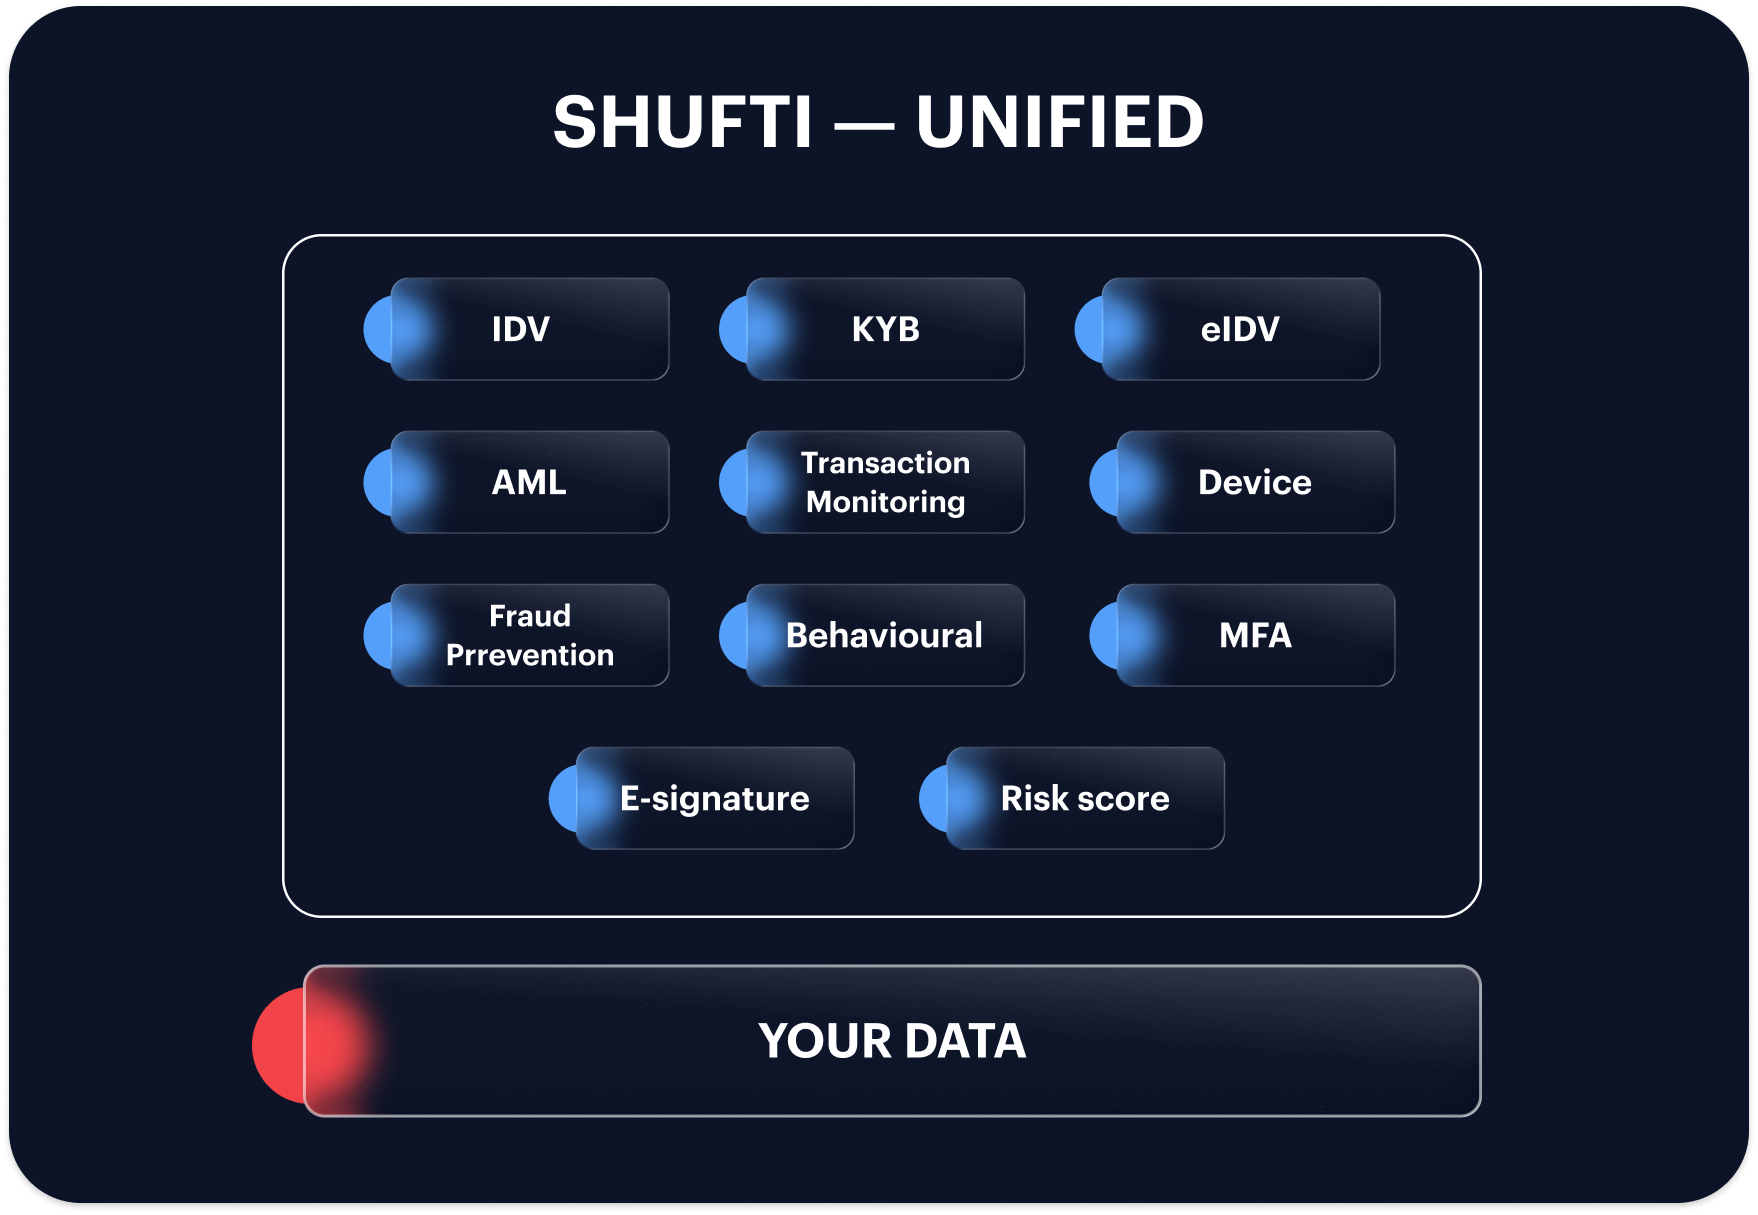
Shufti brings identity verification, device intelligence, behavioural analysis, screening and transaction monitoring into one platform, reducing the number of core handoffs behind each risk decision.
DON’T JUST TAKE OUR WORD FOR IT, HEAR FROM OUR CUSTOMERS
The Confidence
Our Clients Share
Score
“We’re proud to have one of the lowest fraud rates of any gaming marketplace globally and we are always searching for new solutions to better improve the safety of our customers. Shufti provided the most effective KYC solution, allowing us to streamline our customer’s experience on the Kinguin Marketplace, ensuring purchases are as secure and convenient as possible.”
Onboarding
Rate
“We take our clients’ privacy very seriously, and we want them to know that we are constantly looking for new innovative solutions to ensure a safe banking experience. This is why we are proud of our recent partnership with Shufti, the AI-powered identity verification solutions provider, which will provide state-of-the-art identity verification. This collaboration falls under our strategy to provide a seamless and secure digital experience for our valued customers who prefer to use our online platform. We aim to improve our online banking and create an even safer service through the “Safwa Mobile” application.”
“As a relatively new brand, we need to absolutely ensure that initial brand interactions between Mintus and our customers are slick and smooth. To achieve this we need technology that is highly customisable to our needs and able to accurately verify individuals from across the globe. Not only does Shufti deliver this, it also does it quickly and easily – something our customers truly appreciate. We estimate that £150m of painting investments will be verified by Shufti this year.”
Score
“When potential customers informed us that our lengthy verification processes were hindering their due diligence verification, we knew we needed to make changes. Shufti had a reputation as a leading authentication expert that would be able to streamline our processes, while enhancing our risk detection. Through partnering with the team at Shufti we’ve been able to grow our customer numbers by 20%. At the same time we’re able to streamline their experience while on our platform and stop under-aged users and potentially fraudulent users from accessing our services. It’s a win win.”
“Given that we’re working with such vulnerable people, knowing exactly who is volunteering with us is vital, particularly as we need to have a large team on the ground. We needed a secure system that was not only highly accurate, but also time-saving. Shufti eliminated the need for our staff to implement extensive, manual ID verification processes and instead enabled us to focus on our two main projects in Ukraine – to deliver support to as many people as we can, and to grow the capacity of the charity so we can help even more people.”
BUILT TO EVOLVE
Adapt Rules Faster Without Removing Human Oversight
Model Ownership
Shufti develops its core identity, screening, and monitoring capabilities in-house, enabling signals and model updates to operate across a single platform. During evaluation, compare model ownership, update cadence and third-party dependencies across both vendors.
Emerging-Typology Speed, With Governance
Describe an emerging scheme, use the AI Wizard to draft a rule, back-test it against historical data and require MLRO approval before deployment.
Honest Data Handling
A field the engine cannot assess is a finding, not a default. Not Assessable results keep incomplete data visible to your analysts and your auditors, because risk hides best in silent gaps.
One Risk Memory
A composite risk view combines recent behaviour, linked-account patterns and identity history so fraud and AML teams can investigate from the same evidence base.
ZERO DISRUPTION
Migrate to Shufti in 48 to 72 Hours.
Switching to Shufti is a redirect, not a rebuild. Your existing verification logic maps onto Journey Builder. Your engineers point one config file at Shufti’s API, which mirrors your current request and webhook shape.
- 0DAY 0. MAP THE WORKFLOW
Map the workflow
Your current logic maps onto Journey Builder.
- 1DAY 1. REDIRECT ENDPOINTS
Redirect endpoints
One config file points at Shufti's API. Same request and webhook shape.
- 2DAY 2. GO LIVE
Go live
Switch live traffic when you are ready. No downtime.
INDEPENDENT VALIDATION
Shufti's Recognition Across Independent Evaluations
Trusted By 2000+ Businesses Across 240+ Countries And Territories
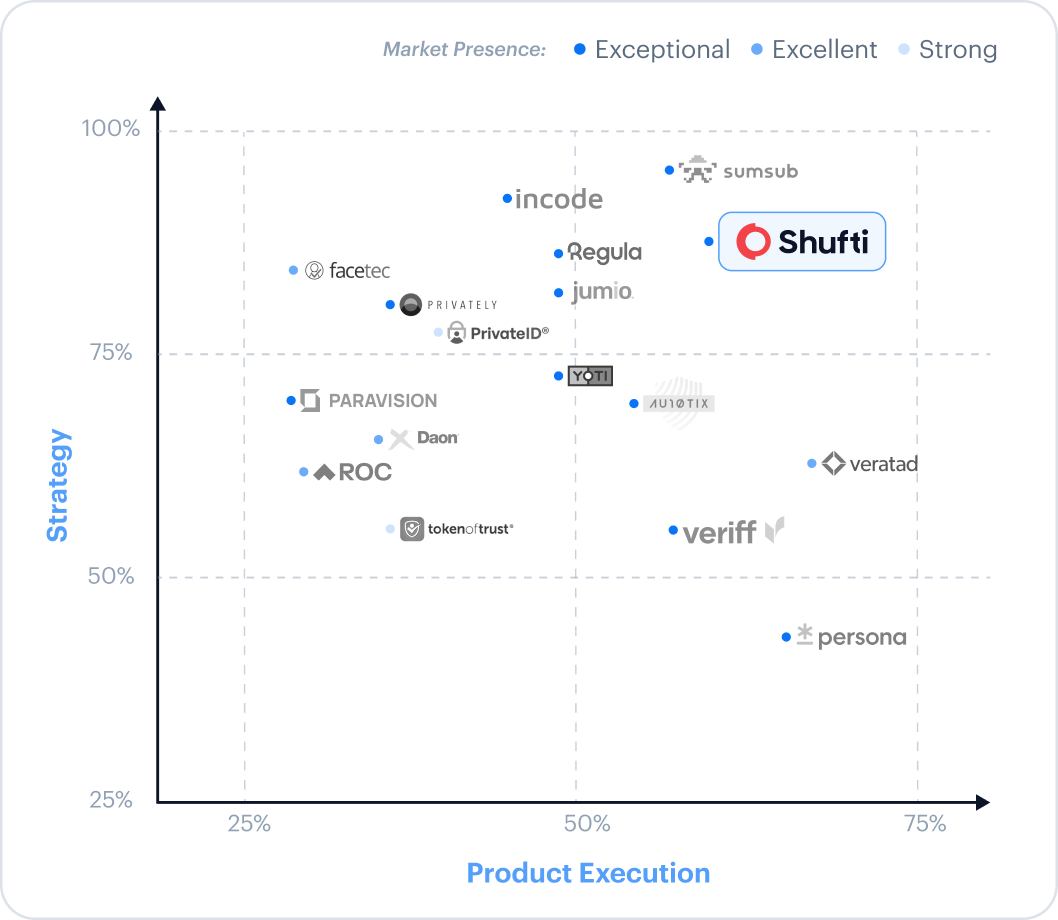
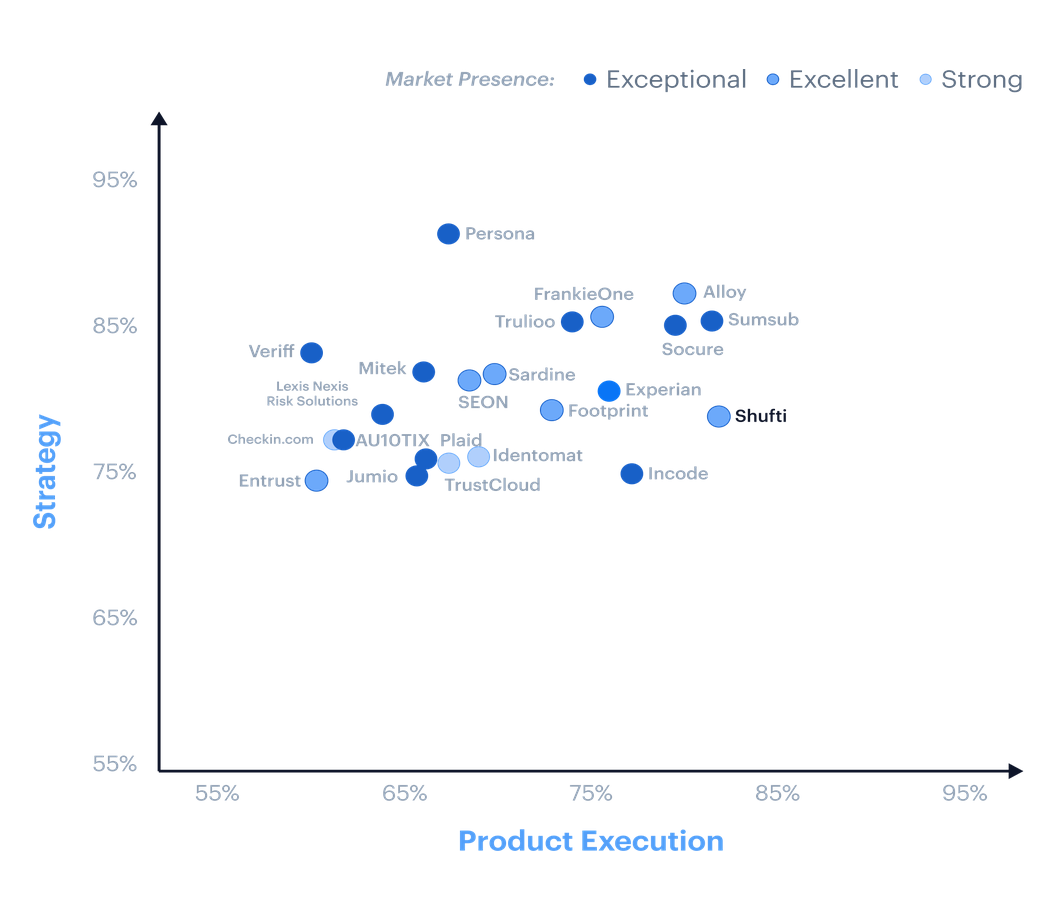
Ranked Exceptional in the Liminal Index 2026 for age estimation
View Report
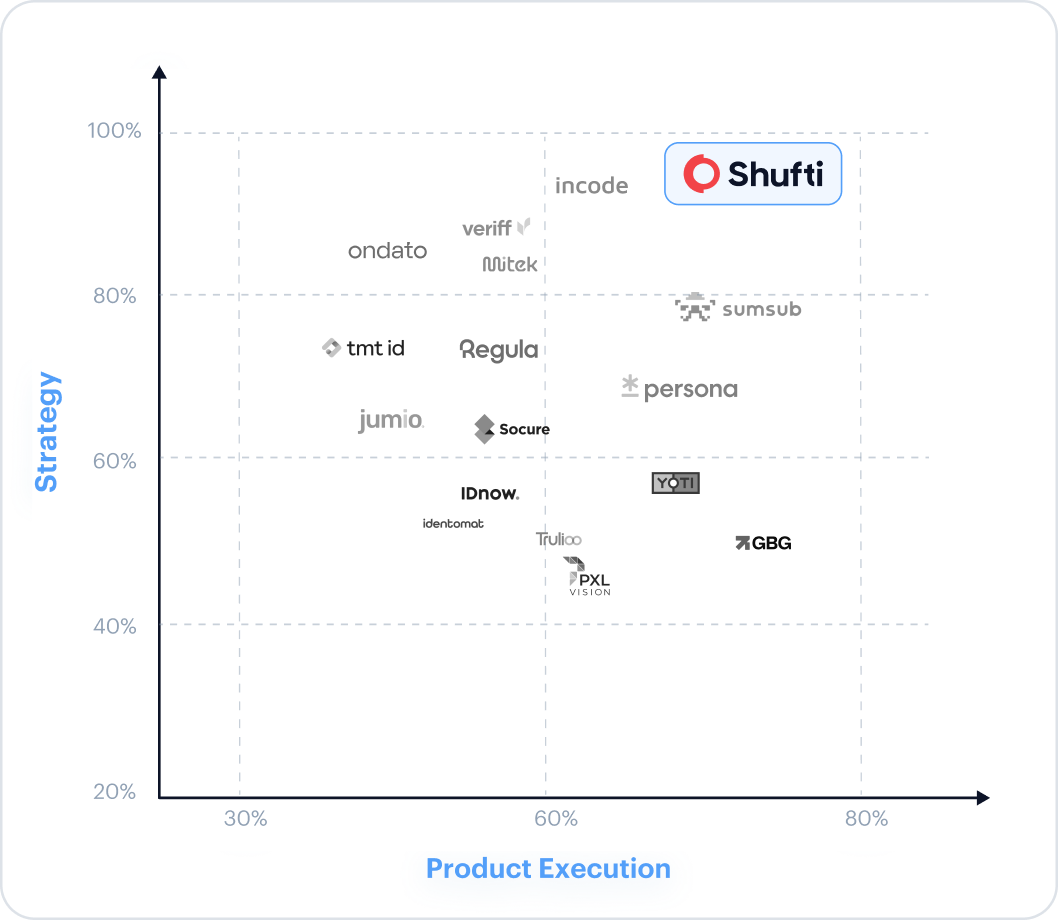
Differentiated by Gartner on document diversity and country coverage
Read more
Certified at iBeta Level 3 PAD with 0% APCER
Read Blog
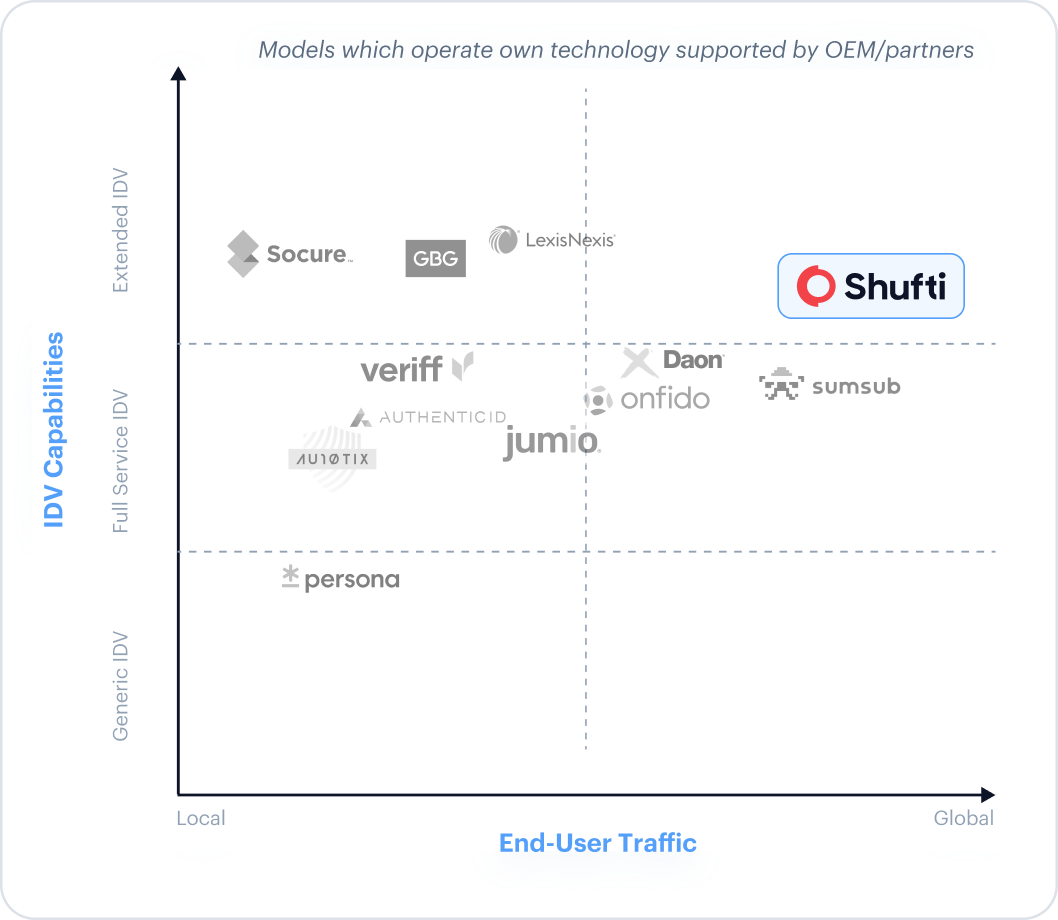
Broadest global reach in the 2025 KuppingerCole Extended IDV report
Download Report
Ranked Top 5 in the DHS RIVR 2025 for identity validation
Read Blog
Top Vendor for Product Execution in the Liminal Index for KYC 2026
View Report
Ranked Exceptional for age verification by Liminal Index 2026
View Report
Recognised as a Leader in G2 Fall 2026 reports
Read More
QUESTIONS YOU MAY HAVE
What Teams Ask Us Before They Switch
Direct answers to the questions that decide a vendor.
The same engine that runs Shufti's identity verification, fraud detection and AML screening for 2,000+ businesses, with ID document coverage across 240+ countries and territories. Its 40+ ensemble models, nine-layer document forensics, device fingerprinting, behavioural biometrics and screening data refreshed every 15 minutes all feed the transaction score, and every alert carries the evidence trail behind the decision. The engine that verifies the identity is the engine that scores the transaction.
Shufti includes identity verification, liveness, document forensics, device fingerprinting and behavioural signals natively. Whether you can retire existing vendors depends on your required coverage, architecture and contractual commitments. For teams evaluating ComplyAdvantage alternative, this unified approach reduces the need to manage separate identity, device and monitoring providers.
A simple one-to-one “match” claim would be misleading because providers structure and disclose coverage differently. When evaluating ComplyAdvantage vs Shufti, compare sanctions regimes, PEP records, adverse-media sources, refresh frequency, language coverage and performance against your own high-risk sample. Shufti publishes coverage across 215+ jurisdictions, 4,000+ watchlists and 2.6 million+ PEP records, refreshed within minutes.
Yes. The complete platform, covering identity verification, fraud detection, AML screening and transaction monitoring, deploys as SaaS, private cloud, on-premises or air-gapped with feature parity, and residency is documented across the EU, UK, US, APAC and MENA. For organisations comparing Shufti vs ComplyAdvantage, deployment flexibility can be an important consideration. ComplyAdvantage describes Mesh as a cloud-based platform, and no on-premises option appears in its current public product materials.
Shufti's identity verification and AML screening start free with 10 checks per month, then run at $1.50 per check on the self-serve Essentials plan for 20,000 checks, with transaction monitoring priced to volume as part of the evaluation. ComplyAdvantage's Starter plan runs from $99 per month for 100 monitored entities on annual billing (rising to $319 per month at 2,000 entities), but Transaction Monitoring and Payment Screening sit only on its custom-priced Enterprise plan, where Vendr's contract data puts the median buyer at $52,900 per year. In short, Shufti publishes self-serve pricing across the stack; ComplyAdvantage moves to sales-led enterprise pricing once transaction monitoring is involved.
AI can classify hits, draft rationale and support rule creation, while analysts retain final case decisions and MLRO approval is required before rules go live. When assessing a ComplyAdvantage alternative, organisations should compare not only AI capabilities but also how each platform maintains human oversight and governance.
Migration from ComplyAdvantage to Shufti can be done in 48 to 72 hours. Define success metrics, test both platforms on an approved data sample and plan production migration around your technical, governance and procurement requirements. Businesses exploring a ComplyAdvantage alternative should evaluate migration timelines alongside implementation support, workflow fit and operational requirements.
Own the Stack.
Pass the User.
2000+ businesses run on Shufti because they want to own every layer and watch more of their users get through. The migration is low-risk.
Use the first 10 free verifications to test our claims