us

207.46.13.83

The Ultimate Guide to Bank Account Verification — guide cover

The Ultimate Guide To Bank Account Verification

What it proves, and what it does not

Bank account verification confirms who controls an account before money moves. The methods, the global rules, and where each one stops.

Schedule a Demo
Why the question got harder

Real-time payments removed the delay and kept the risk

Not long ago, paying somebody meant a cheque in the post or a queue in a branch, and the days it took to settle did real work, because somebody usually had time to catch a mistake before the money was gone.

Merchants now pay out to sellers, riders and creators they will never meet, and fintechs link external accounts and approve withdrawals faster than any manual team could review them. Every one of those moments turns on the same question. Does this account belong to the customer whose name is on the file?

233,000
Unique stolen cheque images, 2025

Recorded Future’s annual payment fraud research, published by Mastercard in March 2026, found the number of unique stolen cheque images rose for the first time in 2025, each one carrying an account number and a signature.

This guide is about the gap between an account that is valid and an account you can trust.

Three questions, not one

Validation, verification and ownership are not the same check

The three terms get used as if they mean the same thing, and the mix-up is expensive. Each rung down the ladder costs more and takes longer, and where you stop is a risk decision rather than a technical one.

Validation

The account number or IBAN is correctly formed and the account exists. Misses everything about who owns it.

US · Nacha WEB debit

Verification

The name registered to the account matches the name you hold. Misses whether your customer is that named person.

EU · VoP · UK · CoP

Ownership verification

A verified identity is bound to the account and re-confirmed at risky moments. Control can still change later.

No regime requires it
The methods

Four methods, and what each one costs you

Four bank account verification methods cover almost everything in use today. Each answers a slightly different question, and none confirms ownership on its own.

MethodWhat it provesSpeedOwnership evidenceMain weakness
Open banking (AIS)The customer authenticated with their own bank and the data came from the bankSecondsStrongOnly works where an open banking regime exists
Instant auth (aggregator)Somebody authenticated to the account using valid credentialsSecondsMediumCredentials get shared, bought and handed over
Network or payee checkThe registered holder name matches the name you submittedSecondsMediumA mule account carries a perfectly genuine matching name
Micro-deposit or penny dropA small credit reached the account, and some markets return the holder name with itSeconds to daysMediumThe classic version needs a second visit, and most people do not make it

Drop-off risk describes what the method asks of the customer, not the quality of the answer it returns. The two move in opposite directions more often than not.

The public schemes

EU, UK and US rules each check something different

Account checking has gone from a private control to a public scheme in market after market. Tell them apart and you stop assuming a regulator has already solved a problem it never touched.

European Union

Verification of Payee

The payee name against the IBAN before a credit transfer is authorised

Live from9 October 2025 in the euro area, 9 July 2027 outside it
Proves ownershipNo
United Kingdom

Confirmation of Payee

The payee name against the account number and sort code before a payment is sent

Live from31 October 2024 for Group 2 providers under Specific Direction 17
Proves ownershipNo
United States

Nacha WEB debit validation

That the account number is valid before a first WEB debit or after a change

Live from19 March 2021
Proves ownershipNo

Coverage by region

Where a check exists, and what it actually returns

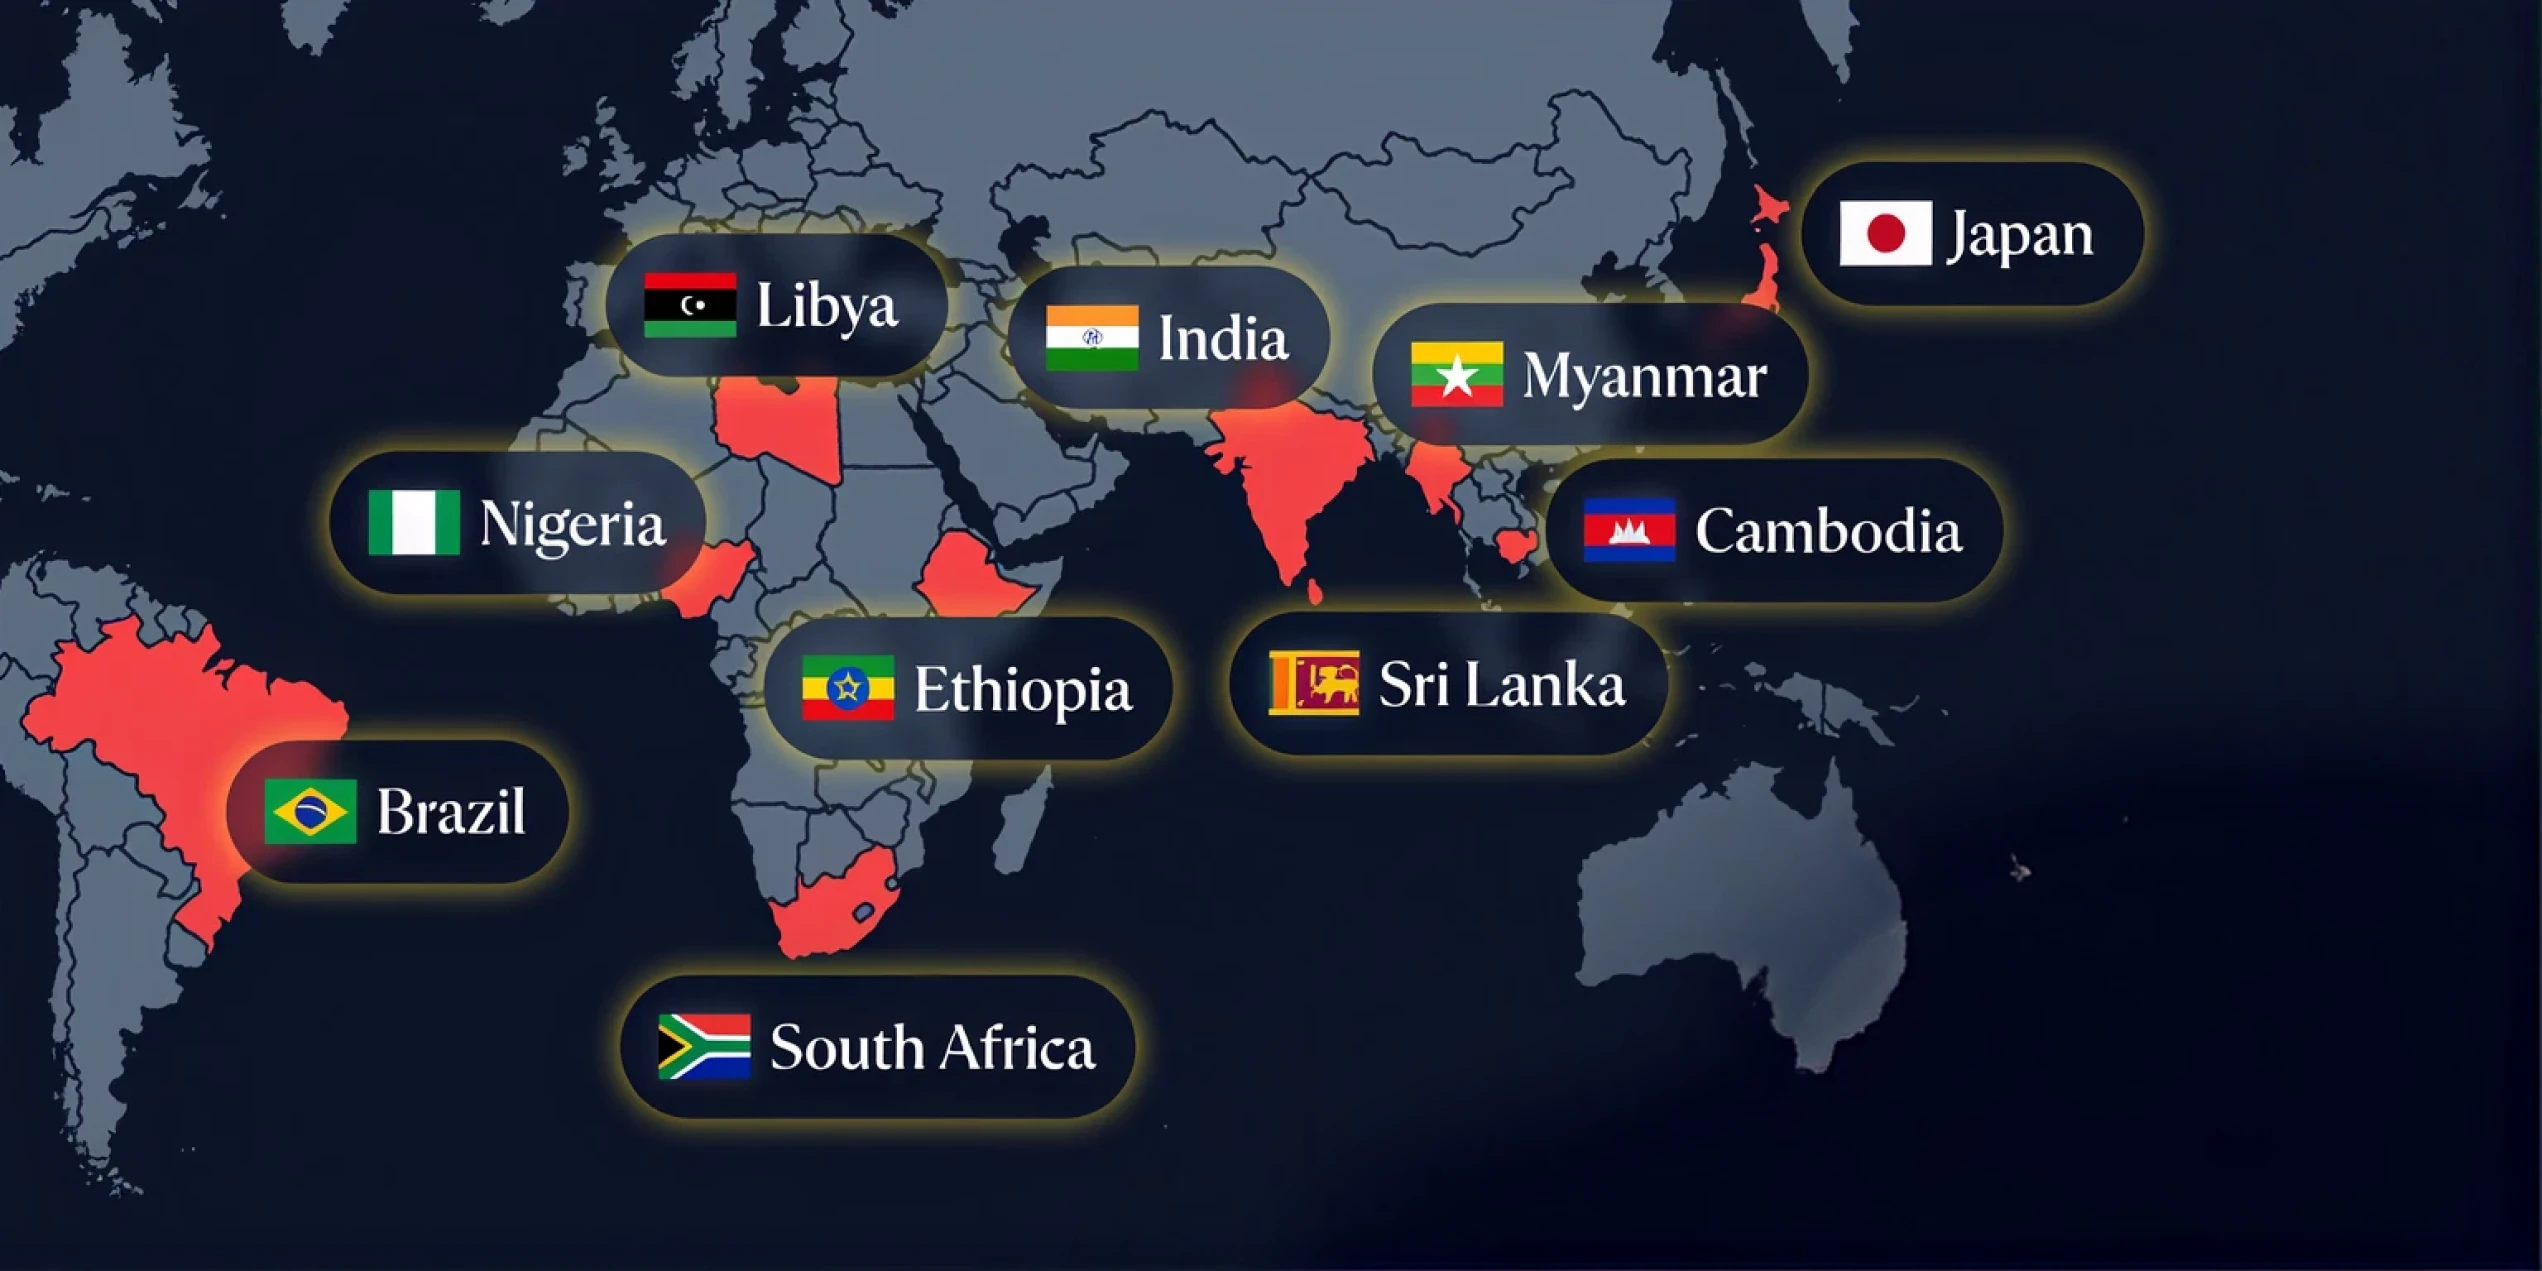
The following map highlights Shufti’s Bank Account Verification coverage by country and region and shows the type of account information or verification result that will be returned in each market.

Loading map geometry

Hover or tap a market. Markets too small to read at this scale are drawn as dots.

MarketRegionWhat the check returnsSources

Where a market is covered by more than one source and the sources return different checks, the map shows the deepest check available and the table lists both.

Emerging markets

Several of the fastest-growing schemes sit outside Europe and North America

A flow built around IBANs and name matching will not survive contact with an alias-addressed rail, or with a market that matches on identity rather than name.

India

RBI circular RBI/2024-25/99

Every bank must show the name on the receiving account before money is sent, free of charge, since 1 April 2025. If no name comes back you are still allowed to send.

Nigeria

NIBSS Name Enquiry · BVN

Name Enquiry is built into the shared network all Nigerian banks sit on, and the Bank Verification Number ties one biometric-linked ID to a customer at every bank.

South Africa

Account Verification Services

You buy the check rather than getting it from the payment system, and because it matches the person’s ID details it comes closer to proving ownership.

The UAE

Aani · Al Etihad Payments

Money is sent to a mobile number, email address or QR code, so what you confirm is the shortcut somebody registered, not an account number.

The fraud that survives

Which fraud patterns survive a name check?

Two of them, and they are connected. Authorised push payment fraud and mule accounts both work by making sure the name on the receiving account is genuine, which turns a green light into part of the attack.

£85,000

Per-claim UK reimbursement ceiling for Faster Payments APP scams since 7 October 2024

10,759

Money mules identified by Europol’s ninth European Money Mule Action, reported December 2023

None

Of the EU, UK and US schemes confirms who actually controls the receiving account
The Ultimate Guide to Bank Account Verification — guide cover
Guide page — validation, verification and ownership
Guide page — the four verification methods compared
Guide page — EU, UK and US scheme rules
Previous
01 - 04
Next

Certifications

Independently audited and certified for enterprise-grade security and data protection.
  • GDPR Compliant
  • GDPR Fundamentals
  • ISO 27001 Certified
  • CCPA
  • iBeta Level 3 ISO 30107-3 Compliant
  • PCI DSS Compliant
  • Shufti SOC 2 Type 2 Compliant

    search_cross_mobile

    Please complete the information below 
to download the whitepaper

    By clicking the "Submit" button, you are agreeing 
to the Terms & Conditions and Privacy Policy

    Frequently asked questions (FAQs)

    In several markets the check is now mandatory at the payment rail rather than at onboarding. The EU’s Verification of Payee has applied in the euro area since 9 October 2025 and applies outside it from 9 July 2027, the UK’s Confirmation of Payee has covered Group 2 providers under Specific Direction 17 since 31 October 2024, and Nacha has required account validation before a first WEB debit since 19 March 2021. None of those rules asks you to prove that your customer controls the account, so ownership verification stays a risk decision you make yourself.

    Was this content helpful?

    Yes. Open banking, instant account authentication through an aggregator, and a network or payee name check all return an answer in seconds without asking the customer to wait for a small credit to land. Micro-deposits still have a place where no other route exists, but the classic version needs a second visit from the customer and most people do not make it.

    Was this content helpful?

    It is the check that answers who is behind an account before money moves, and it runs at three levels. Validation confirms the account number or IBAN is correctly formed and the account exists, verification confirms the name registered to the account matches the name you hold, and ownership verification binds a verified identity to the account and re-confirms it at risky moments.

    Was this content helpful?

    No. Both confirm that the payee name matches the account held at the receiving bank, and neither confirms that the person in front of you controls that account. A mule account carries a perfectly genuine matching name, which is exactly why authorised push payment fraud and mule networks survive a name check.

    Was this content helpful?

    A docless check needs none. Open banking and instant authentication use the customer’s own bank credentials, a network or payee check uses the account identifier and the name, and a micro-deposit uses a small credit to the account itself. Documents such as a bank statement or a voided cheque are a fallback rather than a primary route, and they carry their own risk: 233,000 unique stolen cheque images were recorded in 2025, each one showing an account number and a signature.

    Was this content helpful?

    Open banking, instant authentication and network or payee checks return in seconds. A micro-deposit or penny drop takes seconds to days depending on the rail and on whether the customer has to come back to confirm the amount. Speed and ownership evidence do not move together, so the fastest check is not automatically the weakest one.
    Was this content helpful?
    n-img-roi-cross

    Form submitted successfully!

    Thank you for your interest — your report is loading now.

    Verify who controls the account, not only the name on it

    See what one flow looks like when it runs open banking where a regime exists, a network or payee check where the scheme mandates one, and a verified identity bound to the account where ownership is what you actually have to prove — across the EU, the UK, the US and the fastest-growing markets outside them.

      Let’s Tailor Your Journey

      Which products would you like to check out?

      VideoIdent

      Address Verification

      eIDV (Docless)

      KYB

      AML Screening

      Deepfake Detection

      Face and ID Verification

      Age Verification

      Others

      What is your expected yearly verification volume?

      1 to 1,000

      1,001 to 5,000

      5,001 to 20,000

      20,001 to 50,000

      50,001 to 100,000

      100,001 to 1,000,000

      1,000,000+

      Valid Invalid number

      By clicking Submit, you accept our Privacy Policy and consent to marketing communications.

      Product Guide

      Docless Identity Verification Guide for Latin America

      docless-identity-verification-latin-america-ftr-img
      Product Guide

      KYB Compliance & UBO Verification Requirements in UAE

      kyb-compliance-ubo-verification-uae-ftr-img
      Product Guide

      How to Remediate Existing Clients’ Files Under EU AMLR

      eu-amlr-existing-customer-file-remediation-ftr-img
      report

      iGaming Fraud Report 2026 | Fraud Detection & Bonus Abuse Trends

      igaming-fraud-report-ftr-img
      report

      Forex Fraud Report 2026 | Identity Fraud Trends in Forex

      forex-fraud-identity-fraud-report-2026-ftr-img
      Product Guide

      Risk-Aligned Transaction Monitoring Process to Reduce Alerts

      Product Guide

      Crypto Compliance Maturity Model | Free Self-Assessment

      Crypto Compliance Maturity Model
      Product Guide

      Qualified Electronic Signature: EU & EEA Country Guide | Shufti

      report

      Identity Fraud Report 2026 | Shufti

      Identity Fraud Report 2026
      Product Guide

      Guide to Docless Identity Verification in the US and Canada

      Docless Identity Verification Us Canada
      Product Guide

      AMLR Readiness Checklist: 2027 Gap Assessment | Shufti

      Amlr Readiness Checklist
      Product Guide

      Shufti’s 2026 Context Gap in AML Risk Assessment

      The Context Gap In Aml Risk Assessment
      Product Guide

      Customizable KYC Solution for KYC Product Owners

      Customizable Kyc Solution For Kyc Product Owners
      Product Guide

      Docless KYC Verification in APAC to Onboard More Genuine Users

      Cover of the Shufti guide to docless KYC verification in APAC
      Product Guide

      EU AMLR Guide 2027: Requirements, Scope, Deadlines | Shufti

      Eu Amlr Compliance Guide
      Product Guide

      APAC Child Safety Age Verification Regulations

      APAC Child Safety Age Verification Regulations
      Product Guide

      Docless Identity Verification in the Middle East

      docless-identity-verification-middle-east
      Product Guide

      The Future of Docless Verification in Europe

      Onboard already verified users with Docless Verification in Europe
      Product Guide

      Cyprus 2026 KYC Operators Guide to Improve First Pass Rate

      Cyprus 2026 KYC Operators Guide to Improve First Pass Rate
      Product Guide

      Philippines KYC & Account-Owner Verification Playbook | Shufti

      Philippines KYC & Account-Owner Verification Playbook | Shufti
      Product Guide

      Digital Lending KYC Guide for Mexico: INE/IFE, CURP, RFC, Liveness and AML Controls

      Digital Lending KYC Guide for Mexico: INE/IFE, CURP, RFC, Liveness and AML Controls
      Product Guide

      CySEC Forex KYC Compliance Handbook 2026 | Shufti

      CySEC Forex KYC Compliance Handbook 2026 | Shufti
      Product Guide

      Singapore KYC & AML Compliance Guide 2026 | Shufti

      Singapore KYC & AML Compliance Guide 2026 | Shufti
      Product Guide

      Mexico 2026 KYC Handbook to Improve First Pass Rate

      Mexico 2026 KYC Handbook to Improve First Pass Rate
      Product Guide

      Where Can Identity Data Legally Live? 2026 Guide | Shufti

      Where Can Identity Data Legally Live? 2026 Guide | Shufti
      Product Guide

      Shufti Deepfake Fraud Index Report: Deepfake Fraud Set to Surge 495% in 2026

      Shufti Deepfake Fraud Index Report: Deepfake Fraud Set to Surge 495% in 2026
      Whitepaper

      KYC Compliance and Identity Fraud Challenge Across APAC

      KYC Compliance and Identity Fraud Challenge Across APAC
      Product Guide

      Brazil Bets KYC Playbook for .bet.br Operators 2026 | Shufti

      Brazil Bets KYC Playbook for .bet.br Operators 2026 | Shufti
      Product Guide

      Malta iGaming KYC & AML Readiness Guide 2026| Shufti

      Malta iGaming KYC & AML Readiness Guide 2026| Shufti
      Product Guide

      Brazil 2026 KYC Playbook to Improve First Pass Rate

      Brazil 2026 KYC Playbook to Improve First Pass Rate
      Product Guide

      Malta 2026 KYC Playbook to Improve First Pass Rate

      Malta 2026 KYC Playbook to Improve First Pass Rate
      Whitepaper

      The Deepfake Detection Gap

      The Deepfake Detection Gap
      Product Guide

      Choosing the Right Identity Verification Vendor for the Forex Sector

      Choosing the Right Identity Verification Vendor for the Forex Sector
      Product Guide

      A Comprehensive Guide to Address Verification in Complex Markets

      A Comprehensive Guide To Address Verification In Complex M
      Whitepaper

      Beyond Benchmark Accuracy: Making Deepfake Detection Work for IDV Systems

      Beyond Benchmark Accuracy: Making Deepfake Detection Work for IDV Systems
      Product Guide

      Human – Assisted Video KYC for Regulated Businesses:

      Human – Assisted Video KYC for Regulated Businesses:
      Whitepaper

      Re-Thinking RegTech for KYC Compliance

      Re-Thinking RegTech for KYC Compliance
      Product Guide

      Enterprise Guide to Choose Right Identity Verification Solution

      Enterprise Guide to Choose Right Identity Verification Solution
      report

      Global Age-Verification Laws 2025 Snapshot

      Global Age-Verification Laws 2025 Snapshot
      Whitepaper

      The Backbone of Global Trust

      The Backbone of Global Trust
      report

      State of Global AML Compliance 2025

      State of Global AML Compliance 2025
      Product Guide

      Strategic ID Verification Vendor for Crypto Industry

      Strategic ID Verification Vendor for Crypto Industry
      report

      Market Positioning and Commercial Assessment Results Presentation

      Market Positioning and Commercial Assessment Results Presentation
      Whitepaper

      Preventing Account Takeover Fraud with Multilayered Defense

      Preventing Account Takeover Fraud with Multilayered Defense
      Whitepaper

      The Critical 1% Closing Systemic Gaps In Global Identity Verification

      The Critical 1% Closing Systemic Gaps In Global Identity Verification
      Whitepaper

      Outsmarting the Deepfake Threat to Identity Trust

      Outsmarting the Deepfake Threat to Identity Trust
      Product Guide

      Scale Without Borders

      Scale Without Borders
      report

      Streamlining Identity Verification: How Shufti Secure Capture Enhances Accuracy and Trust

      Streamlining Identity Verification: How Shufti Secure Capture Enhances Accuracy and Trust
      report

      Top 10 Most Difficult Countries for Identity Verification

      Top 10 Most Difficult Countries for Identity Verification
      Whitepaper

      Shufti’s iGaming White Paper 2023

      Shufti’s iGaming White Paper 2023
      report

      Shufti Identity Fraud Report 2022

      Shufti Identity Fraud Report 2022
      report

      Shufti Fraud Report 2021

      Shufti Fraud Report 2021
      report

      Holiday Season – The Prime Time for ID Thieves and Financial Criminals

      Holiday Season – The Prime Time for ID Thieves and Financial Criminals
      report

      Shufti Completes 4 Years of Fighting ID Fraud

      Shufti Completes 4 Years of Fighting ID Fraud
      Product Guide

      On-premises Identity Verification for the Banking Sector

      On-premises Identity Verification for the Banking Sector
      Whitepaper

      Shrinking the Space for Travel Industry Scams with Biometric Verification

      Shrinking the Space for Travel Industry Scams with Biometric Verification
      Product Guide

      Global Gambling Compliance: Regulations, Age Checks & Financial Safety

      Global Gambling Compliance: Regulations, Age Checks & Financial Safety
      report

      A comprehensive guide to KYC and AML compliance in Canada

      A comprehensive guide to KYC and AML compliance in Canada
      n-img-roi-cross

      Form submitted successfully!

      Thank you for your interest — your report is loading now.

      Take the next steps to better security.

      Contact us

      Get in touch with our experts. We'll help you find the perfect solution for your compliance and security needs.

      Contact us

      Get the Shufti newsletter

      Stay ahead of the curve with fresh takes on the latest identity innovations.

        Take the next steps to better security.

        Contact us

        Get in touch with our experts. We'll help you find the perfect solution for your compliance and security needs.

        Contact us

        Request demo

        Get free access to our platform and try our products today.

        Get started

        Pitch a piece and get a verified byline in the Media room.
        Partnership Inquiries?
        Email us at [email protected]

        iBeta Level 1 — ISO 30107-3 Compliant iBeta Level 2 — ISO 30107-3 Compliant iBeta Level 3 — ISO 30107-3 Compliant PCI DSS SOC 2 Type 2 GDPR GDPR Fundamentals — Quality Guild ISO 27001:2022 KJM Age Verification CCPA / CPRA Cyber Essentials Cyber Essentials Plus
        Copyright © 2026 Shufti. All rights reserved.