

 AMLR Solutions
 AMLR Consultation
 EUDI Wallet
 Onboarding
 Ongoing Monitoring
 FRAML
 KYC
 KYB
 KYI
 Age Assurance
 Workforce IAM
 Candidate Verification
 Account Takeover
 Bonus/ Promotion Abuse
 Chargeback Fraud
 Deepfake
 Document Fraud
 Fraud Networks
 Impersonation Fraud
 Money Mule Activity
 Multi-Accounting
 Party Fraud
 Regulatory & Compliance Risks
 Synthetic Identity Fraud
 Adult Content
 Banking
 Crypto
 Fintech
 Forex
 Compliance
 Fraud prevention
 Trust & safety
 Global expansion
 Compliance Officers
 Developers
 Fraud Analysts
 Product Managers
 Journey Builder
 Global Trust Platform
 Customer Profiles
 Vendor Comparison
 IDV Case Management
 AML Case Management
 Regulatory Reporting
 Agentic Rule Builder
 AI Compliance Co-Pilot
 Fraud Analytics
 Fraud Hub
 OCR
 Shufti AI
 Bank Account Verification
 Biometric Duplication
 Database Checks
 Document Intelligence
 Government ID
 Mobile Driver's License
 NFC
 Selfie Liveness
 Brand Personalisation
 Deployment Options
 Identity Methods
 IDV Modes
 Multi-tenancy
 On-Premise IDV
 Secure Capture
 Shufti MCP


- Afghanistan
- Albania
- Algeria
- Angola
- Argentina
- Armenia
- Australia
- Austria
- Azerbaijan
- Bahrain
- Bangladesh
- Belarus
- Belgium
- Bolivia
- Bosnia and Herzegovina
- Brazil
- Bulgaria
- Cambodia
- Cameroon
- Canada
- Chile
- China
- Colombia
- Costa Rica
- Croatia
- Cyprus
- Czech Republic
- Denmark
- Dominican Republic
- Ecuador
- Egypt
- El Salvador
- Estonia
- Eswatini
- Ethiopia
- Finland
- France
- Germany
- Greece
- Haiti
- Hong Kong
- Hungary
- India
- Iraq
- Ireland
- Indonesia
- Italy
- Japan
- Jordan
- Kazakhstan
- Kenya
- Kosovo
- Kuwait
- Latvia
- Lithuania
- Luxembourg
- Malaysia
- Malta
- Mauritius
- Mexico
- Micronesia
- Moldova
- Mongolia
- Montenegro
- Morocco
- Mozambique
- Myanmar
- Namibia
- Nauru
- Nepal
- Nigeria
- Nicaragua
- Niue
- Norway
- Netherlands
- New Zealand
- Oman
- Pakistan
- Palau
- Palestine
- Panama
- Papua New Guinea
- Paraguay
- Peru
- Puerto Rico
- Philippines
- Portugal
- Poland
- Qatar
- Republic of Congo
- Romania
- Russia
- Rwanda
- Samoa
- San Marino
- Saudi Arabia
- Senegal
- Serbia
- Seychelles
- Sierra Leone
- Singapore
- Slovakia
- Slovenia
- Somalia
- South Africa
- South Korea
- South Sudan
- Spain
- Sri Lanka
- St Kitts and Nevis
- St Maarten
- St Lucia
- Sweden
- Switzerland `
- Syria
- Taiwan
- Tajikistan
- Tanzania
- Thailand
- Timor Leste
- Togo
- Tonga
- Trinidad and Tobago
- Turkey
- Turks and Caicos
- Turkmenistan
- Tunisia
- Tuvalu
- UAE
- Uganda
- Ukraine
- UK
- USA
- Vietnam
- Zambia
Scale Identity Verification and KYC Operations in Afghanistan
Verify Afghan customers through e-Tazkira, paper Tazkira and passport checks and 10,000+ foreign ID document types, run KYB on ACBR-registered businesses and their real owners, and monitor transactions and sanctions lists. One platform runs compliance and fraud prevention across the full customer lifecycle for DAB-supervised firms.
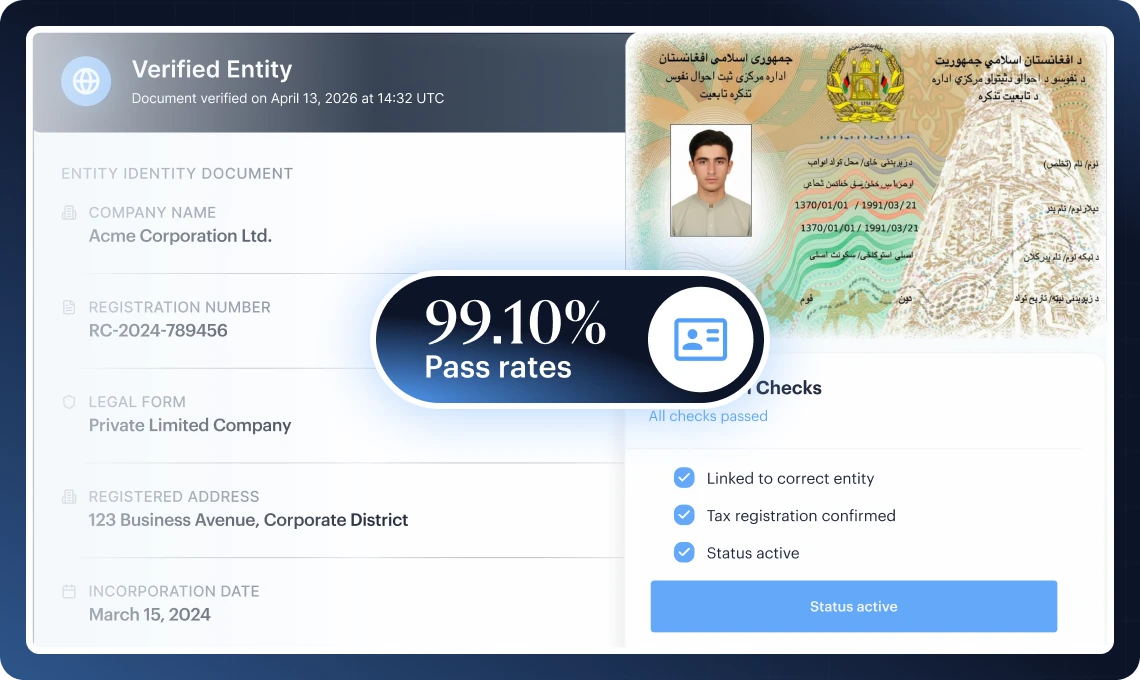




Operational Performance for Afghanistan KYC
Our Numbers Speak Volumes
99.10%
Pass
Rates
Under 5 secs
IDV
Verification
100%
Omni-format
Document Recognition
Afghanistan IDV/KYC Challenges
DAB's KYC Rules Change With the Amount at Stake
KYC verification in Afghanistan scales with the money involved. DAB's 2021 KYC Regulation adds documents at each band, from a name and address below AFN 250,000 up to beneficial owner details above AFN 3,000,000. Shufti's AI Journey Builder applies each band's checks automatically.
Paper and Electronic Tazkiras Circulate Side by Side
Customers hold handwritten paper Tazkiras alongside the e-Tazkira, and the two formats carry different security features. A check built for one misses forgeries in the other. Shufti reads both, runs forensic checks suited to each and routes paper-only holders to a second check.
Owners Above 10% Must Be Traced Through Company Records
DAB requires firms to identify everyone who owns or controls more than 10% of a company, and that picture is usually built from Articles of Association and shareholder records rather than a searchable public register. Shufti reads those records and ties each owner to a verified identity.
Thin Case Files Weaken FinTRACA Reports
The AML Law gives firms three days to report a suspicion to FinTRACA, and DAB expects STR copies to be kept for ten years. Thin files slow the first and weaken the second. Shufti's case management packages every check, hit and analyst note into report-ready bundles.
Documents and Languages
Individual Documents Shufti Verifies in Afghanistan
Shufti verifies 8+ Afghan identity documents plus passports and ID cards from other countries. The cards below cover the core documents Afghan onboarding relies on, with the full list on the supported documents page.
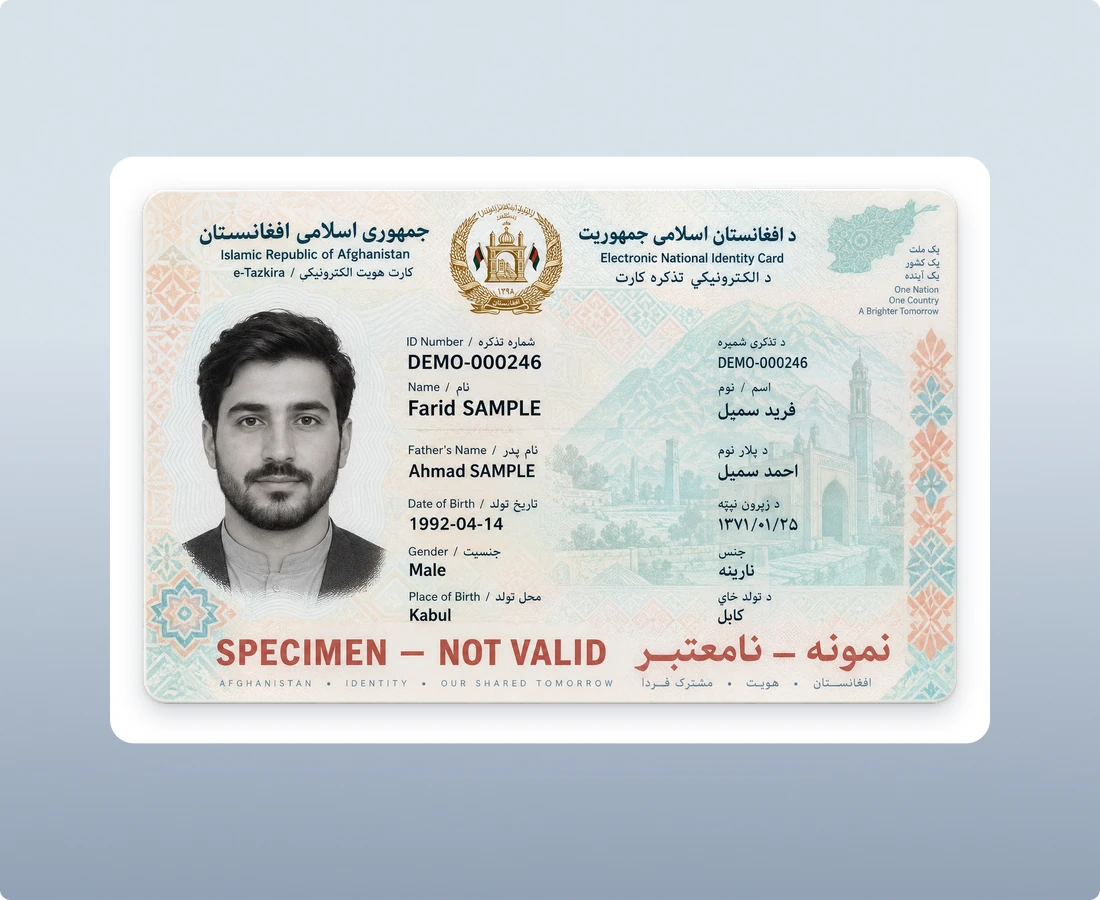
View All Supported DocumentsElectronic Tazkira (e-Tazkira)
Issued by the National Statistics and Information Authority (NSIA), which captures fingerprints, iris scans and a photo at enrolment. Shufti reads the card's Dari, Pashto and English fields, checks print, layout and photo for tampering and matches the card photo to a liveness-checked selfie.
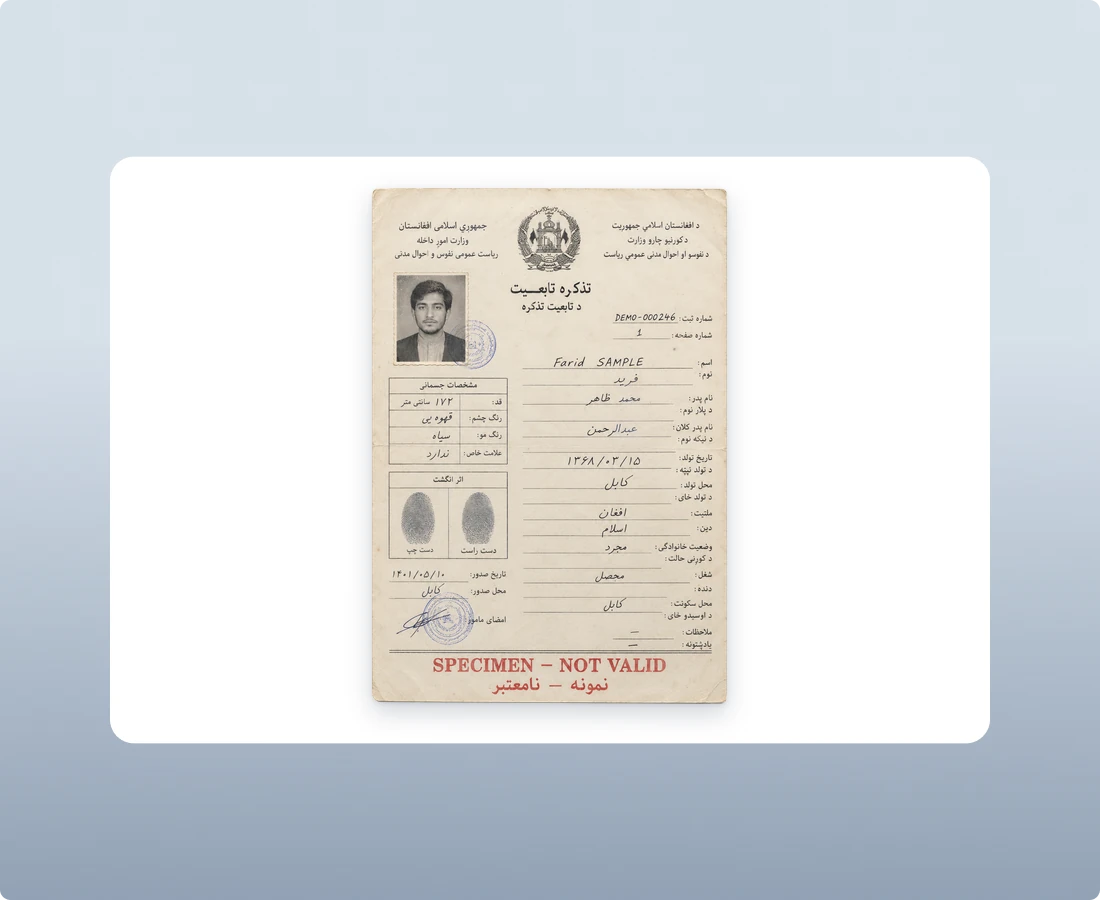
Paper Tazkira
The older handwritten Tazkira carries no printed security features but remains in use, and the passport office accepts it once NSIA's Population Registration Directorate confirms it. Shufti extracts its details, flags edits and routes the holder to a passport or video check.
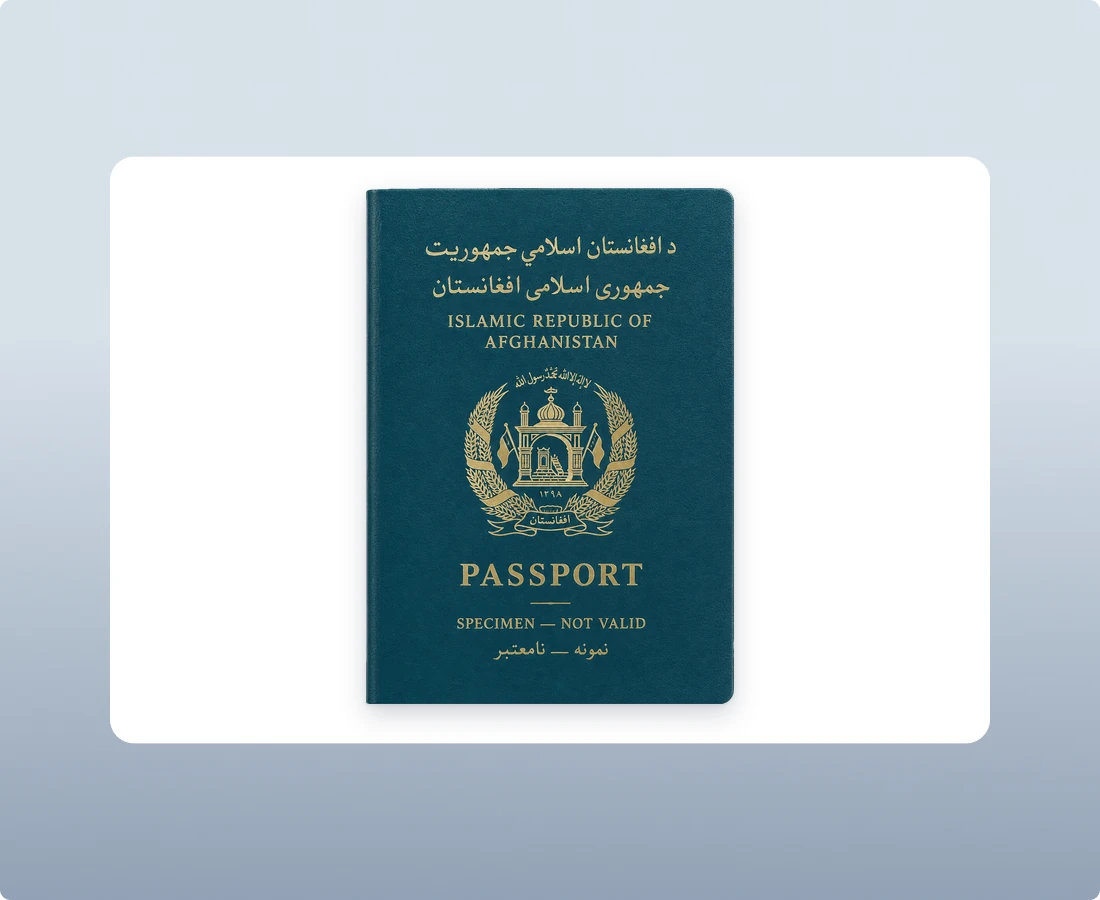
Afghan Passport
Issued by the Ministry of Interior's General Directorate of Passports with a machine-readable zone. Shufti runs nine forensic detection layers, from MRZ checksum validation to hologram analysis, so a cloned or altered passport fails before onboarding.
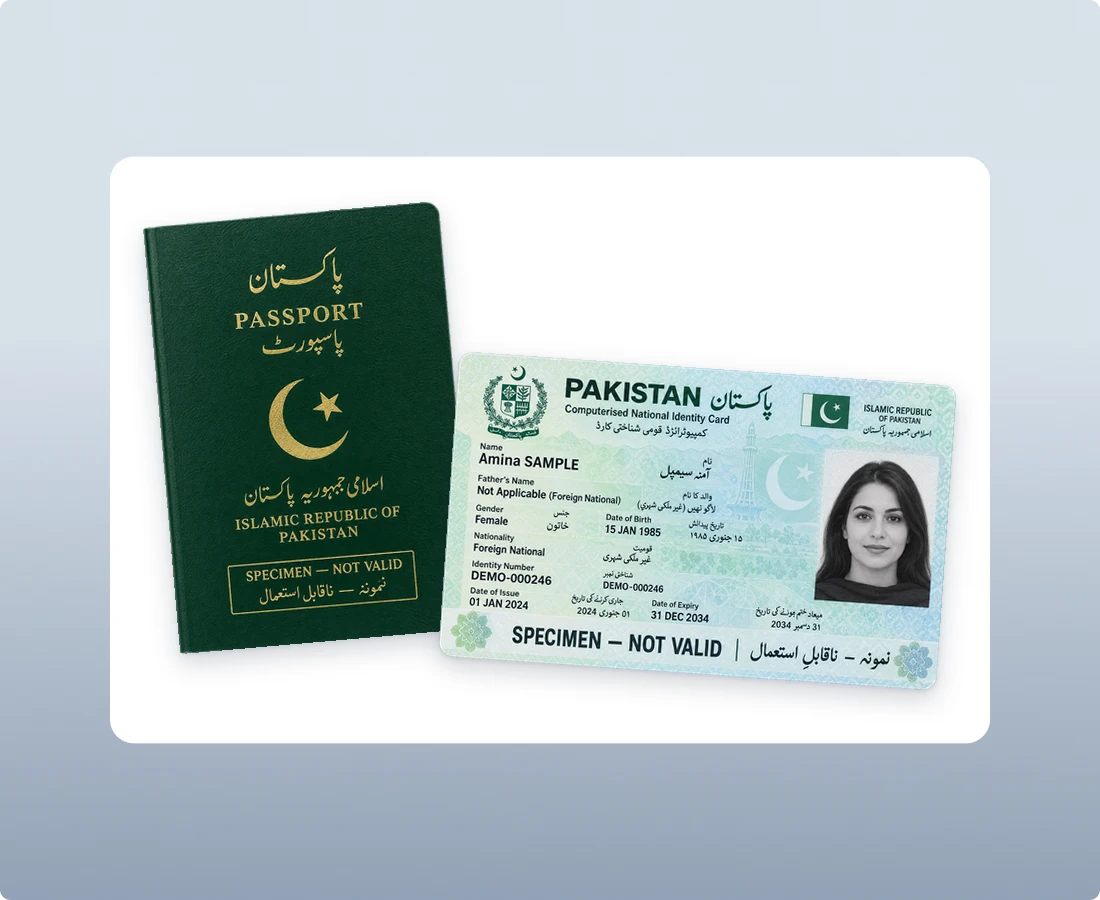
Foreign Passports and National ID Cards
Shufti actively processes 10,000+ ID document types from 240+ countries and territories, and its zero-shot AI learns new document formats in minutes. Aid workers, contractors, foreign investors and Afghans holding foreign papers onboard on the same platform as resident customers.
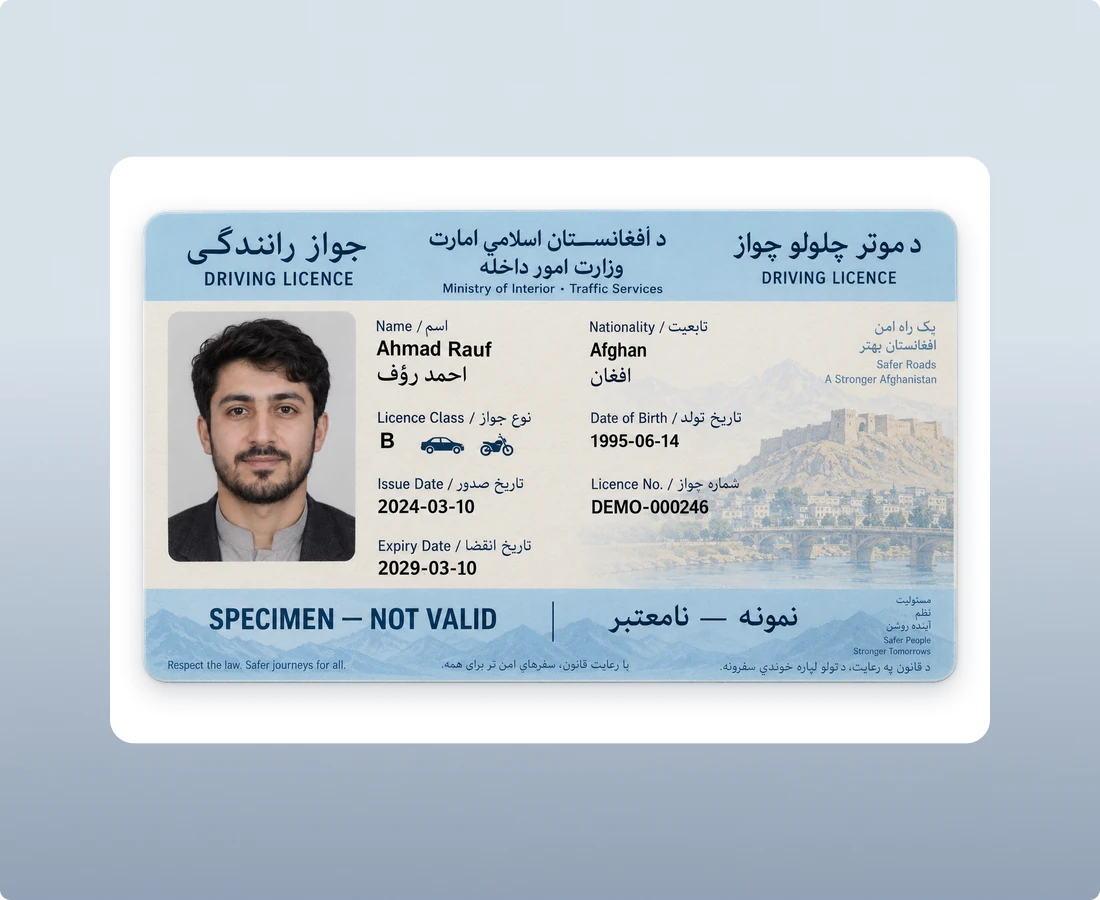
Afghan Driving License
Issued through the Ministry of Interior's traffic services. Shufti checks the licence's authenticity, expiry date and photo against a live selfie, giving firms a second photo ID when a customer's Tazkira needs corroboration or a driver must be verified.
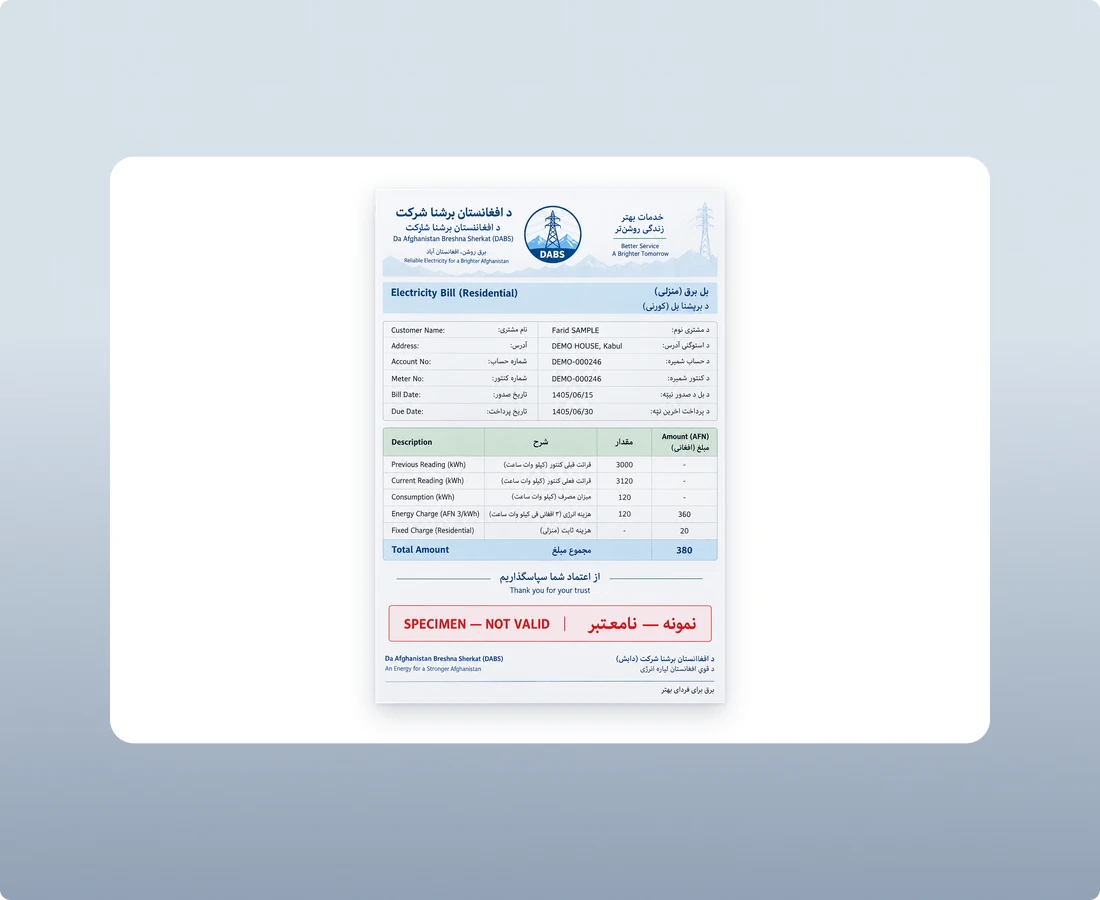
Proof of Address
Electricity bills from Da Afghanistan Breshna Sherkat, telecom bills, bank statements and lease agreements, read together with the six-digit postcode where one appears. Shufti verifies the address in the same step as the ID, since DAB's KYC Regulation asks for an address at every tier.
Entity Identity
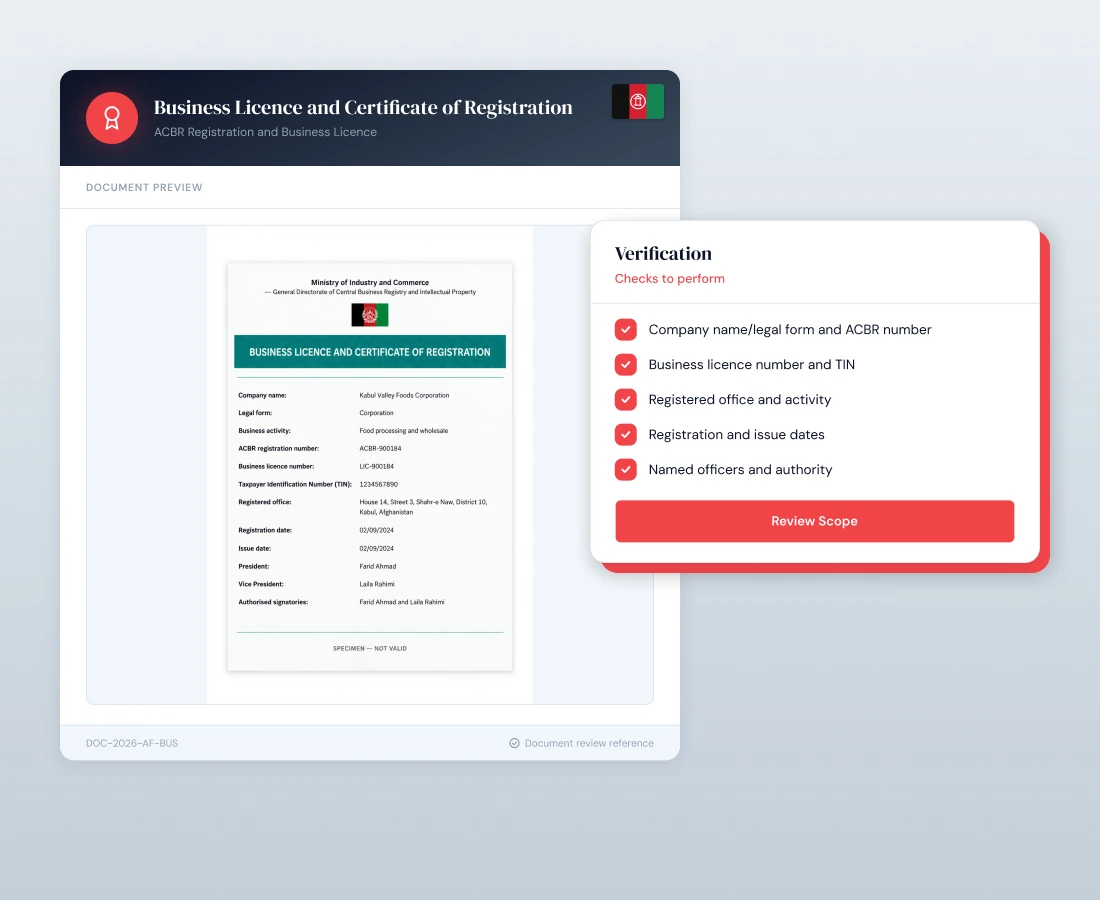
Business Licence and Certificate of Registration
Issued through the Afghanistan Central Business Registry (ACBR) at the Ministry of Industry and Commerce, and required by DAB for business accounts above AFN 250,000. Shufti reads the registration, TIN and licence numbers and checks the documents for tampering against registry records.
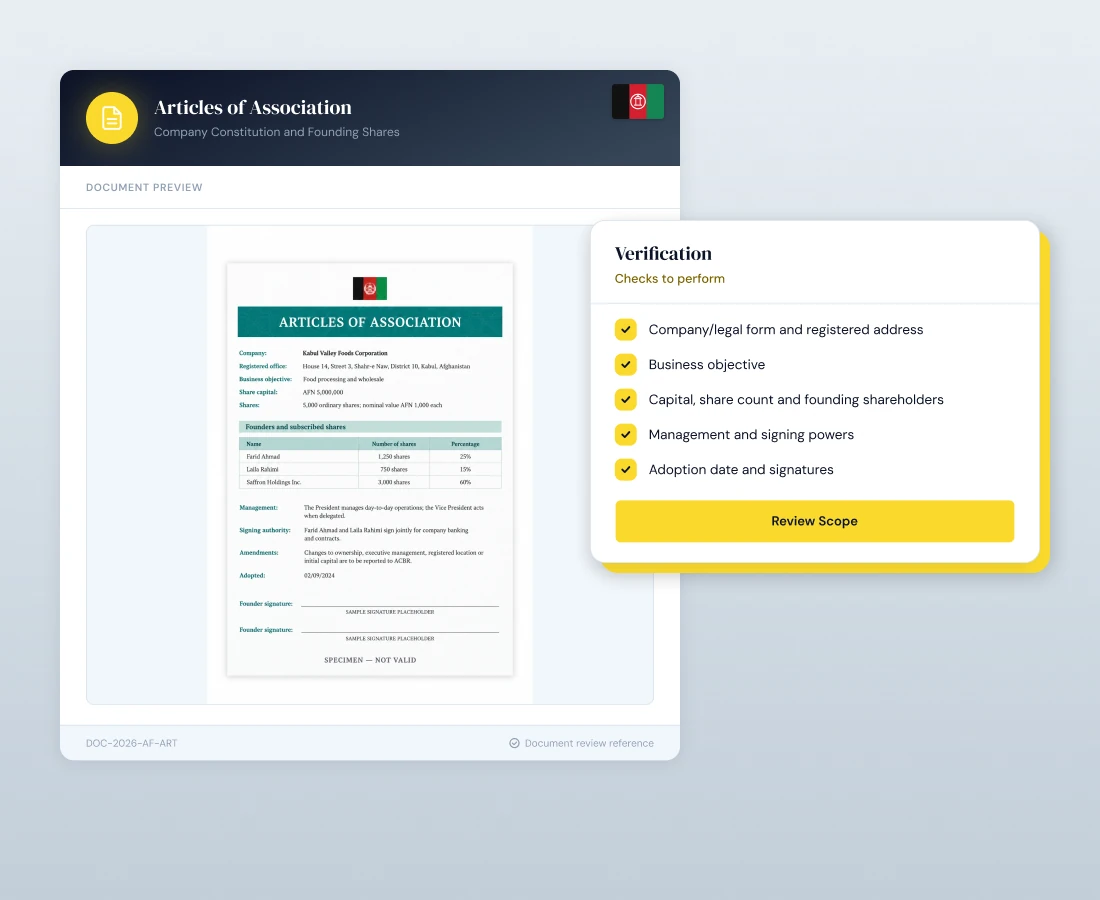
Articles of Association
Filed with the registry at incorporation and required by DAB once a business relationship passes AFN 3,000,000. Shufti's AI-OCR reads ownership, capital and signing authority from Dari, Pashto or English pages and flags GAN-generated or edited pages.
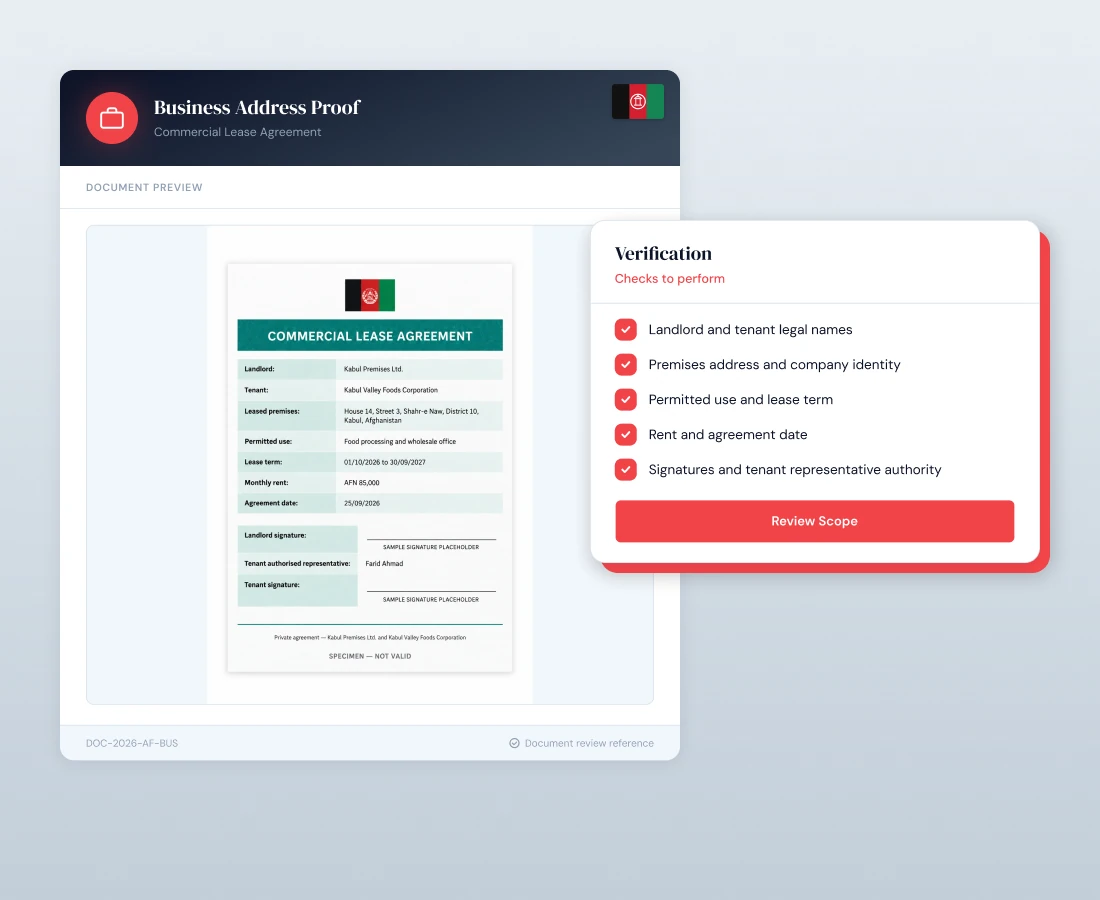
Business Address Proof
The business location recorded at ACBR registration. Shufti cross-checks it against lease agreements, utility bills and the business licence, so the address on file agrees across every document a company submits.
Tax Identity
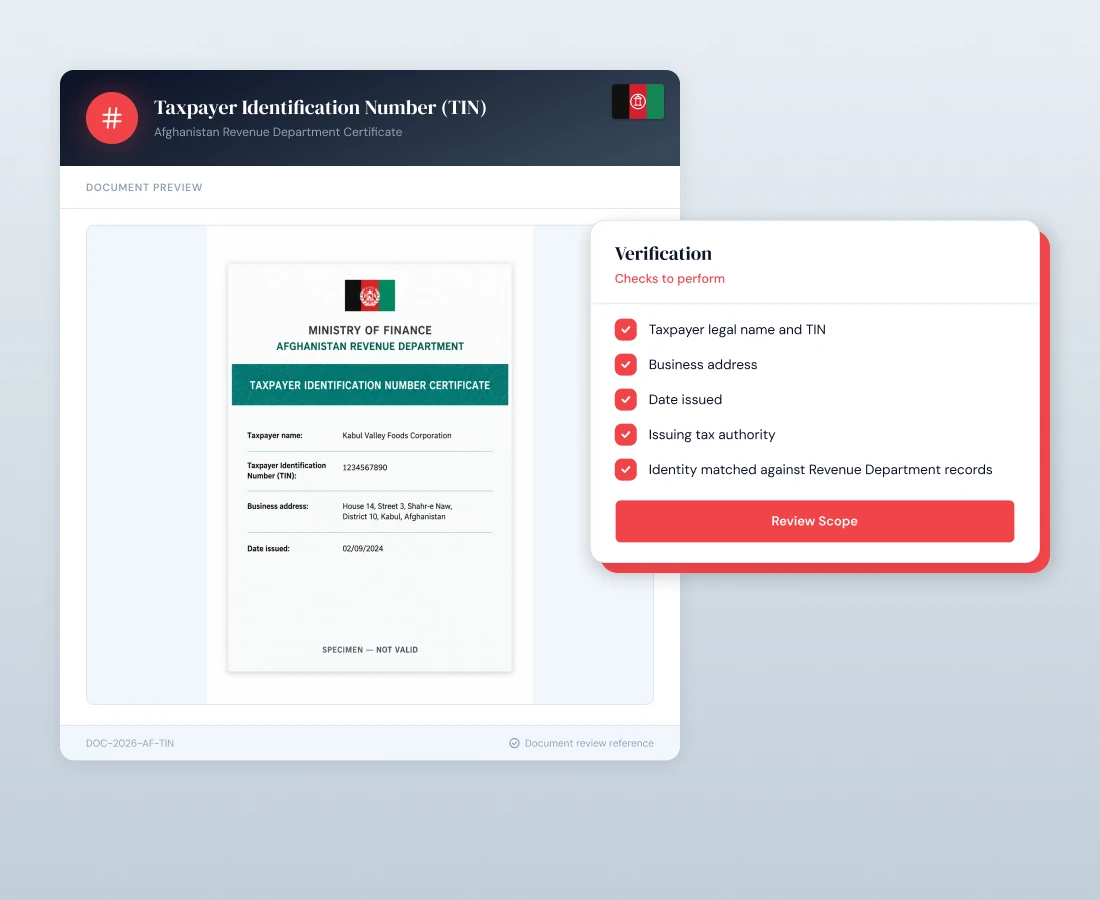
Taxpayer Identification Number (TIN)
A unique 10-digit number issued by the Afghanistan Revenue Department under Article 86 of the Income Tax Law 2009, which bank account holders must hold. Shufti extracts the TIN and cross-checks it against the business licence and registration record.
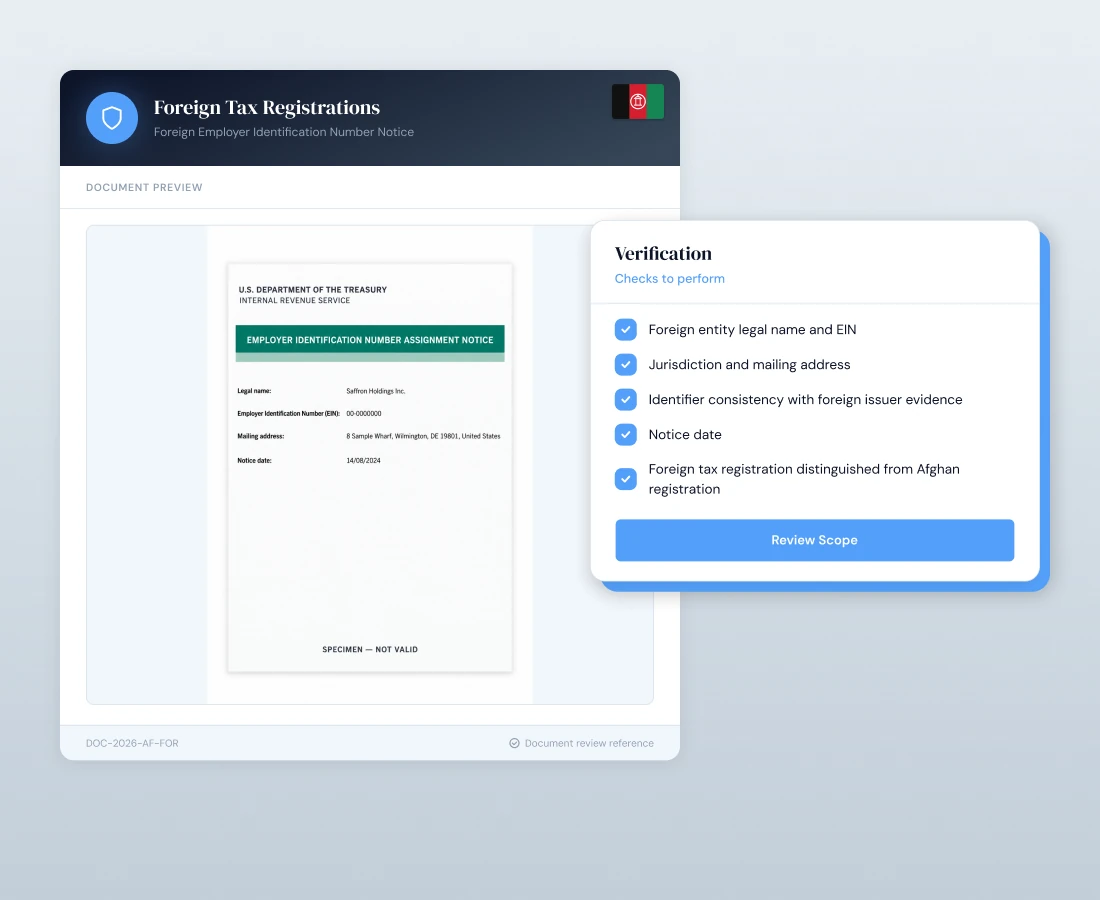
Foreign Tax Registrations
Non-resident shareholders and branches of foreign companies present tax numbers issued outside Afghanistan. Shufti reads those registrations alongside the Afghan TIN and links each one to the right legal entity in the ownership record.
Ownership and Control
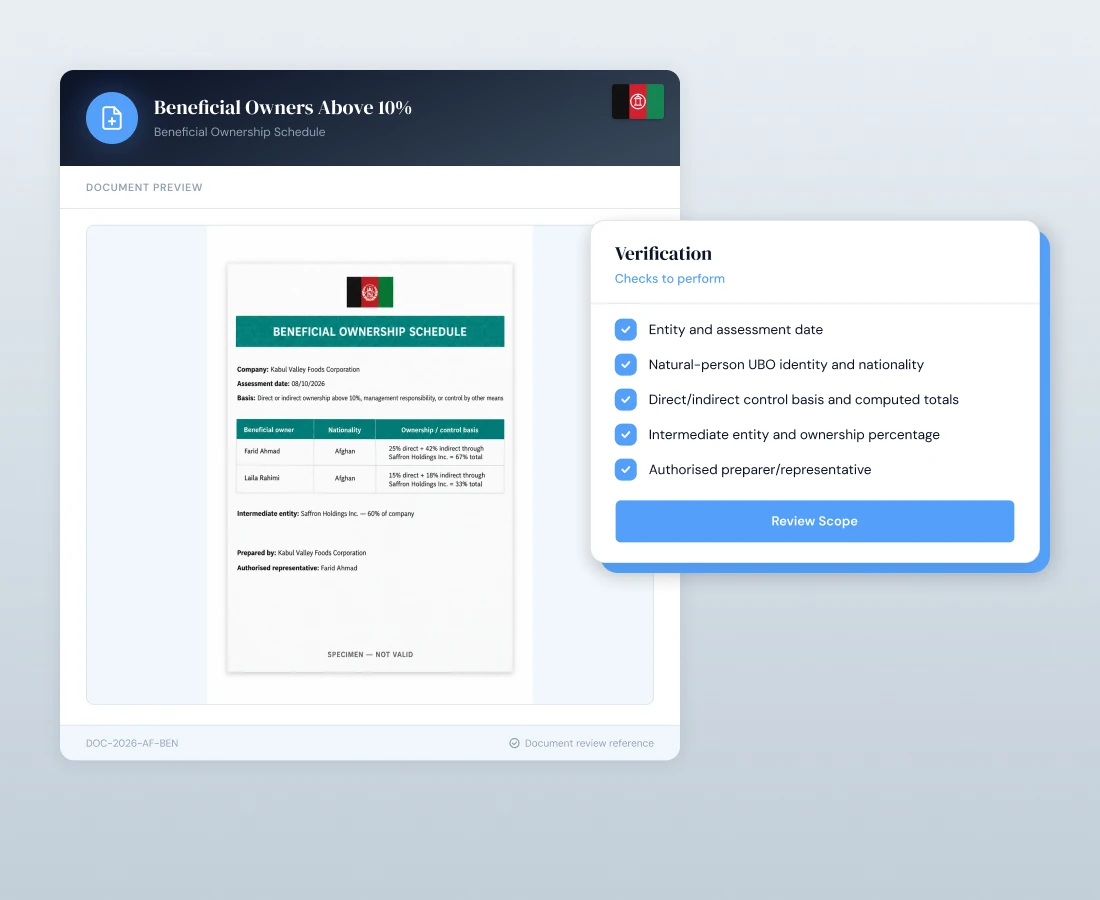
Beneficial Owners Above 10%
The DAB test covers ownership, management and control by other means, not shareholding alone. Shufti extracts each qualifying person from company records, verifies their Tazkira or passport and screens them for sanctions and PEP exposure before the account opens.
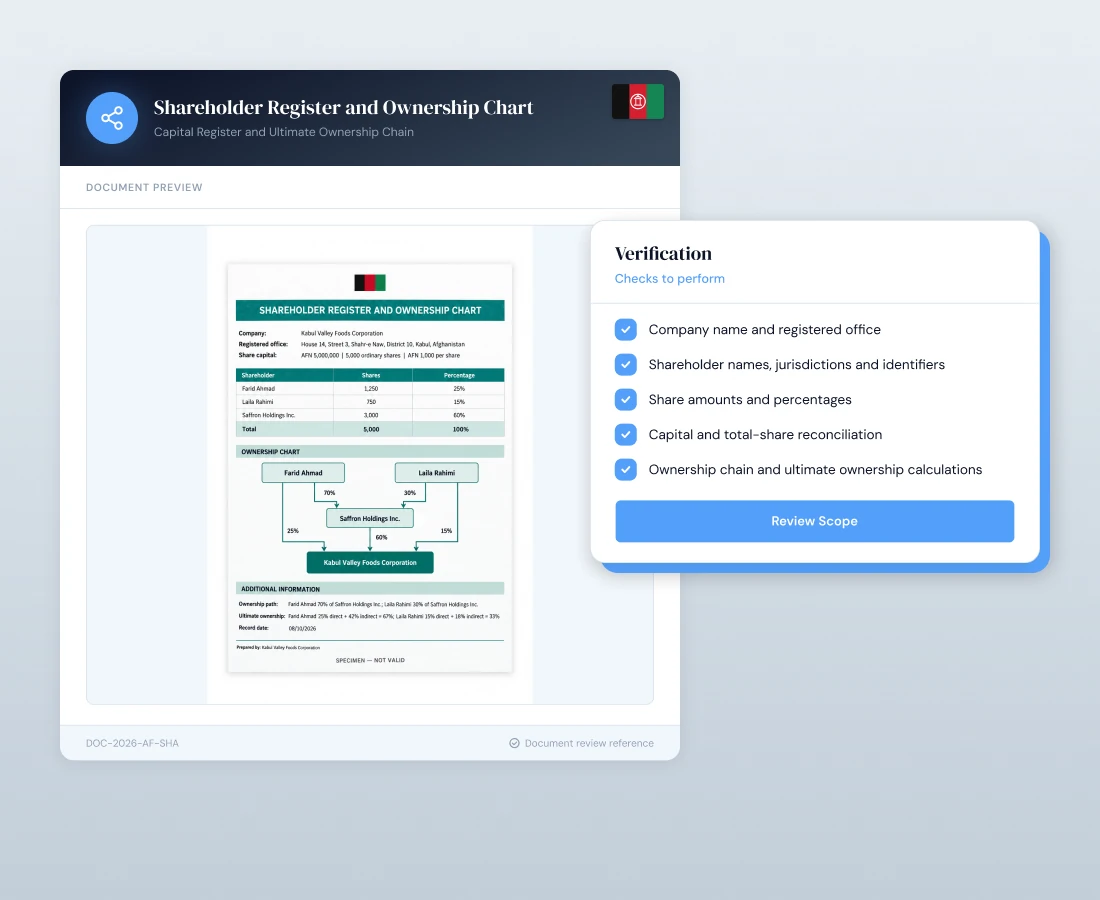
Shareholder Register and Ownership Chart
Shufti maps ownership through intermediate companies to the natural person in control and screens each layer, so a holding company registered abroad cannot hide who stands behind an Afghan subsidiary or branch.
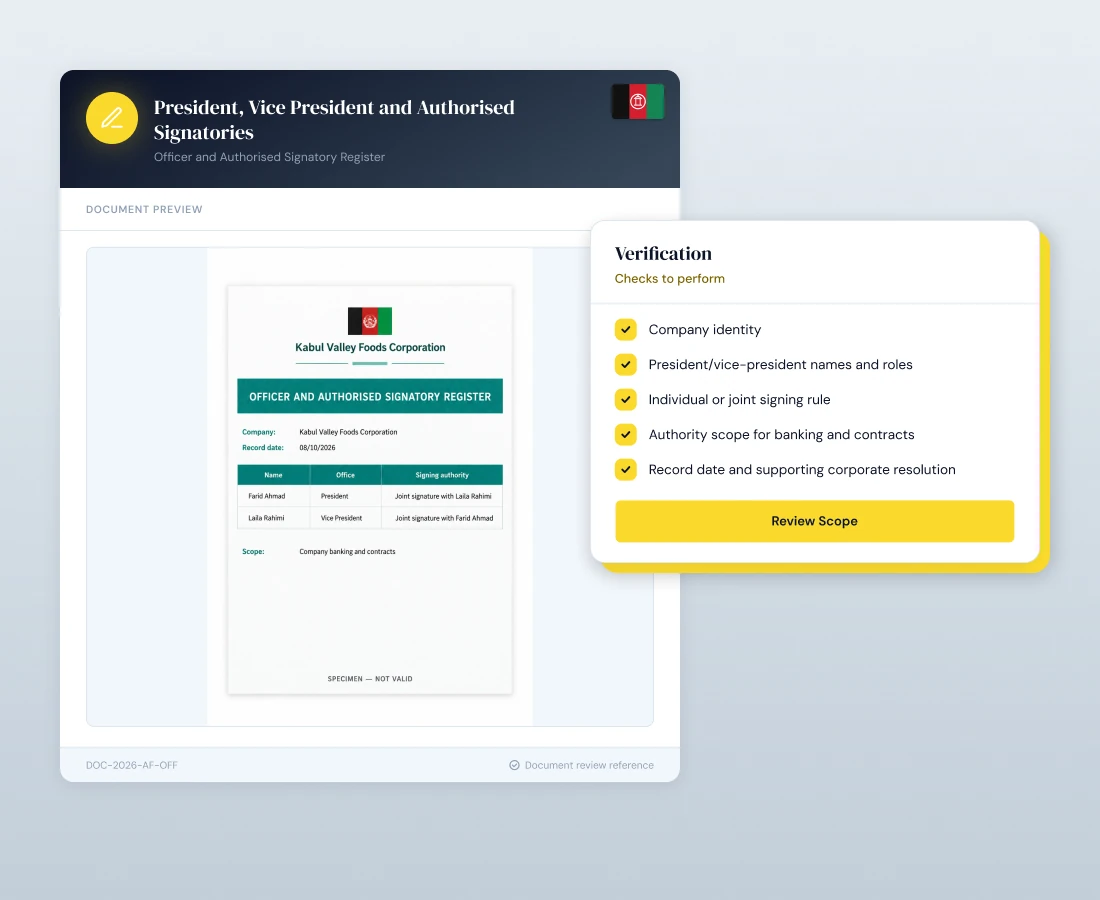
President, Vice President and Authorised Signatories
Shufti verifies the identity document of each officer named at registration and each signatory on the account, screens them for sanctions and PEP exposure and raises an alert when a new officer appears in updated records.
Languages We Cover
Dari, Pashto and English Document Parsing
Afghan IDs and passports carry Dari, Pashto and English text in Perso-Arabic and Latin script. Shufti's OCR reads 150+ languages and scripts at 99.7% accuracy and averages 93% accuracy against Google Vision's 78.4% in its published benchmark. Zero-shot document intelligence extracts data from layouts it has never seen, on first sight, without waiting for a template.
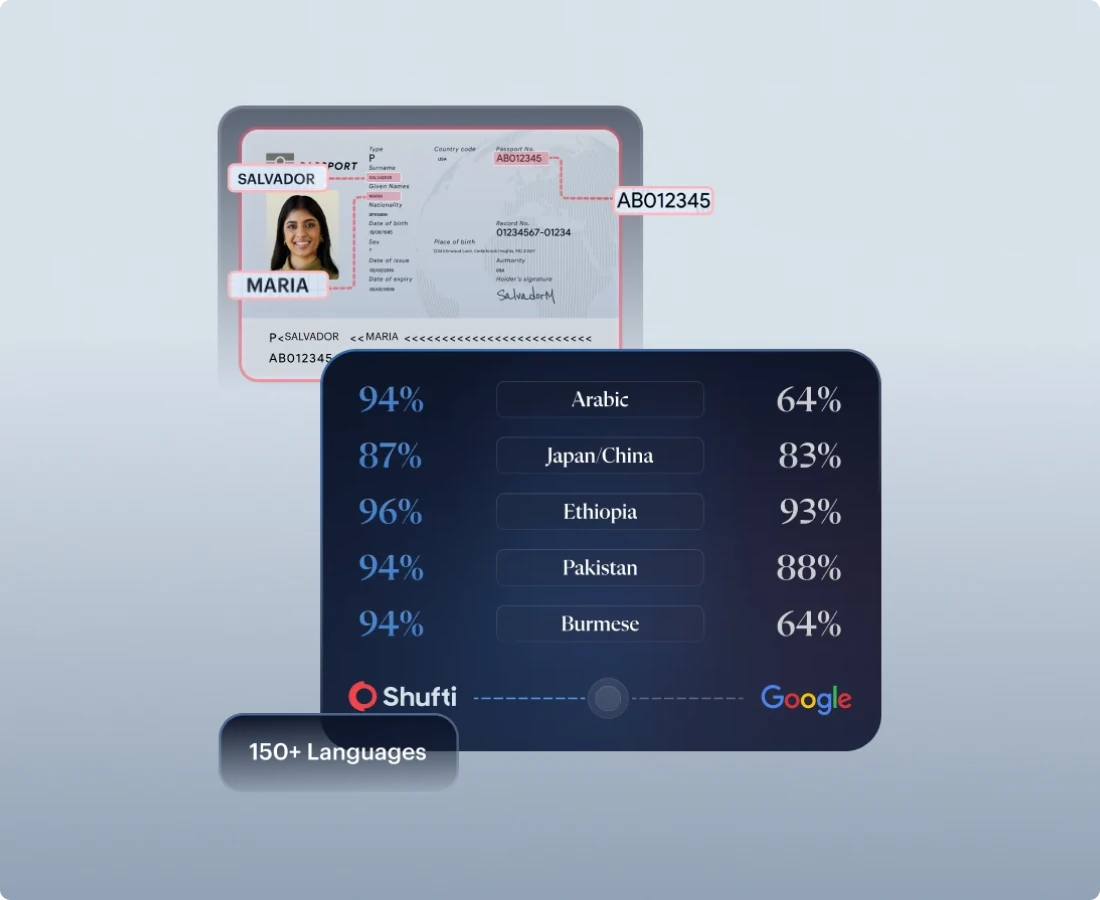
Afghan Name Matching
The Tazkira records a person's name with their father's and grandfather's names, and spellings shift between Dari, Pashto and English. Shufti's phonetic and transliteration rules match those variants in sanctions and PEP screening.
Cross-Document Consistency Checks
Names, fathers' names, dates of birth and ID numbers are reconciled across the Tazkira, passport, driving licence, business licence and Articles of Association, so a mismatch between records is flagged before an analyst has to find it.
Independent Validation
Shufti's Recognition Across Independent Evaluations
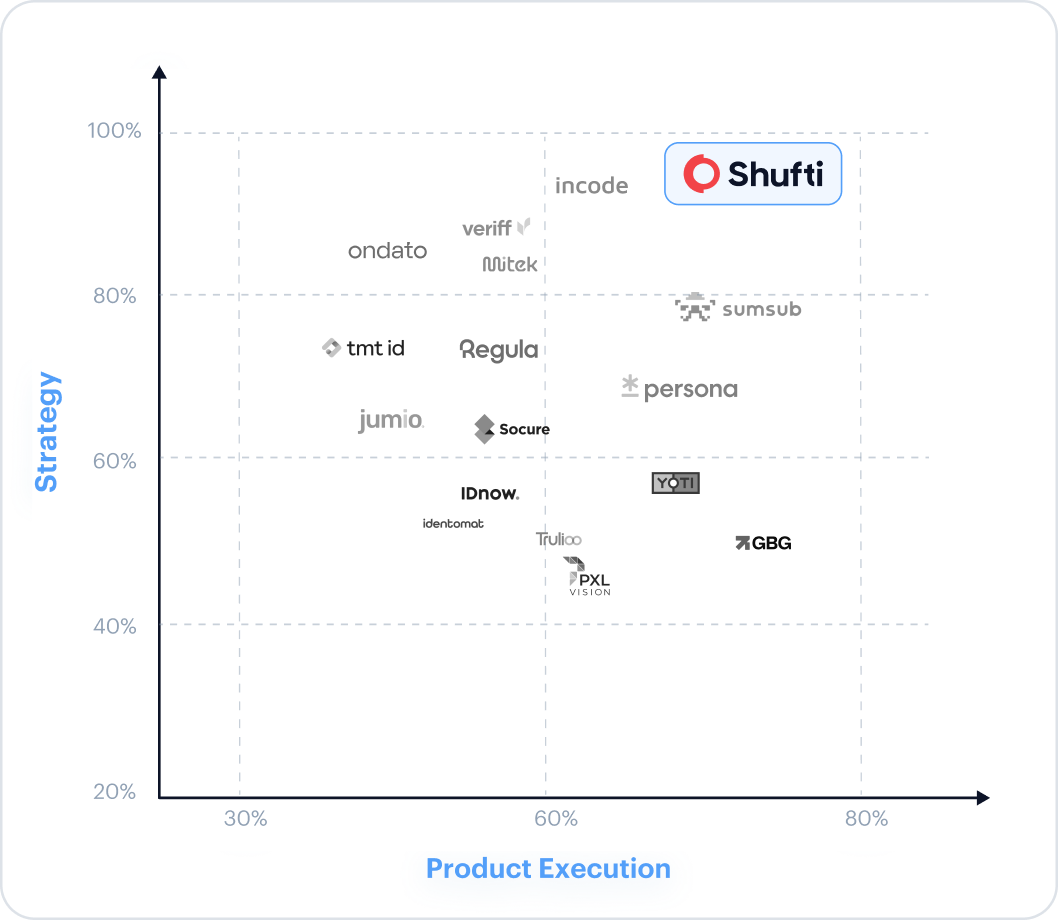
Ranked Exceptional in the Liminal Index 2026 for age estimation
View Report
Differentiated by Gartner on document diversity and country coverage
Read more
Certified at iBeta Level 3 PAD with 0% APCER
Read Blog
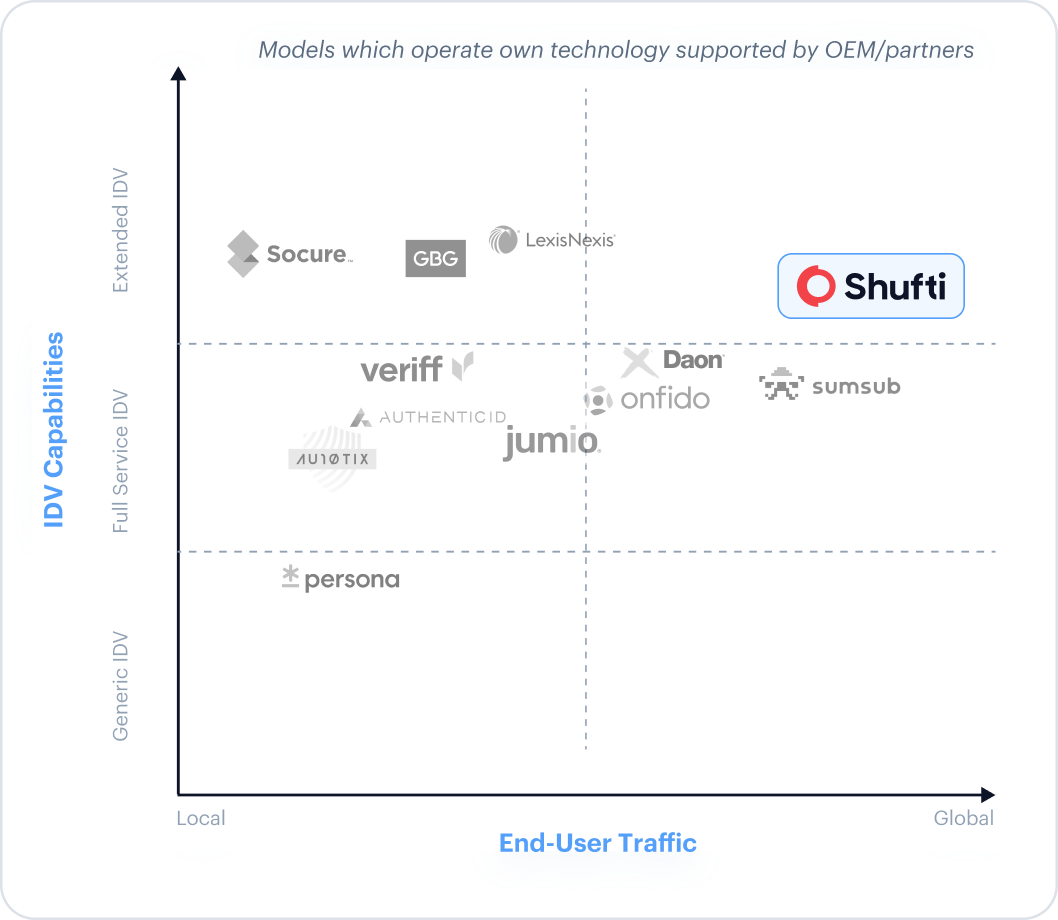
Broadest global reach in the 2025 KuppingerCole Extended IDV report
Download Report
Ranked Top 5 in the DHS RIVR 2025 for identity validation
Read Blog
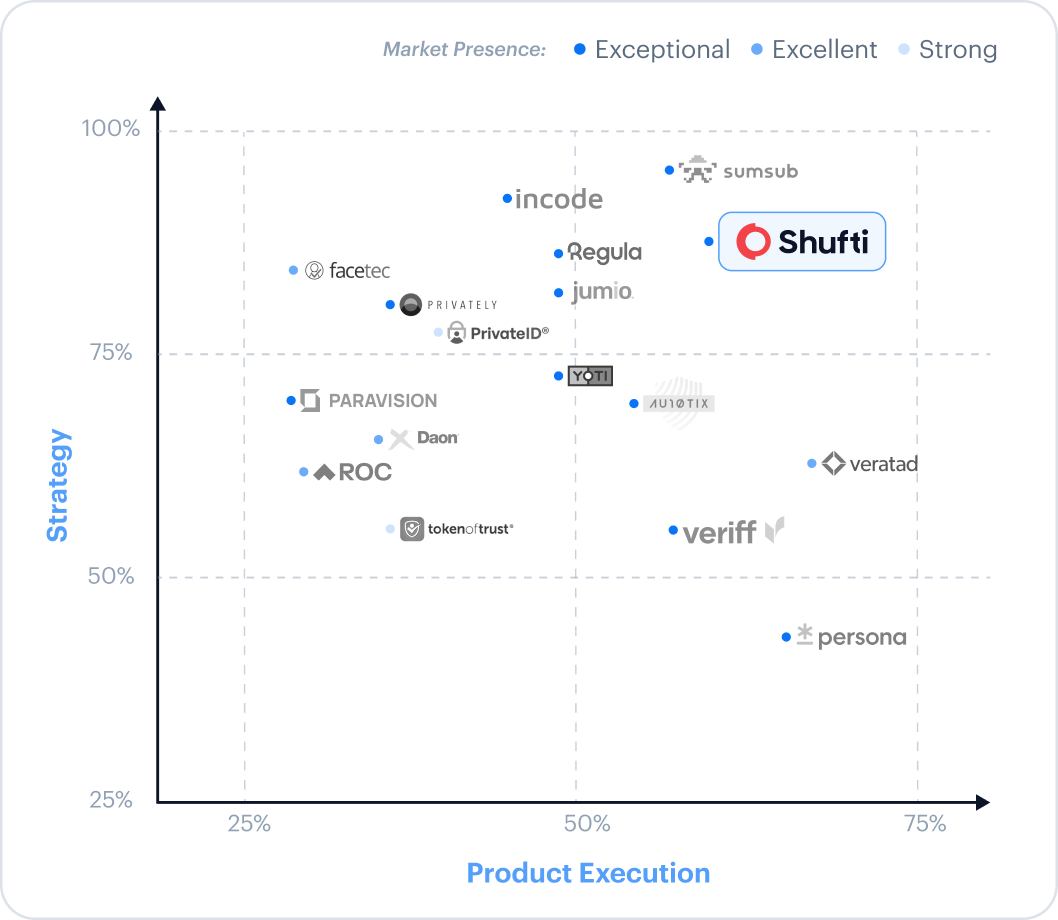
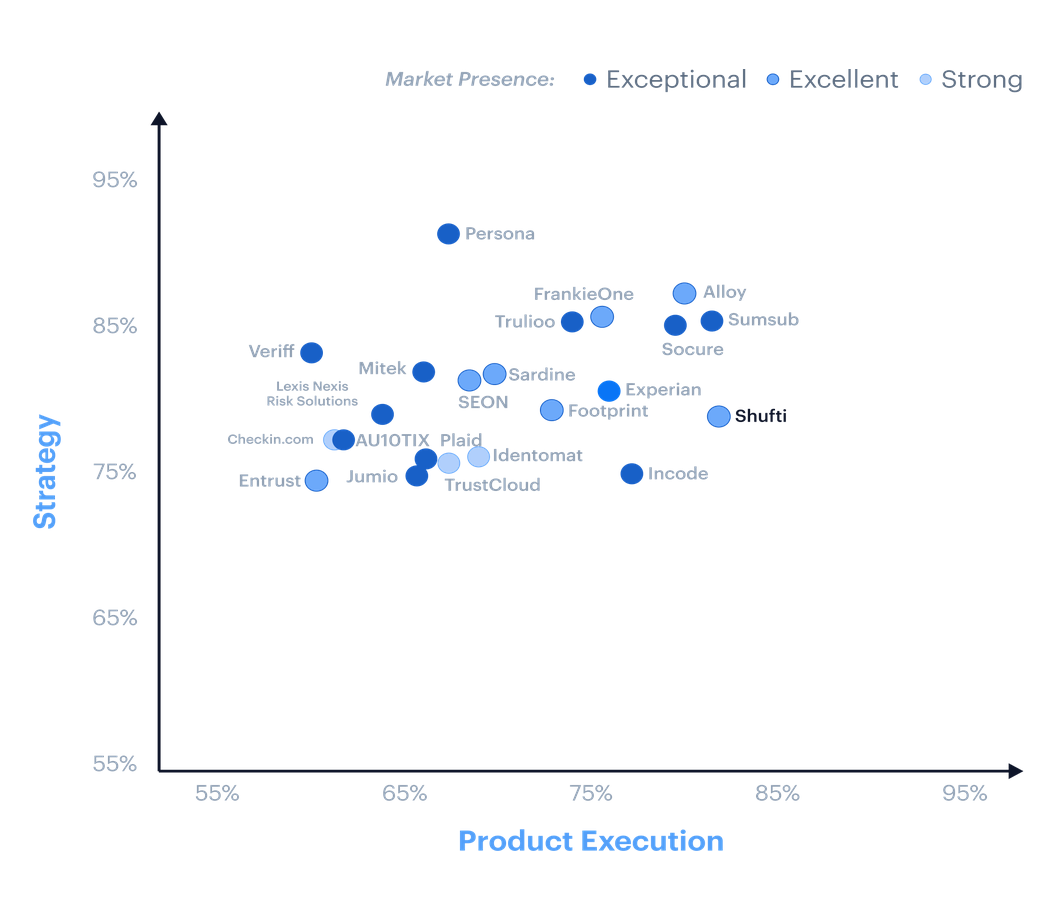
Top Vendor for Product Execution in the Liminal Index for KYC 2026
View Report
Ranked Exceptional for age verification by Liminal Index 2026
View Report
Recognised as a Leader in G2 Fall 2026 reports
Read More
Regulatory Update
Every Verification Route Afghan Firms Rely On, in One Platform
Online ID verification in Afghanistan rests on Article 12 of the AML Law, which accepts an original national identity card or passport and requires specific measures for customers who are not physically present. Shufti supports each route Afghan firms use, plus chip, document and video routes for non-residents and customers without an e-Tazkira.
Document and Face Biometric
LiveThe customer photographs an e-Tazkira, paper Tazkira or passport and takes a selfie, and Shufti matches the two with iBeta Level 3 certified liveness. It is the main remote route for residents and most non-residents.
Tiered Onboarding by Amount
LiveDAB lets e-money institutions apply simplified due diligence up to AFN 200,000, accepting simple identification such as UN IDs and, for women only, non-photo IDs. Shufti captures what each tier allows and steps the customer up as balances grow.
NFC Chip Verification
LiveShufti reads the chip in most foreign biometric passports and checks the issuer's signed data, giving firms a high-assurance route for foreign nationals and Afghans who hold a foreign passport.
Video Identification
LiveAn agent-led video session, run in the language your customers use, verifies the customer and their document live, captures consent and records the full session as evidence for high-risk and enhanced due diligence cases.
Fraud Prevention Across the Afghanistan Customer Journey
Reduce fraud losses and protect customer trust across onboarding, account access, and payments. Shufti connects identity, behavioral, device, network, and transaction intelligence to help Afghanistan businesses act on risk while keeping legitimate customers moving.
Governance & Controls
Audit-Ready Decisions, Lower Operational Drag
Fewer Avoidable Re-submissions
Capture guidance for e-Tazkiras, paper Tazkiras and passports cuts glare, crop and blur rejections, and reads Dari and Pashto text at the first attempt.
Cleaner Audit Trails
Shufti's case management records sources, results, timestamps, evidence, analyst notes and decision history, packaged as report-ready bundles for STR filing with FinTRACA.
One Workflow, One Back Office
Unify KYC, KYB, AML screening and transaction monitoring in one case file, with perpetual KYC/KYB tracking ownership, officer and transaction behavior changes across the lifecycle.
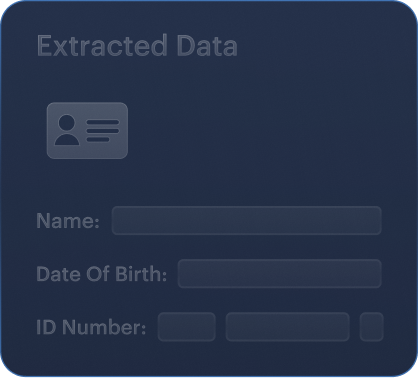
e-Tazkira and Passport-First Flow Design
Residents verify with the e-Tazkira first, paper Tazkira holders step up to a passport or video check, and non-residents start with their passport.
Shufti's IDV/KYC Solutions for Afghanistan
KYC Solutions
Afghan customers range from salaried bank clients and mobile wallet users to microfinance borrowers, aid recipients and foreign residents. One Shufti flow routes each by risk, so nobody faces checks they don't need.
Explore More
Face Verification
Remote wallet sign-ups and agent-assisted onboarding both need proof that the person matches the Tazkira. Shufti matches the selfie to the document photo at a false match rate below 0.001, so impostors fail while genuine customers pass first time.
.
Age Verification
Lenders, telecom operators and online platforms need to confirm a customer is an adult before opening an account. Shufti estimates age from a selfie in under 5 seconds and falls back to the document's date of birth, blocking 99.8% of underage attempts.
.
Bank Account Verification
Salary payments, loan disbursements and aid transfers go astray when the account name differs from the customer. Shufti validates Afghan bank account details and matches the account-holder name in real time, so funds reach the verified customer.
.
Address Verification
Addresses are often written differently across bills, leases and ID records. Shufti's layout-aware extraction and fuzzy matching read local utility bills and statements at a 99.3% pass rate, matching each address to the customer's ID and application.
.
Document Verification
Forged and altered IDs remain a common entry point for fraud, so ID verification in Afghanistan starts with the document itself. Shufti checks Tazkiras, passports and licences within seconds, flagging GenAI edits, screenshots, replays and print-and-scan copies.
.
Identity Verification
Some customers need more than one check. Shufti combines document, biometric, NFC and address checks in one API session, so a firm can step a customer up from a basic DAB tier to full verification without restarting onboarding.
.KYB Solutions
Afghan companies register with the Central Business Registry, and many sit inside group structures with corporate shareholders. Shufti reads ACBR registration, Articles and shareholder records at every review, maps ownership to DAB's beneficial ownership test and ties each owner to a verified identity.
Explore More
Business Verification
Onboarding an Afghan company means confirming its business licence, TIN, president, vice president and everyone who owns or controls more than 10%. Shufti confirms the ACBR registration, reads owners from the Articles of Association and shareholder records the company provides and ties each to a verified identity.
.
Enhanced Due Diligence
PEPs, high-risk customers and money service providers need enhanced checks under Articles 12 and 15 of the AML Law. Shufti's due diligence forms branch by risk, collect source of funds and verify beneficial owners through secure links before an analyst signs off.
.AML Screening
A customer who is clean at onboarding can land on a list next week. Shufti's perpetual KYC rescreens customers against 4,000+ watchlists, including the UN 1267 and 1988 sanctions lists that FinTRACA directs firms to apply, refreshes every 15 minutes and keeps each alert in one case file.
Explore More
Business AML Screening
Sanctions exposure often sits with an owner or officer rather than the company itself. Shufti screens every entity, owner and signatory against UN Security Council lists, PEP data and adverse media, and perpetual KYB rescreens them whenever ownership changes.
.
Transaction Monitoring
Banks choosing AML monitoring software in Afghanistan need it to report transactions above AFN 1,000,000 to FinTRACA each month and to catch structuring below that line. Shufti's library of 500+ pre-built rules covers structuring, smurfing and mule activity with 60% fewer false positives.
.
AI Compliance Co-Pilot
One common name can return 140+ screening hits. Shufti's AI Compliance Co-Pilot reviews every hit, assigns a 0 to 100 confidence score and a written reason, and leaves the final decision with the MLRO, whose overrides are logged.
.Built To Fit Afghanistan's Compliance Landscape
AML systems in Afghanistan answer to the AML Law and FinTRACA across every sector, while Da Afghanistan Bank adds its own regulations for banks, money service providers, e-money institutions and microfinance lenders. Shufti maps its KYC, KYB, AML screening and transaction monitoring controls to every regime below, so one platform covers each licence your group holds.
Anti-Money Laundering and Proceeds of Crime Law
Afghanistan's primary AML law requires identification with an original national identity card or passport, ongoing due diligence and specific measures for customers not physically present (Article 12), enhanced checks on PEPs (Article 15), five-year record keeping (Article 16) and suspicious transaction reports within three days (Article 18).
Financial Transactions and Reports Analysis Center of Afghanistan (FinTRACA)
Set up within Da Afghanistan Bank under Article 25 of the AML Law with operational independence, FinTRACA receives suspicious transaction reports and threshold reports from banks, money service providers, e-money and microfinance institutions, and enforces compliance under Article 24 through warnings, licence suspensions and revocations.
Da Afghanistan Bank (DAB)
The central bank licenses and supervises banks, money service providers, foreign exchange dealers, electronic money institutions, payment institutions and microfinance institutions. The Banking Law it enforces bars accounts for undisclosed persons, requires customer identification (Article 84) and requires banks to keep transaction records for at least ten years (Article 78).
AML/CFT Responsibilities and Preventive Measures Regulation
DAB's 2016 regulation defines a beneficial owner as anyone owning or controlling more than 10% (Article 8), requires suspicious transaction reports within three working days (Article 19), monthly reports of bank transactions above AFN 1,000,000 (Article 20) and ten-year retention of STR copies (Article 24).
Know Your Customer Regulation (2021)
Approved by DAB in August 2021, it tiers customer due diligence by amount (Articles 7 and 8), calls for sanctions screening before onboarding and KYC refreshes every one, two or three years by risk (Article 14), and sets transaction limits for e-money institutions (Article 15).
Microfinance Regulation
Published by DAB in 2024, it caps microfinance financing at AFN 1,500,000, requires an electronic Tazkira for any financing above AFN 20,000 (Article 31), bars financing to individuals on sanctions lists (Article 32) and applies KYC under the AML Law and DAB's 2016 regulation.
Law on Combating the Financing of Terrorism
Provides for designations under UN Security Council resolutions and domestic powers (Article 10), requires funds of designated persons to be frozen without delay and without prior notice (Article 11), and sets out humanitarian exemptions (Article 18) and delisting procedures (Article 19).
UN Security Council 1988 Sanctions Committee
Maintains the 1988 Sanctions List, whose listed individuals and entities face an asset freeze, travel ban and arms embargo. A standing freezing order, published by FinTRACA, applies it in Afghanistan together with the 1267 list, so firms screen customers, owners and counterparties against both.
High-Level Coordination Commission on Combating Money Laundering and Terrorist Financing
Established under Article 33 of the AML Law with FinTRACA as its secretariat, the commission coordinates AML and CFT policy across ministries and agencies. In March 2021 it approved a publishable version of the national money laundering and terrorist financing risk assessment first presented in 2019.
Ministry of Industry and Commerce (MoIC)
Runs the Afghanistan Central Business Registry, which registers corporations, partnerships, limited liability companies and sole proprietorships and issues business licences. Registration needs the Tazkira or passport of the company's president and vice president and its founding articles, and key details are published in the Official Gazette.
Ministry of Interior Affairs
Issues Afghan passports through its General Directorate of Passports, valid for five or ten years, and driving licences through its traffic services. Passport applicants submit a Tazkira or e-Tazkira and attend in person so their biometrics can be captured at the passport office.
Afghanistan Data Residency and Deployment
Shufti offers on-premises deployment inside Afghan infrastructure, including air-gapped setups, or nearest-region cloud hosting where the client approves the transfer. The agreement defines hosting locations and transfer safeguards, and DAB's inspection access to records stays intact under either model.
Banking Secrecy Under the Banking Law
Article 65 of the Banking Law binds bank staff to keep customer information secret, and Article 8 of the AML Law sets that secrecy aside for AML purposes. Shufti applies encryption, role-based access and configurable retention so identity and biometric data reach only authorised staff.
DAB Privacy and Security Rules
Afghanistan has no general data protection law, so DAB's rules set the bar. The EFT Regulation requires an information security policy and limits disclosure (Articles 4 and 34), and the Branchless Banking Regulation bars agent devices from storing biometrics (Article 20). Shufti's encrypted capture supports both duties.
Outsourcing and Third-Party Responsibility
DAB's payment system and EFT regulations keep the licensed firm responsible for any third party it engages and preserve DAB's monitoring access. Shufti supplies processing records, audit logs and a data processing agreement that let the firm show that oversight in an inspection.
Retention Controls
Retention is configurable by client and licence. The five-year minimum in Article 16 of the AML Law, and ten years for STR copies and bank transaction records, is a floor, not an automatic deletion date, and legal holds keep records needed for FinTRACA requests.
Encryption and Security
Data is encrypted in transit and at rest, with role-based access and audit logging throughout. Shufti holds ISO 27001:2022 certification and a SOC 2 Type 2 report, and shares its reports for vendor due diligence and the annual IT audit DAB's External Audit Regulation requires of banks.
Automated Decisions and Biometric Data
Shufti returns every verification result with its supporting details through the API and back office, so support and compliance teams can explain an outcome to the customer, review a disputed decision and escalate it for a fresh check.
Scope of Our Role
Shufti acts as a third-party service provider on each firm's instructions, and the licensed firm keeps responsibility for customer due diligence under Article 12 of the AML Law. Shufti's privacy notice identifies any activity it carries out as an independent controller.
Data Residency and Privacy Controls in Afghanistan
Afghanistan AML Sources That Strengthen Decisions
Da Afghanistan Bank (DAB)
Financial Transactions and Reports Analysis Center of Afghanistan (FinTRACA)
Ministry of Finance – Afghanistan Customs Department
Financial Action Task Force (FATF)
Asia/Pacific Group on Money Laundering (APG)
Egmont Group of Financial Intelligence Units
United Nations Office on Drugs and Crime (UNODC)
UN Security Council 1988 Sanctions Committee
World Customs Organization (WCO)
International Criminal Police Organization (INTERPOL)
World Bank Group
International Monetary Fund (IMF)
Basel Committee on Banking Supervision
Wolfsberg Group
Office of Foreign Assets Control (OFAC)
Turn Afghanistan Verification Requirements into a Smoother Customer Journey
Share your customer types, risk rules and current onboarding process. A Shufti specialist will show you how to connect identity verification, KYB and ongoing monitoring, reducing operational hand-offs while keeping decision evidence organised for compliance review.
INDEPENDENTLY AUDITED. GLOBALLY CERTIFIED.
Certified to Global Standards



PROVEN WORKFLOWS
Identity Verification Built Around Your Industry in Afghanistan
Faster Account Opening On DAB-Aligned Checks
The 12 banks DAB lists as licensed must identify every account holder, screen customers before onboarding and refresh KYC on a risk-based cycle. Shufti verifies Tazkiras and passports remotely, applies DAB's KYC tiers automatically and keeps each decision ready for supervisory inspection or a FinTRACA request.
Frequently Asked Questions
Does Shufti support the e-Tazkira, and what happens when customers cannot use it?
Yes. Shufti reads the e-Tazkira's Dari, Pashto and English fields, checks it for tampering and matches its photo to a liveness-checked selfie. Customers with only a paper Tazkira, or no Tazkira at all, move to passport or video verification in the same flow, or NFC where they hold a foreign biometric passport.
Is an e-Tazkira image enough to verify an Afghan customer?
An image alone leaves room for edited or borrowed cards. Shufti adds forensic tamper checks and a liveness-backed selfie match, with video identification for higher-risk cases, which supports the specific measures Article 12 of the AML Law requires for customers who are not physically present.
Can Shufti verify foreign documents or identity formats it has not encountered before?
Yes. Shufti's zero-shot document intelligence reads unfamiliar layouts and checks them for tampering, so aid workers, foreign investors and Afghans holding foreign papers onboard without waiting for a template. Article 12 of the AML Law also lets firms accept other documents their procedures prescribe.
How does Shufti OCR compare with Google OCR for Dari and Pashto identity documents?
Shufti's OCR reads the Dari, Pashto and English fields on Afghan documents, and across the languages in its published benchmark against Google Vision it averages 93% accuracy to Google's 78.4%. Shufti also transliterates extracted names into Latin script, so the same person matches across documents, records and watchlists.
How does Shufti verify ownership when an Afghan company has several corporate layers?
Shufti reads ACBR registration details, Articles of Association and shareholder records, and traces each corporate shareholder to the natural person in control. It applies DAB's test of more than 10% ownership or control, plus anyone who manages the entity or controls it by other means.
Does Shufti's ongoing monitoring cover more than sanctions screening?
Yes. Article 12 of the AML Law requires ongoing due diligence and scrutiny of transactions throughout the relationship. Shufti compares transactions with each customer's profile, rescreens sanctions, PEP and adverse media data, and flags ownership and officer changes before the next scheduled KYC refresh.
How does Shufti keep screening current and handle Dari and Pashto name variations?
Watchlists, including the UN 1267 and 1988 sanctions lists, refresh every 15 minutes. Native phonetic models across 80+ languages match transliteration variants, patronymic names and reordered names, so a listed person is caught without flooding analysts with false hits on common names.
Can we choose Afghanistan hosting or run verification inside our own infrastructure?
Yes. Shufti can run on-premises inside your Afghan infrastructure, including fully air-gapped deployments, or in nearest-region cloud hosting where you approve the transfer. The agreement records the hosting location and transfer safeguards, and DAB keeps its inspection access to your records either way.
What controls help us protect identity and biometric data?
Encryption in transit and at rest, role-based access, audit logs and configurable retention protect identity and biometric data. Shufti's independent certifications support vendor reviews, and its access records help banks show they meet the secrecy duty in Article 65 of the Banking Law.
Can we configure different retention periods for different Afghanistan licences?
Yes. Retention is set per client, product and licence, so a bank, a money service provider and an e-money institution in one group can each keep records for their own required period, with legal holds wherever FinTRACA or DAB needs them.
What does Shufti provide when our compliance team needs to prepare a FinTRACA report?
Shufti assembles a report-ready bundle with the customer's verification results, screening hits, transaction history, analyst notes and decision trail, so the compliance officer can review the evidence and file the suspicious transaction report within the three days the AML Law allows.
Can we add verification checks without rebuilding our onboarding journey?
Yes. Shufti's AI Journey Builder adds or reorders checks such as NFC, video, address or EDD questionnaires by product, DAB tier and risk level through the same API and SDK, so existing journeys keep running while new steps go live for the customers who need them.
How does Shufti make verification queries easier for our customer support team?
Support agents see each verification result in the back office with the reason behind it, the documents captured and the checks that passed or failed, so they can explain an outcome, request a resubmission or escalate a dispute without involving engineering.
Let’s Build Trust Into Your Business
1B+Verifications Processed
240+Regions Actively Processed
99.7%Accuracy Rate
Samer Al Tamimi
CEO of Safwa Bank
“We take our client’s privacy very seriously and always look for new innovative solutions to ensure a safe banking experience. Working with Shufti feels like a breath of fresh air, as their 100% in-house tech keeps our customer’s data free from vulnerabilities and fully safe and protected.”
Trusted. Compliant. Certified
Explore Shufti For Your Business
Get a personalised demo from our experts.
PROVEN PLAYBOOKS
Explore Practical KYC & AML Resources
4 June, 2025
Sanctions Lists: OFAC, EU & UN Compliance Guide
How UN, EU and national sanctions lists work, who they target, and what screening businesses need in place to avoid dealing with sanctioned people or entities.
Knowledge Base