

 AMLR Solutions
 AMLR Consultation
 EUDI Wallet
 Onboarding
 Ongoing Monitoring
 FRAML
 KYC
 KYB
 KYI
 Age Assurance
 Workforce IAM
 Candidate Verification
 Account Takeover
 Bonus/ Promotion Abuse
 Chargeback Fraud
 Deepfake
 Document Fraud
 Fraud Networks
 Impersonation Fraud
 Money Mule Activity
 Multi-Accounting
 Party Fraud
 Regulatory & Compliance Risks
 Synthetic Identity Fraud
 Adult Content
 Banking
 Crypto
 Fintech
 Forex
 Compliance
 Fraud prevention
 Trust & safety
 Global expansion
 Compliance Officers
 Developers
 Fraud Analysts
 Product Managers
 Journey Builder
 Global Trust Platform
 Customer Profiles
 Vendor Comparison
 IDV Case Management
 AML Case Management
 Regulatory Reporting
 Agentic Rule Builder
 AI Compliance Co-Pilot
 Fraud Analytics
 Fraud Hub
 OCR
 Shufti AI
 Bank Account Verification
 Biometric Duplication
 Database Checks
 Document Intelligence
 Government ID
 Mobile Driver's License
 NFC
 Selfie Liveness
 Brand Personalisation
 Deployment Options
 Identity Methods
 IDV Modes
 Multi-tenancy
 On-Premise IDV
 Secure Capture
 Shufti MCP


- Algeria
- Argentina
- Australia
- Austria
- Bangladesh
- Belgium
- Brazil
- Bulgaria
- Cambodia
- Canada
- Chile
- China
- Colombia
- Croatia
- Cyprus
- Czech Republic
- Denmark
- Dominican Republic
- Egypt
- Estonia
- Eswatini
- Ethiopia
- Finland
- France
- Germany
- Greece
- Haiti
- Hong Kong
- Hungary
- India
- Iraq
- Ireland
- Indonesia
- Italy
- Japan
- Jordan
- Kazakhstan
- Kenya
- Kosovo
- Kuwait
- Latvia
- Lithuania
- Luxembourg
- Malaysia
- Malta
- Mauritius
- Mexico
- Micronesia
- Moldova
- Mongolia
- Montenegro
- Morocco
- Mozambique
- Myanmar
- Namibia
- Nauru
- Nepal
- Nigeria
- Nicaragua
- Niue
- Norway
- Netherlands
- New Zealand
- Oman
- Pakistan
- Palau
- Palestine
- Panama
- Papua New Guinea
- Paraguay
- Peru
- Puerto Rico
- Philippines
- Portugal
- Poland
- Qatar
- Republic of Congo
- Romania
- Russia
- Rwanda
- Samoa
- San Marino
- Senegal
- Serbia
- Seychelles
- Sierra Leone
- Singapore
- Slovakia
- Slovenia
- Somalia
- South Africa
- South Korea
- South Sudan
- Spain
- Sri Lanka
- St Kitts and Nevis
- St Maarten
- St Lucia
- Sweden
- Switzerland `
- Syria
- Taiwan
- Tajikistan
- Tanzania
- Thailand
- Timor Leste
- Togo
- Tonga
- Trinidad and Tobago
- Turkey
- Turks and Caicos
- Turkmenistan
- Tunisia
- Tuvalu
- UAE
- Uganda
- Ukraine
- UK
- USA
- Vietnam
Scale Identity Verification and KYC Operations in Algeria
Verify residents and expats through CNIBE and passport NFC chip reads and 10,000+ foreign ID document types, run KYB on CNRC-registered businesses and real owners, and monitor transactions and sanctions lists. One platform runs compliance and fraud prevention across the full customer lifecycle for Bank of Algeria-, COSOB- and CSA-supervised firms.




Operational Performance for Algeria KYC
Our Numbers Speak Volumes
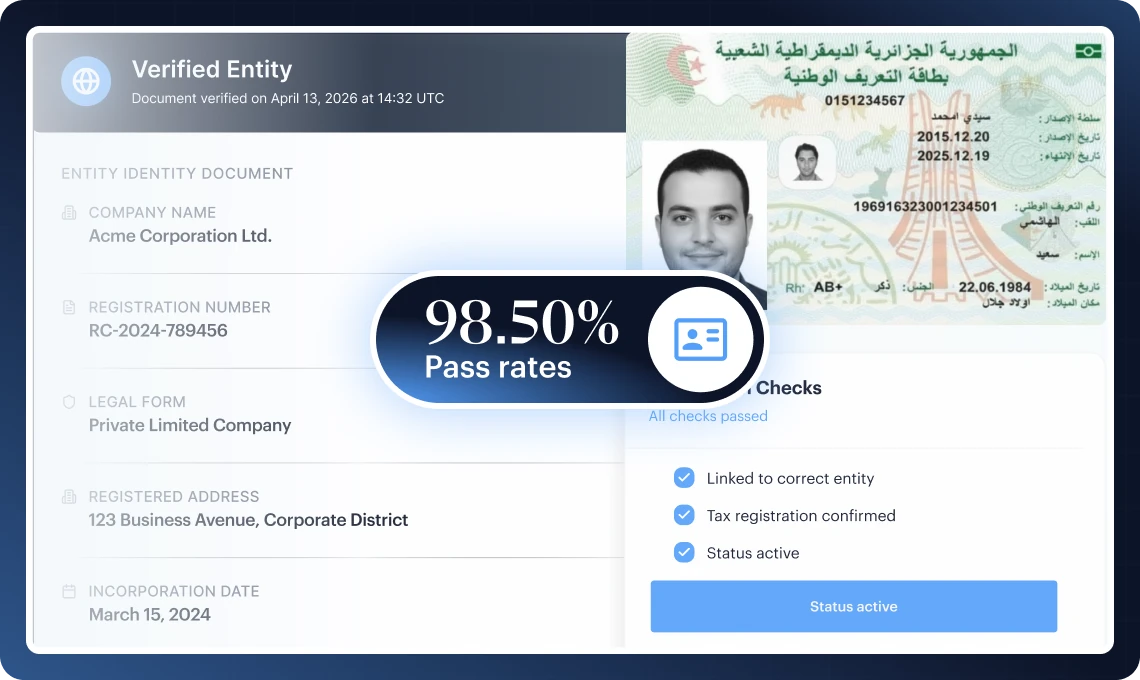
98.50%
Pass
Rates
Under 5 secs
IDV
Verification
100%
Omni-format
Document Recognition
Algeria IDV/KYC Challenges
Beneficial Ownership Rules Changed in April 2026
Executive Decree 26-163 replaced the 2023 rules, extending them to legal arrangements and requiring yearly confirmation. KYC compliance in Algeria now means checking each corporate customer's declared owners against the CNRC register. Shufti's KYB identifies owners at the 20% threshold and flags register changes.
Banks Must Block Prohibited Virtual-Asset Payments
Law 25-10 bans holding, trading and mining virtual assets, and Bank of Algeria Regulation 24-03 requires banks to block related operations and report them to the CTRF immediately. Shufti's crypto wallet screening and transaction monitoring flag payments tied to virtual-asset platforms before they settle.
High-Risk Customer Files Need Review at Least Once a Year
Law 05-01, as amended in 2025, caps the review cycle for high-risk customers at one year and requires scrutiny of transactions for the whole relationship. Shufti checks every transaction against the customer's profile, rescreens lists continuously and raises a review when ownership or behavior changes.
Thin Case Files Weaken Reports Filed Through e-DS
Suspicious transaction reports reach the CTRF through its e-DS online platform, and refusing to report is a criminal offence under Law 05-01. A report assembled from scattered evidence is hard to defend. Shufti keeps identity, screening and transaction evidence for each alert in one case file.
Documents and Languages
Individual Documents Shufti Verifies in Algeria
Shufti verifies 8 Algerian document types plus passports and ID cards from other countries. The cards below cover the core documents Algerian onboarding relies on, with the full list on the supported documents page.
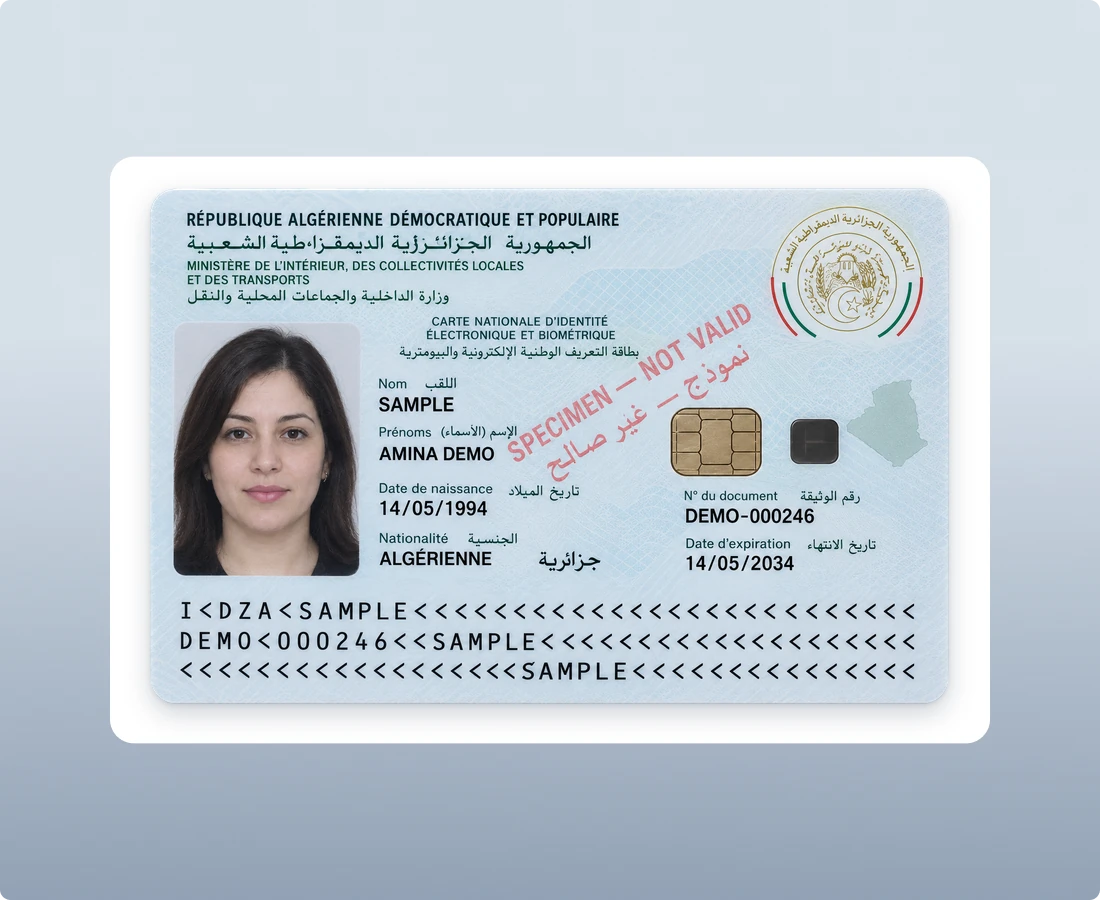
View All Supported DocumentsAlgerian Biometric National ID Card (CNIBE)
The Ministry of Interior issues the CNIBE under Presidential Decree 17-143, with two electronic chips and the 18-digit national identification number. Shufti reads the chip over NFC, runs nine forensic detection layers on the card and matches the holder with biometric liveness.
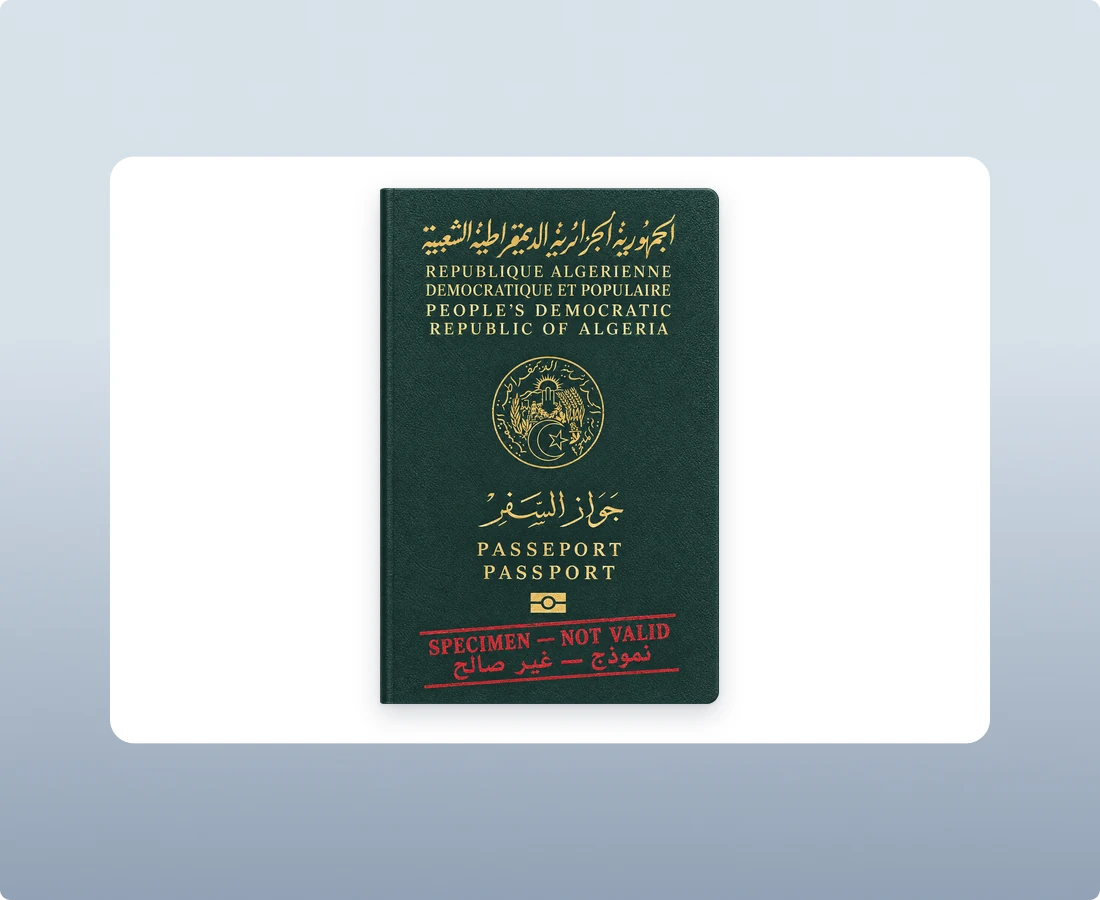
Algerian Biometric Passport
Issued under Law 14-03, the biometric electronic passport stores the holder's data on a chip. Shufti reads that chip over NFC and validates the MRZ checksum and printed security features, so a cloned or altered passport fails before onboarding.
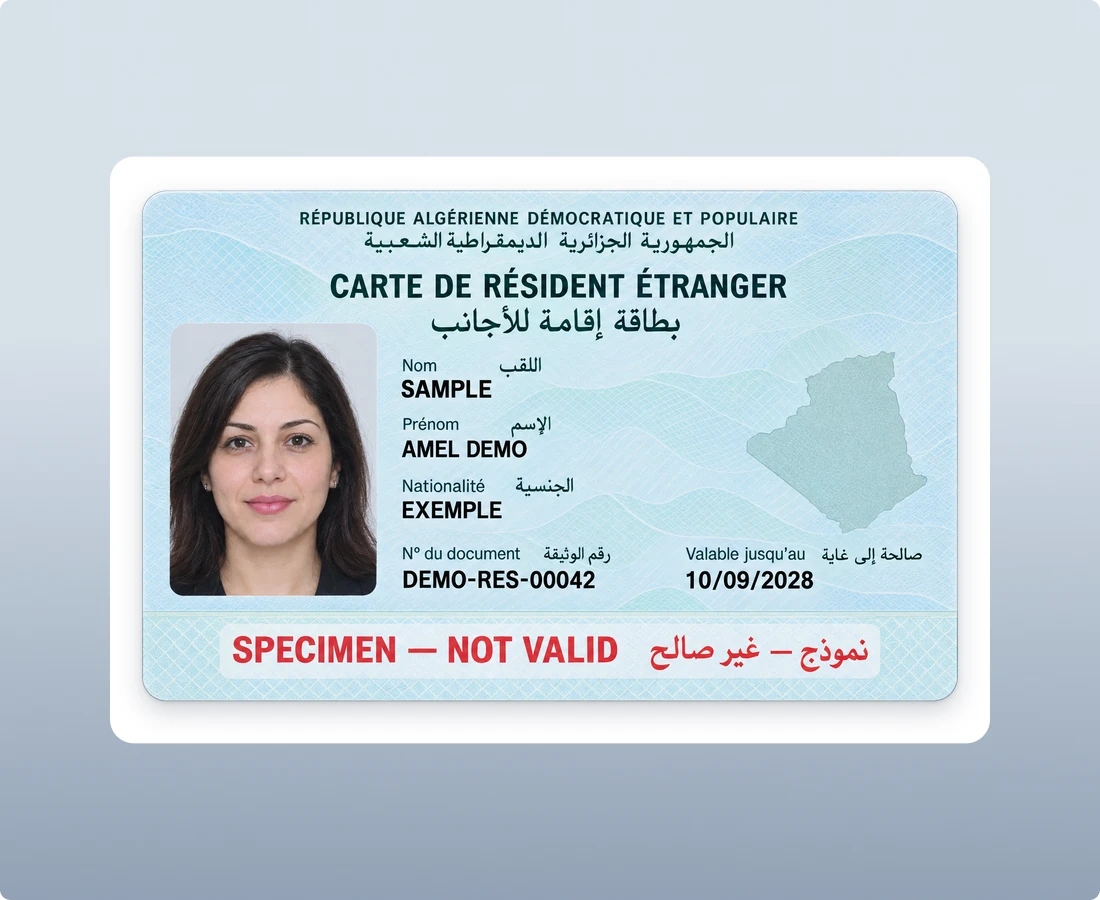
Residence Card for Foreign Nationals
Foreign nationals living in Algeria hold a residence card issued by the wilaya under Law 08-11, valid for two or ten years. Shufti checks the card's authenticity and expiry and pairs it with the holder's passport in the same flow.
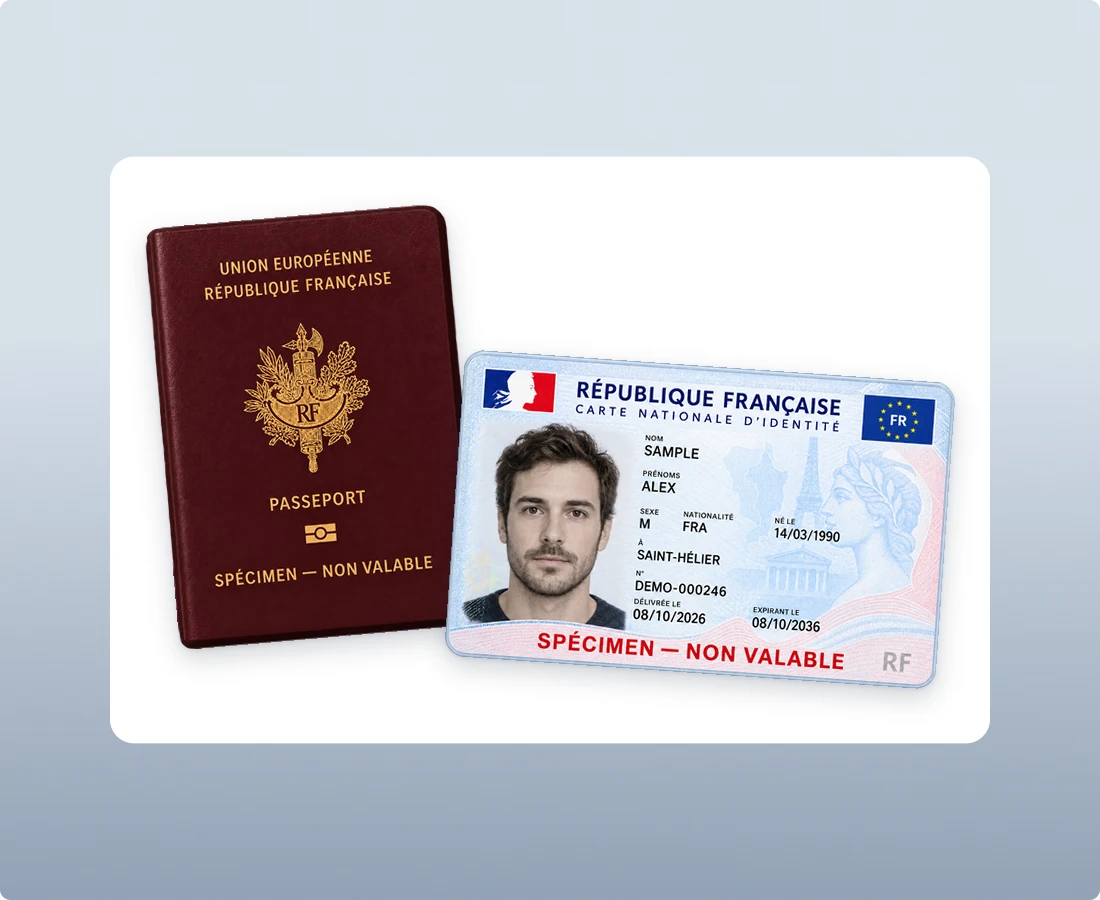
Foreign Passports and National ID Cards
Shufti actively processes 10,000+ ID document types from 240+ countries and territories, and its zero-shot AI learns new document formats in minutes. That covers foreign workers, students and non-resident investors who onboard without an Algerian document.
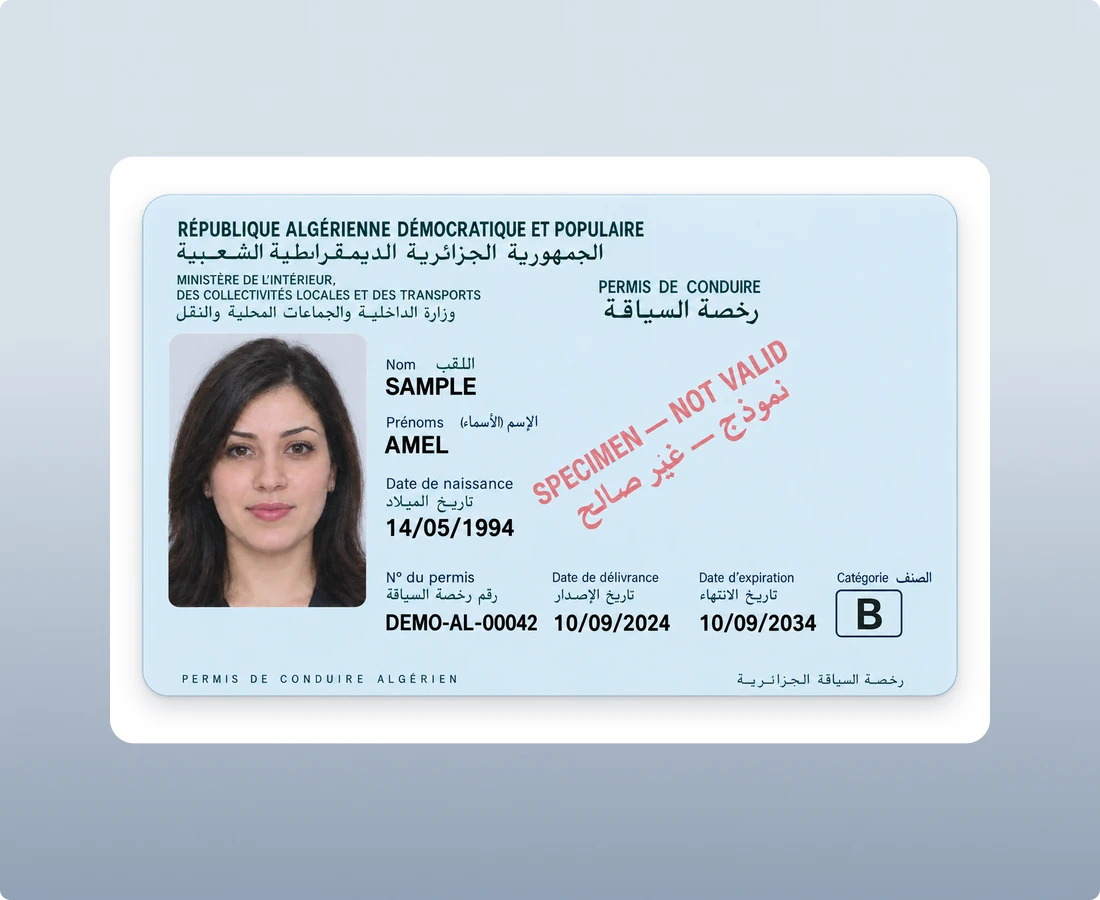
Algerian Driving License
Shufti verifies Algerian driving licences, including the biometric card format, by checking security features, expiry and the photo against a live selfie. Rental, delivery and transport businesses get a quick way to confirm who is behind an account.
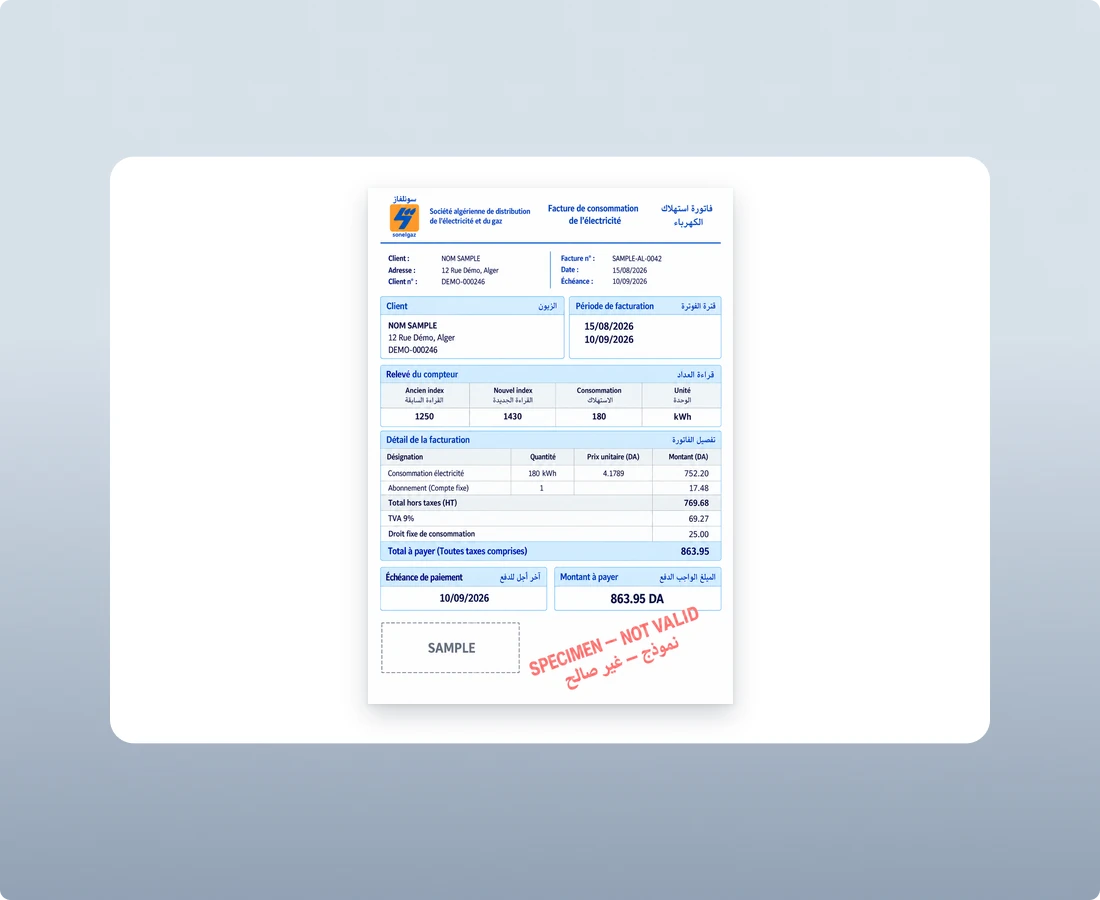
Proof of Address
Shufti reads Sonelgaz electricity and gas bills, Algérie Télécom, Djezzy, Mobilis and Ooredoo bills, bank statements and the residence certificate (certificat de résidence), then verifies the address against the customer's ID in one step.
Entity Identity
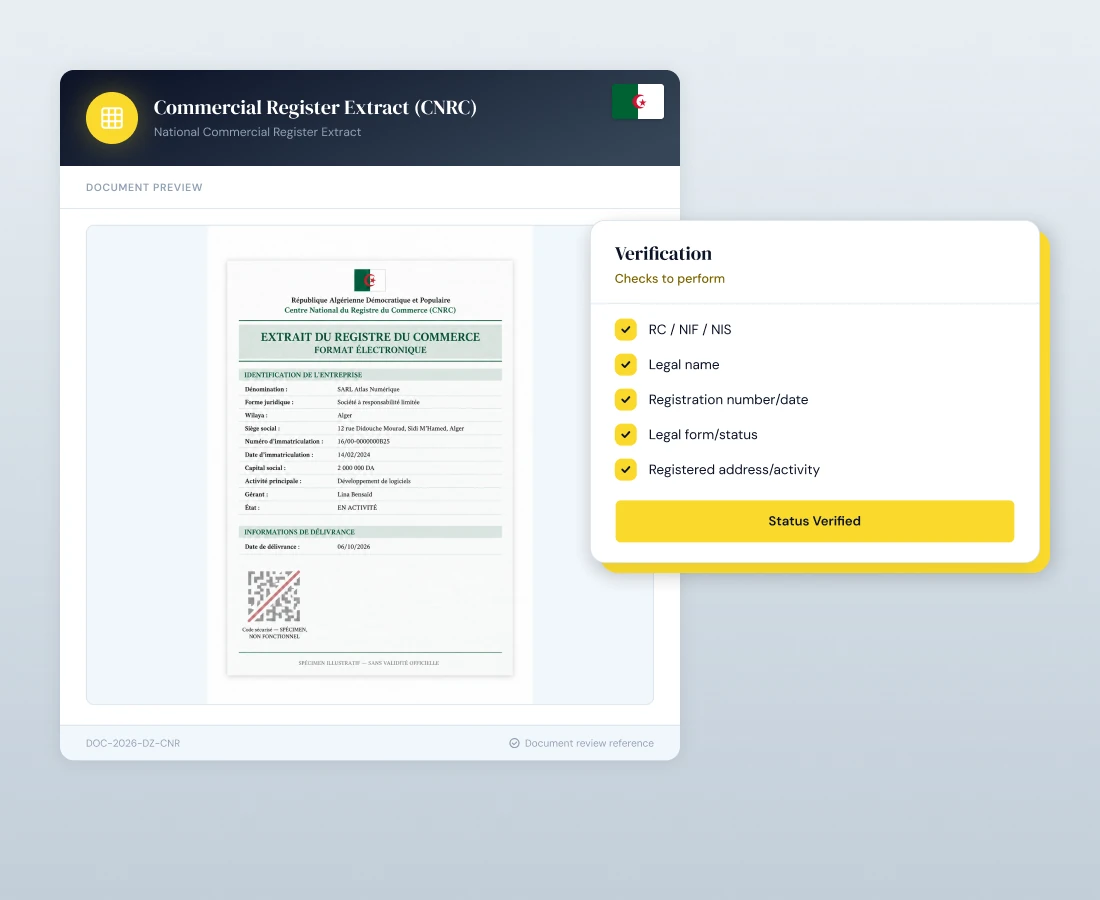
Commercial Register Extract (CNRC)
The CNRC's electronic commercial register extract carries a secured code that confirms the register number, company name, wilaya and active status. Shufti reads the extract and checks it against live register data, so a struck-off or altered record is caught at onboarding.
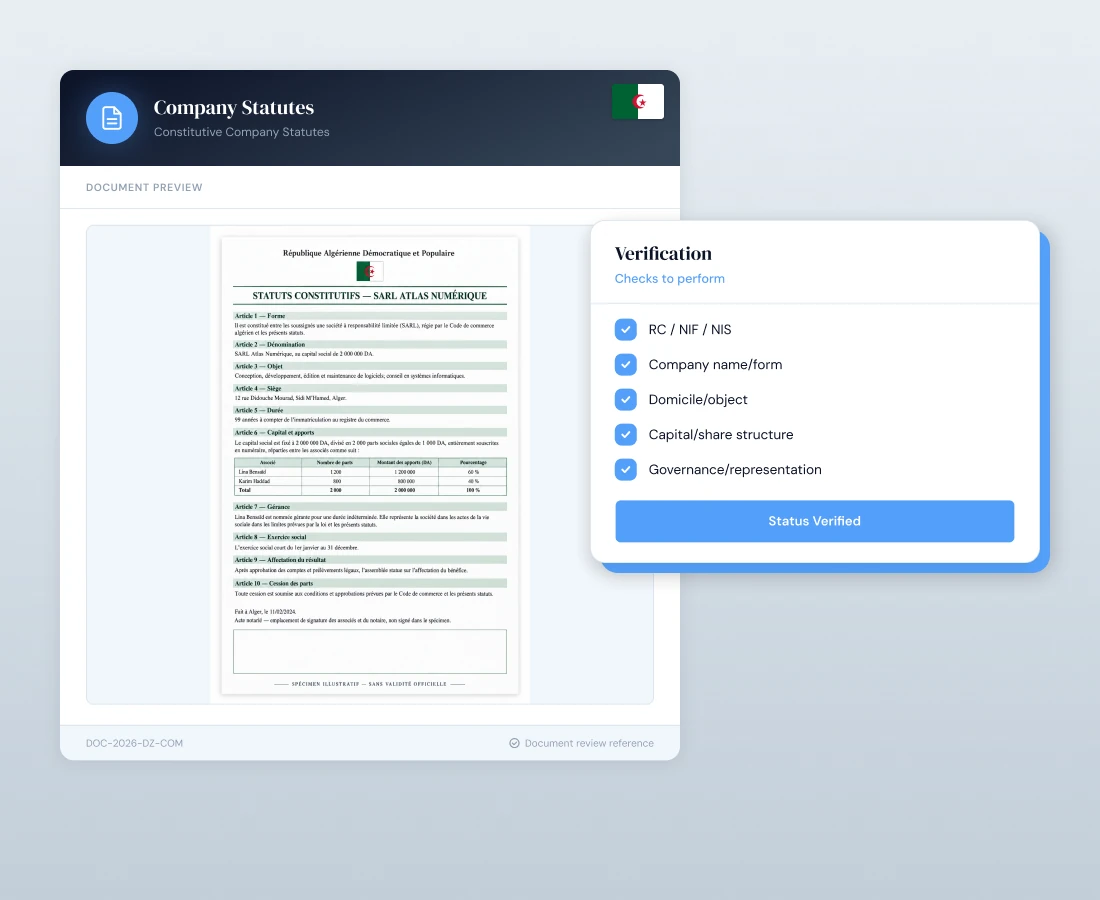
Company Statutes
Shufti's AI-OCR reads ownership, capital, manager powers and signing authority from the statutes of an SARL, EURL or SPA, checks them against the register extract and flags GAN-generated or edited pages before they reach a reviewer.
Auto-Entrepreneur Card
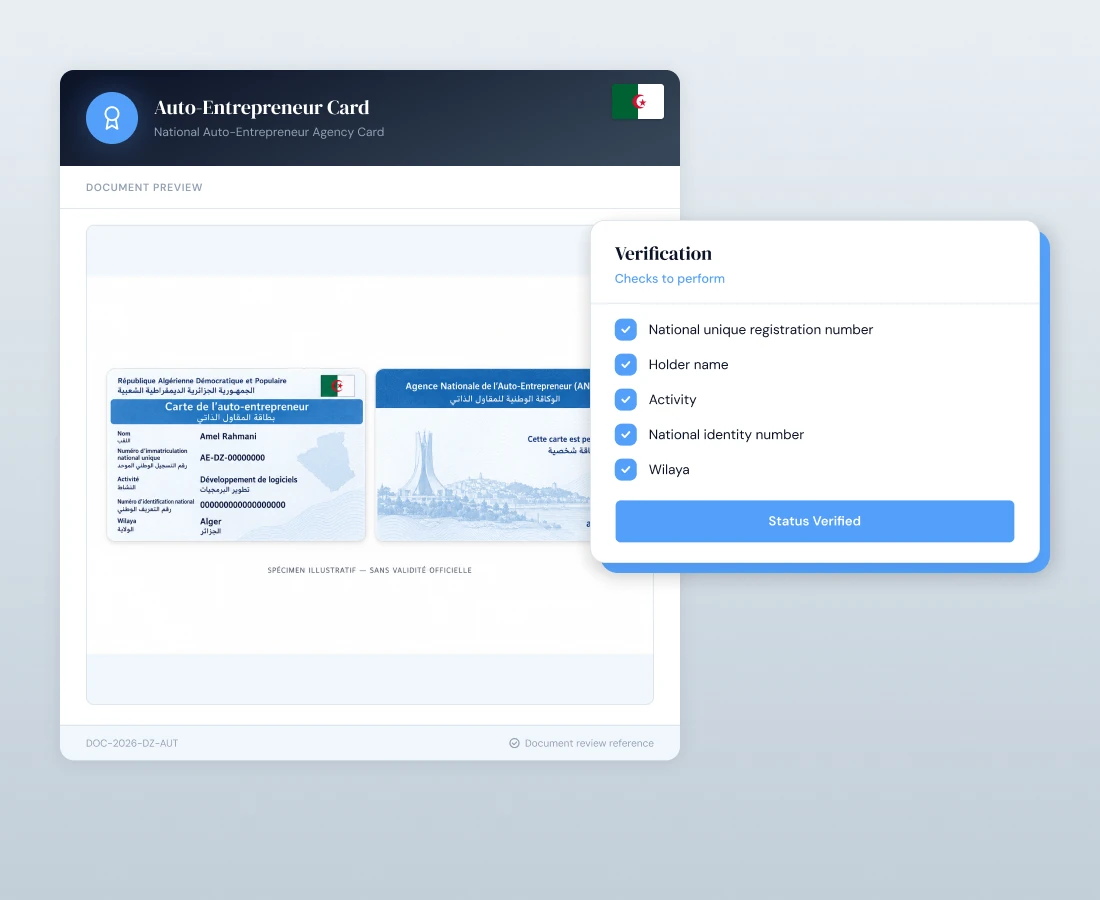
Self-employed traders registered under Law 22-23 hold an auto-entrepreneur card with a unique national number instead of a commercial register extract. Shufti verifies the card and the holder's CNIBE together, so sole traders onboard through the same KYB flow.
Business Address Proof
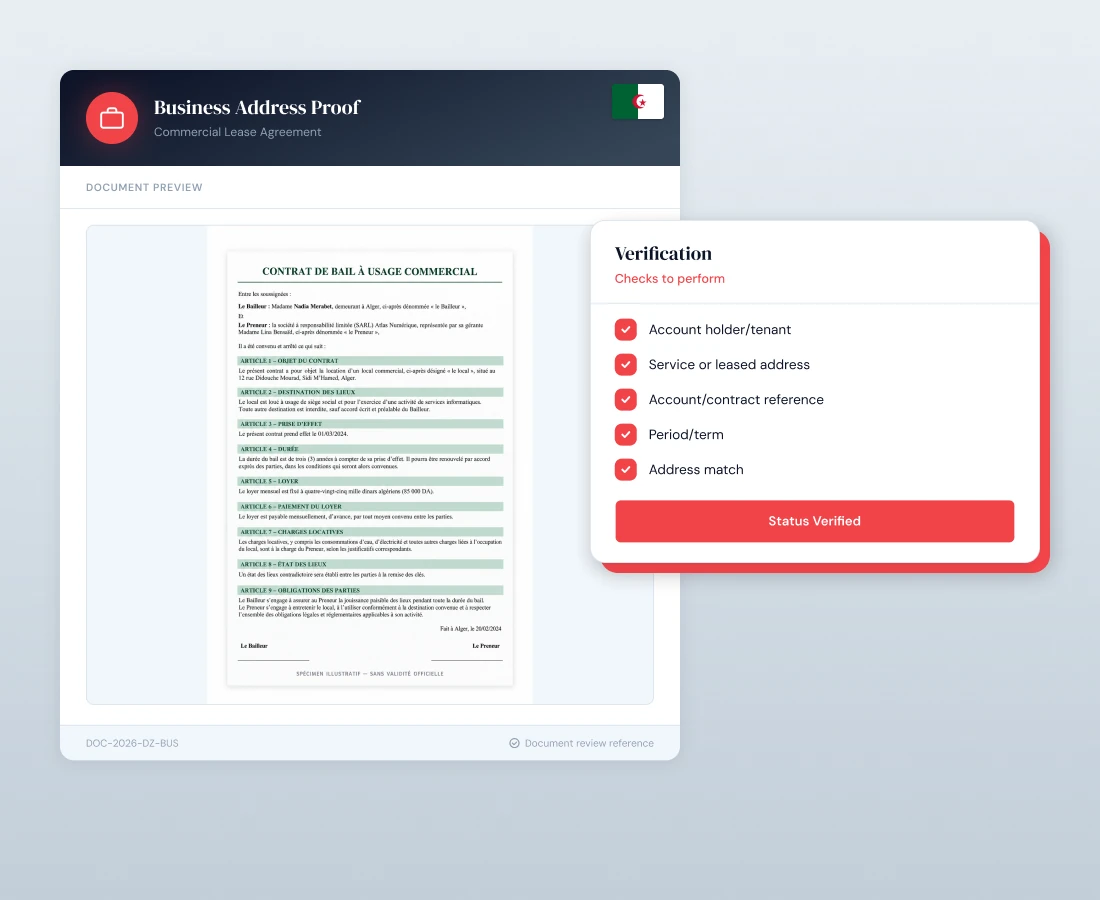
Lease agreements and utility bills for the business premises show where a company actually operates. Shufti cross-checks them against the address on the commercial register extract, so the declared seat matches the place of business.
Tax Identity
Tax Identification Number (NIF)
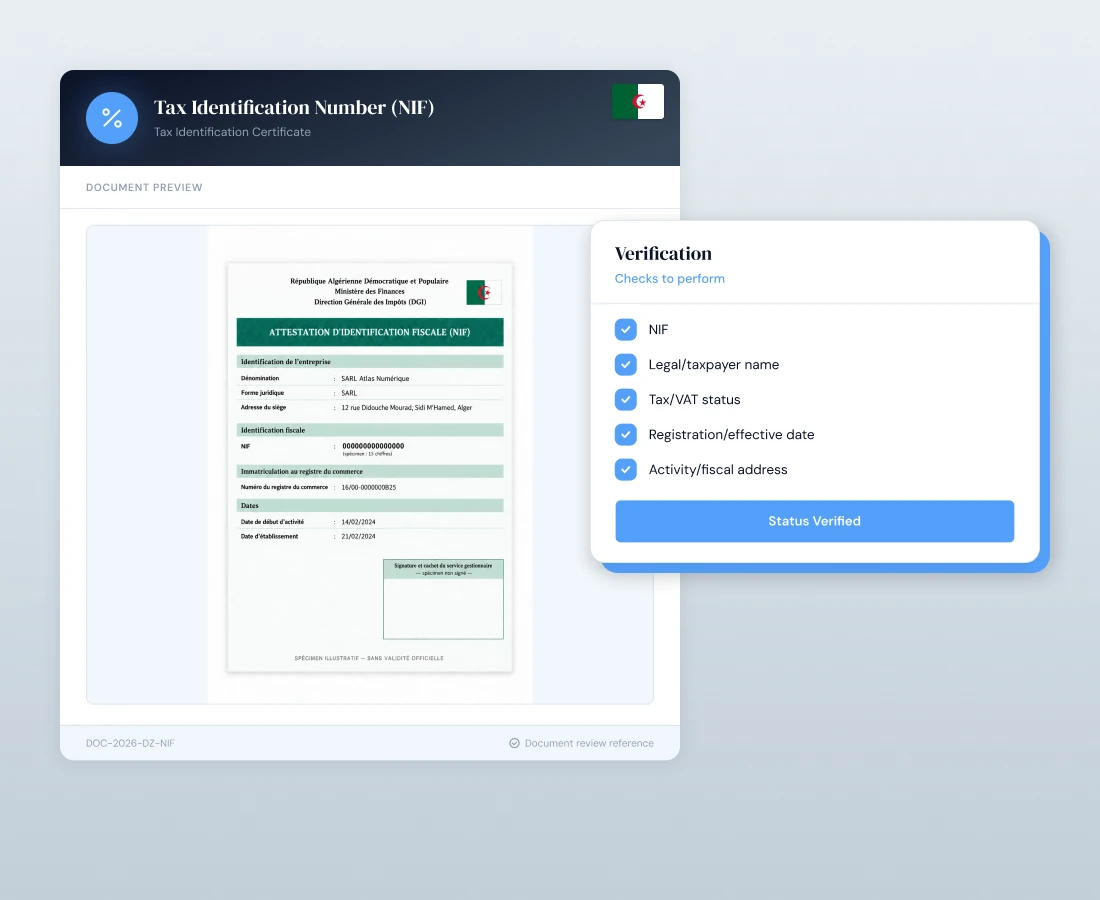
The Directorate General of Taxes issues the NIF to companies and, under Law 22-23, to auto-entrepreneurs within 30 days of registration. Shufti extracts the NIF from the certificate and cross-checks it against the company name and commercial register number.
Statistical Identification Number (NIS)
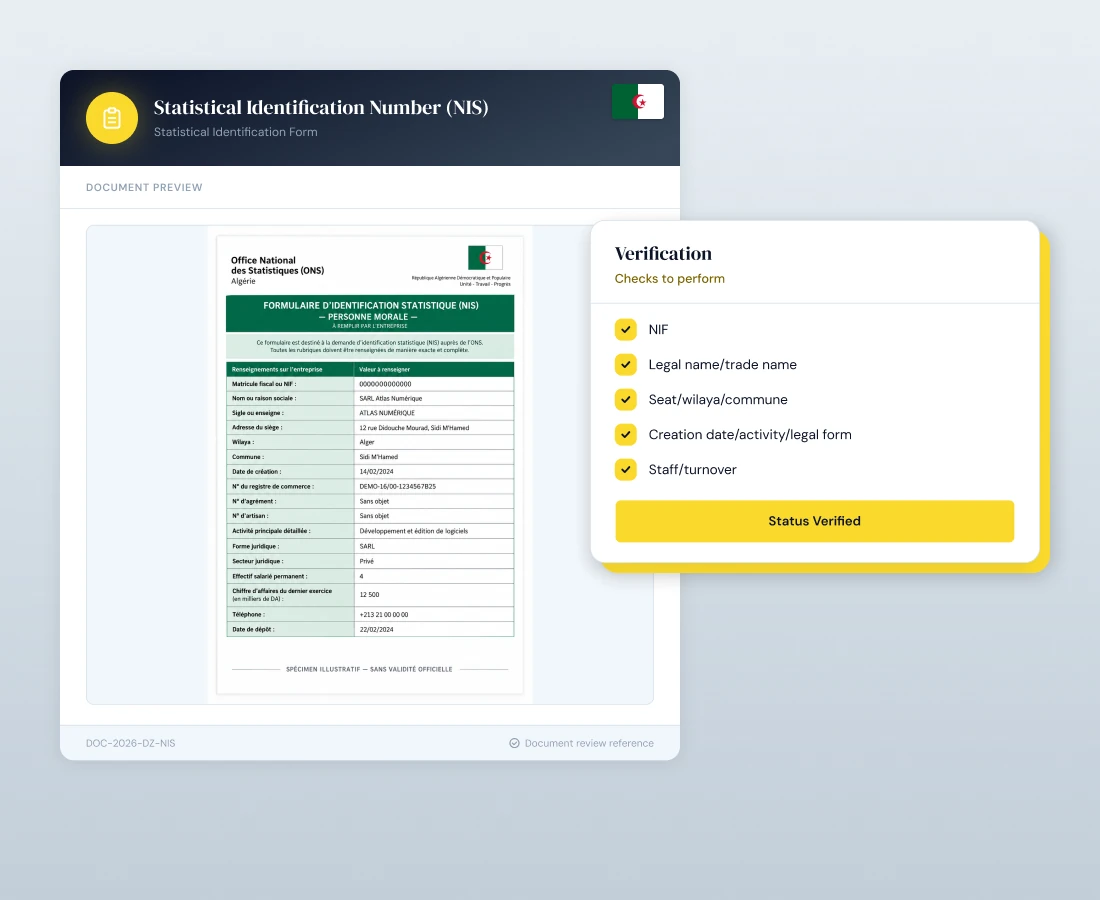
The National Office of Statistics assigns each business a statistical identification number, with extra digits for secondary establishments. Shufti reads the NIS alongside the NIF, catching mismatches between a branch and its head office.
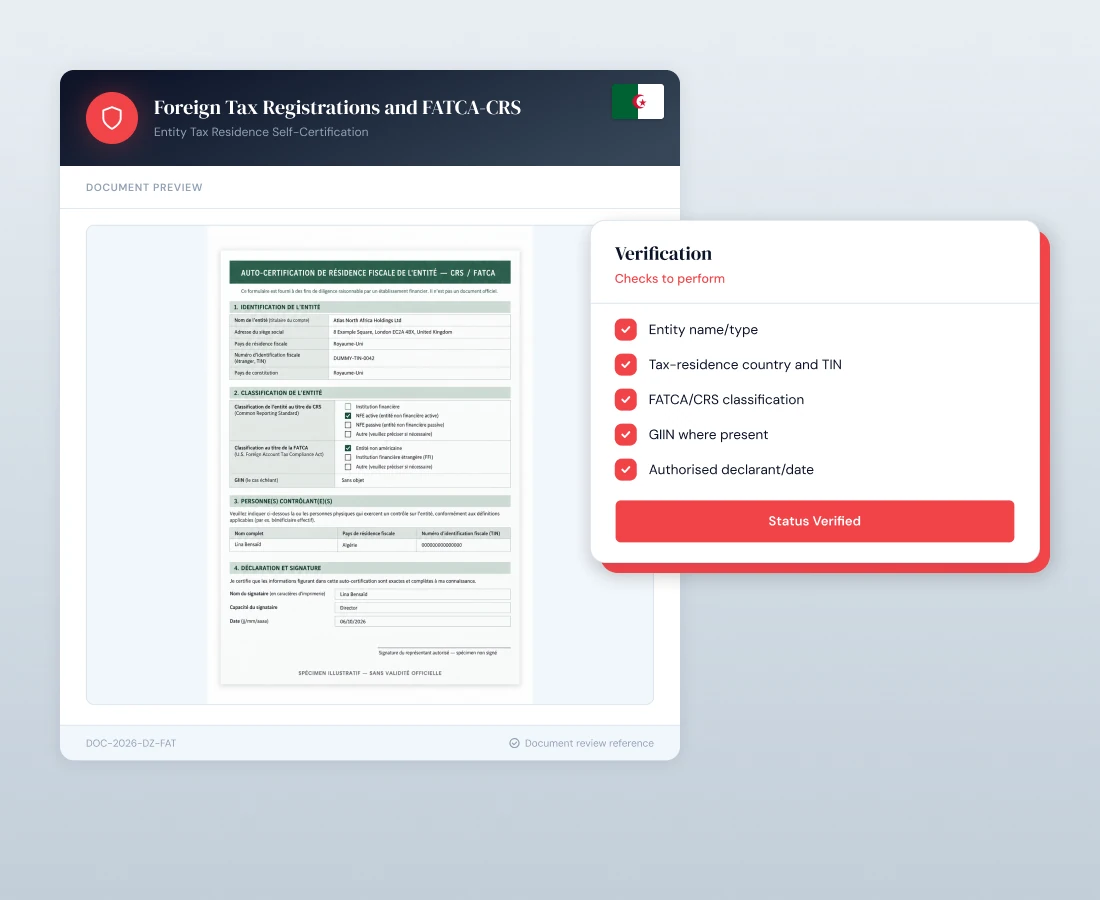
Foreign Tax Registrations and FATCA/CRS
For foreign shareholders and non-resident group companies, Shufti's due diligence forms capture foreign tax identifiers and FATCA and CRS self-certifications in the same KYB case, so tax status sits beside ownership data.
Ownership and Control
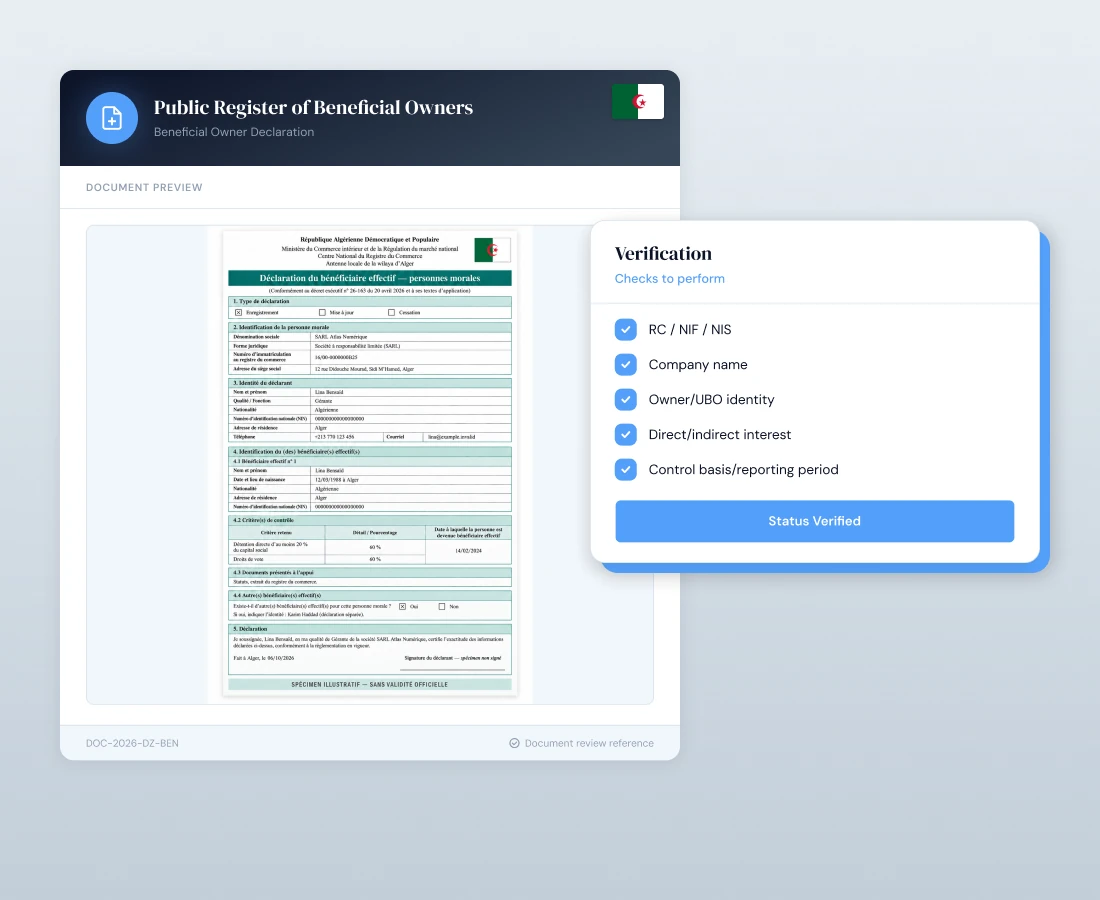
Public Register of Beneficial Owners
Executive Decree 26-163 of April 2026 replaced Decree 23-429 and keeps the register at the CNRC, which banks and other reporting entities may consult for due diligence. Shufti identifies everyone who owns or controls 20% or more and screens each person.
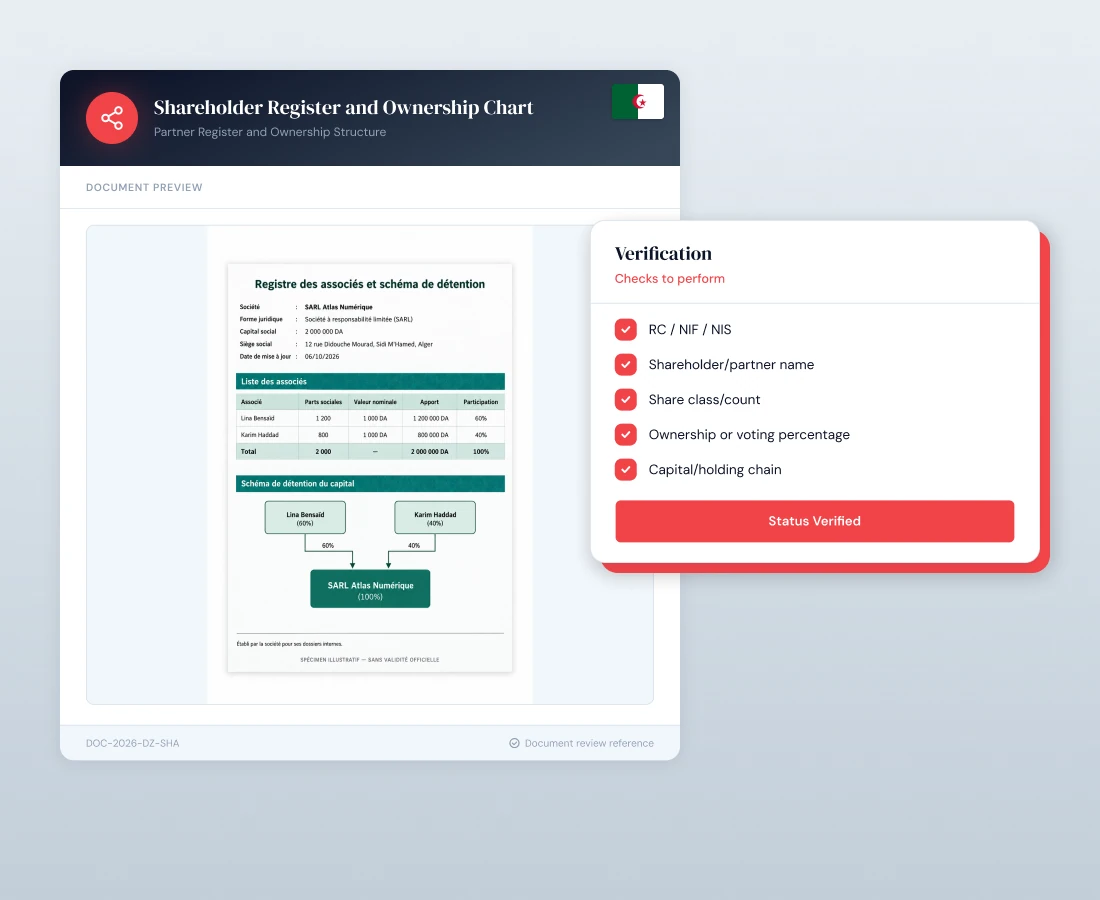
Shareholder Register and Ownership Chart
Shufti maps ownership through holding companies and intermediate layers using the statutes and shareholder records, then screens every person and entity in the chain against sanctions, PEP and adverse media lists, including Algeria's national terrorist list.
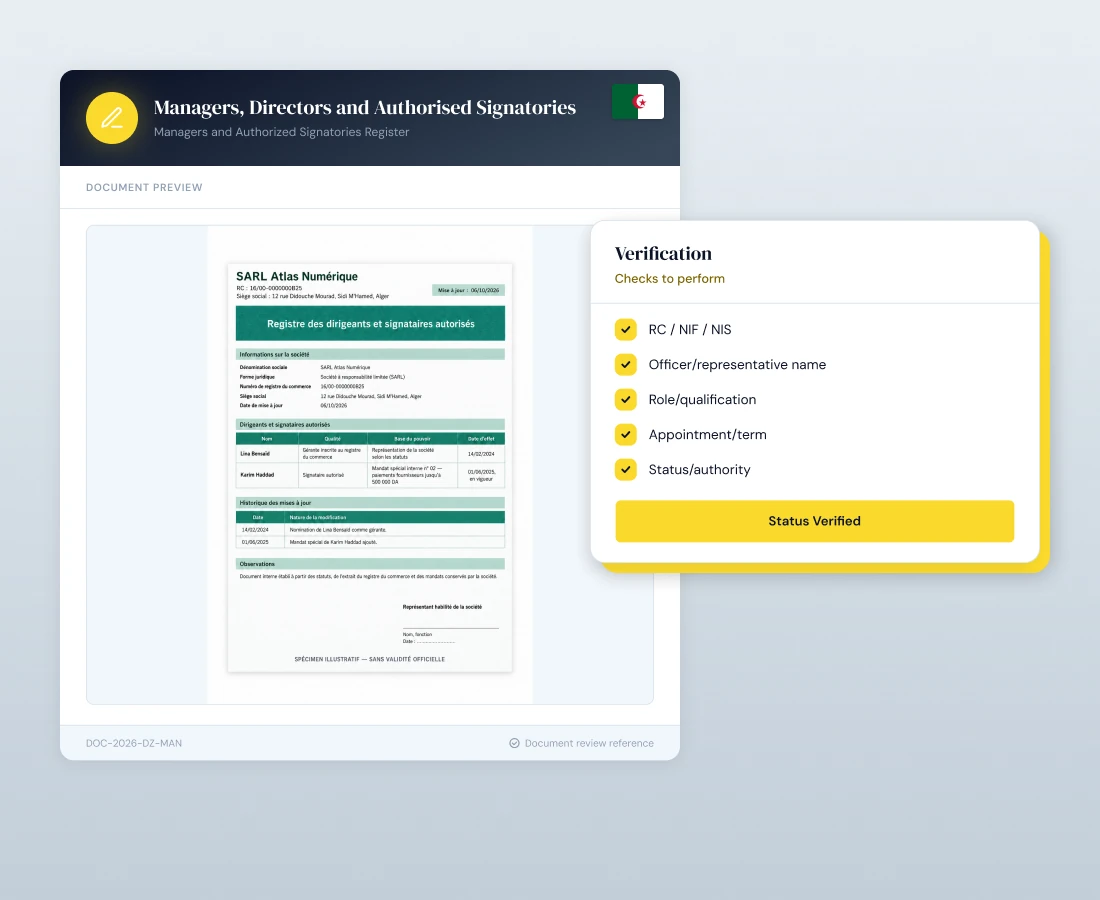
Managers, Directors and Authorised Signatories
Shufti verifies the identity of each gérant, director and authorised signatory, screens them against sanctions and PEP lists, and sends an alert when the commercial register shows a change in management.
Languages We Cover
Arabic, French and Expat Document Parsing
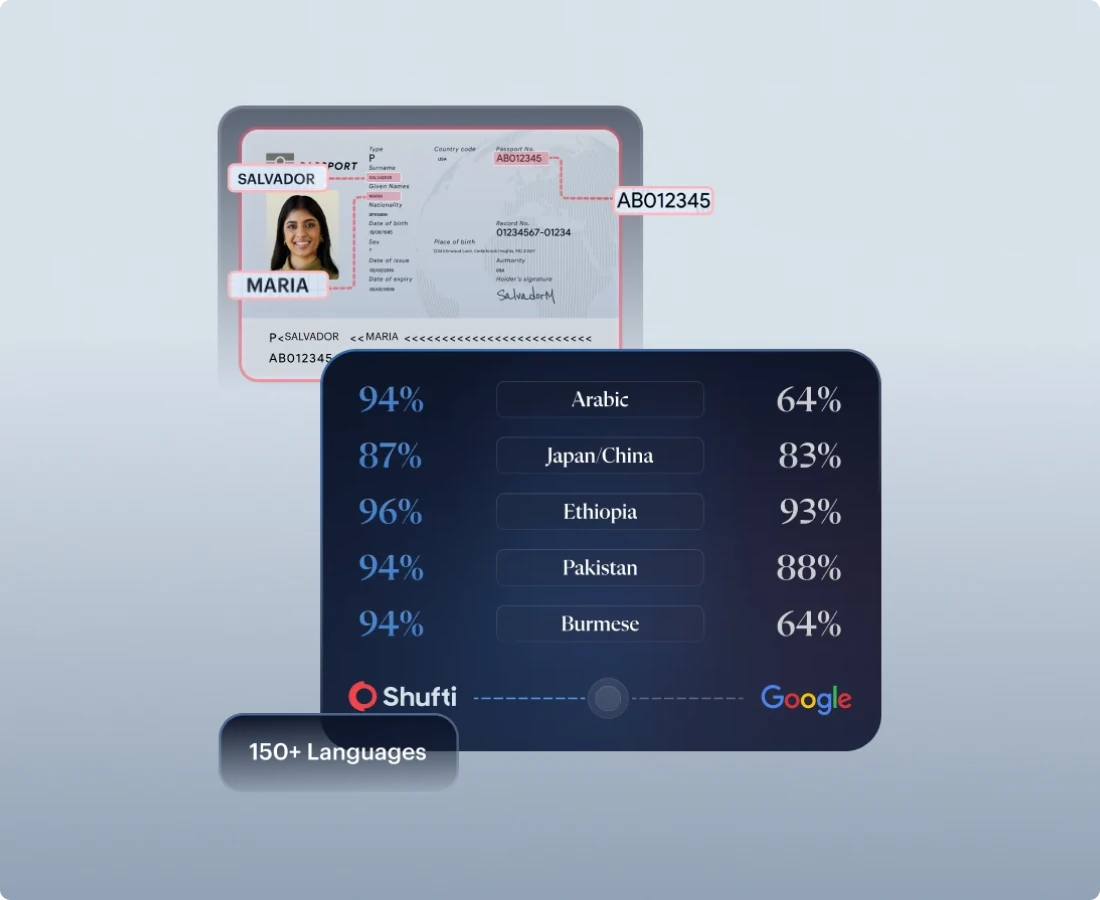
Algerian documents carry Arabic and Latin-script fields, and foreign customers bring documents in many other scripts. Shufti's OCR reads 150+ languages and scripts at 99.7% accuracy and scores 94% on Arabic documents against Google Vision's 64%. Zero-shot document intelligence extracts data from layouts it has never seen, on first sight, without waiting for a template.
Algerian Name Matching
One Algerian name can appear in Arabic, in French transliteration and in English spellings across documents and lists. Shufti's phonetic and transliteration models match these variants in sanctions and PEP screening, so spelling neither hides a true match nor raises a false one.
Cross-Document Consistency Checks
Shufti reconciles names, dates of birth and the national identification number across the CNIBE, passport, driving licence, commercial register extract and beneficial owner register entries, so a mismatched record surfaces before an analyst approves the customer.
Independent Validation
Shufti's Recognition Across Independent Evaluations
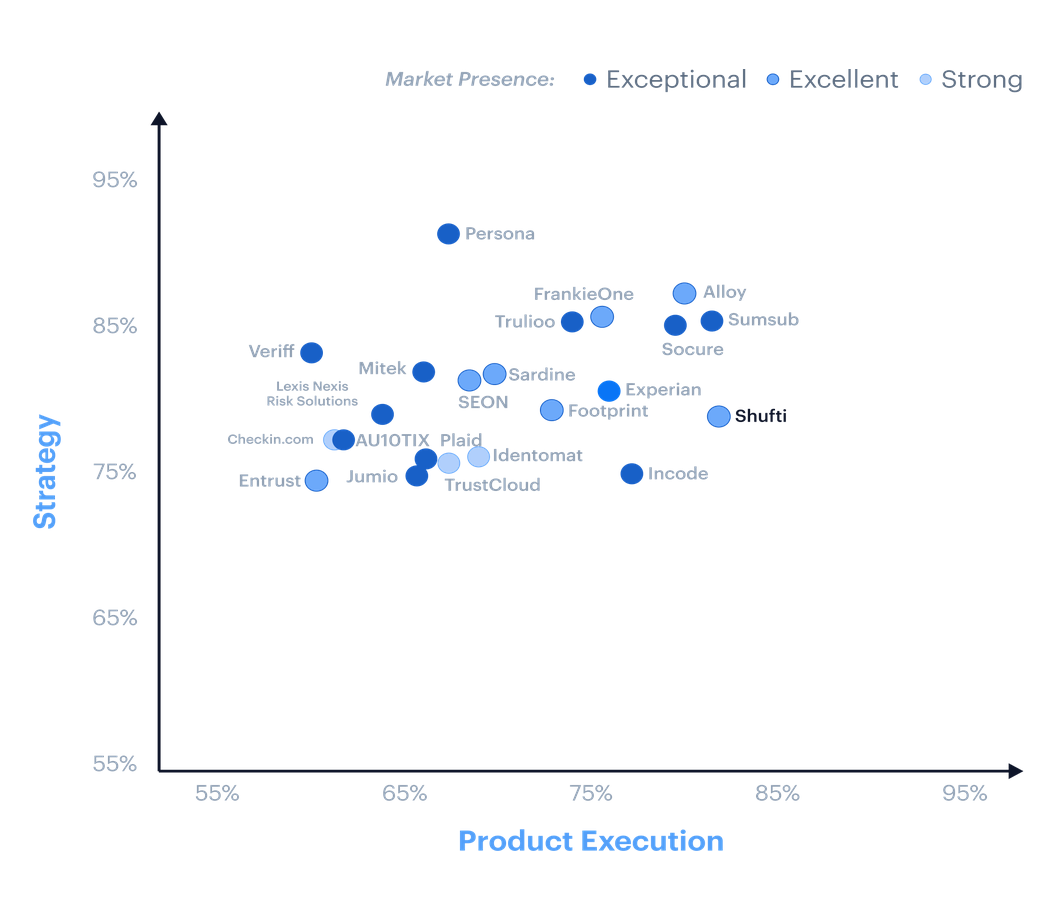
Ranked Exceptional in the Liminal Index 2026 for age estimation
View Report
Differentiated by Gartner on document diversity and country coverage
Read more
Certified at iBeta Level 3 PAD with 0% APCER
Read Blog
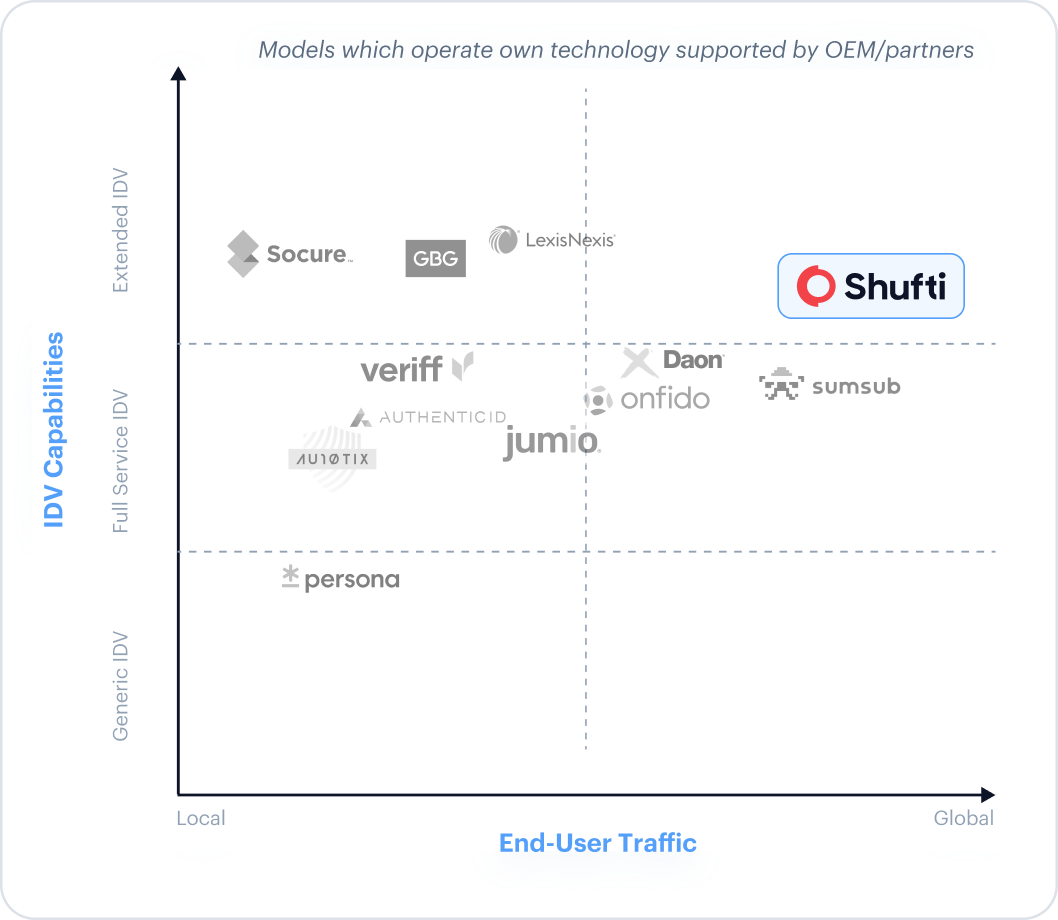
Broadest global reach in the 2025 KuppingerCole Extended IDV report
Download Report
Ranked Top 5 in the DHS RIVR 2025 for identity validation
Read Blog
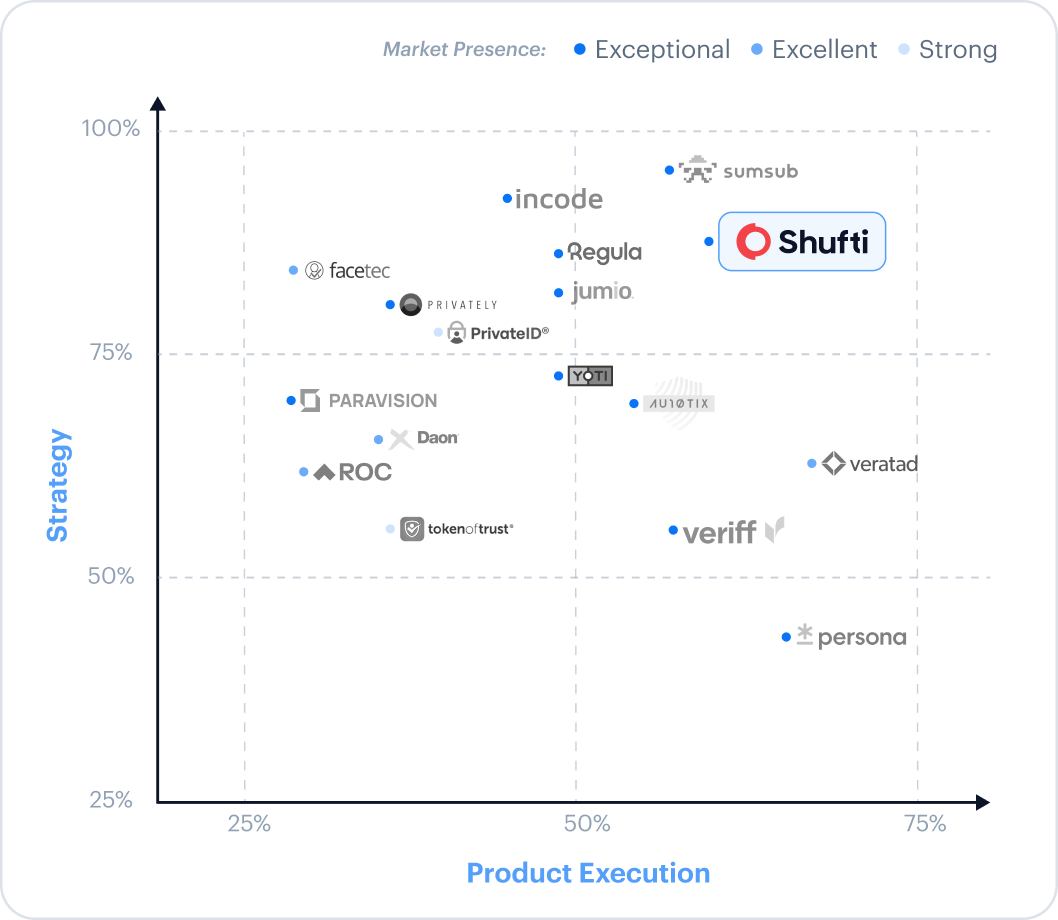
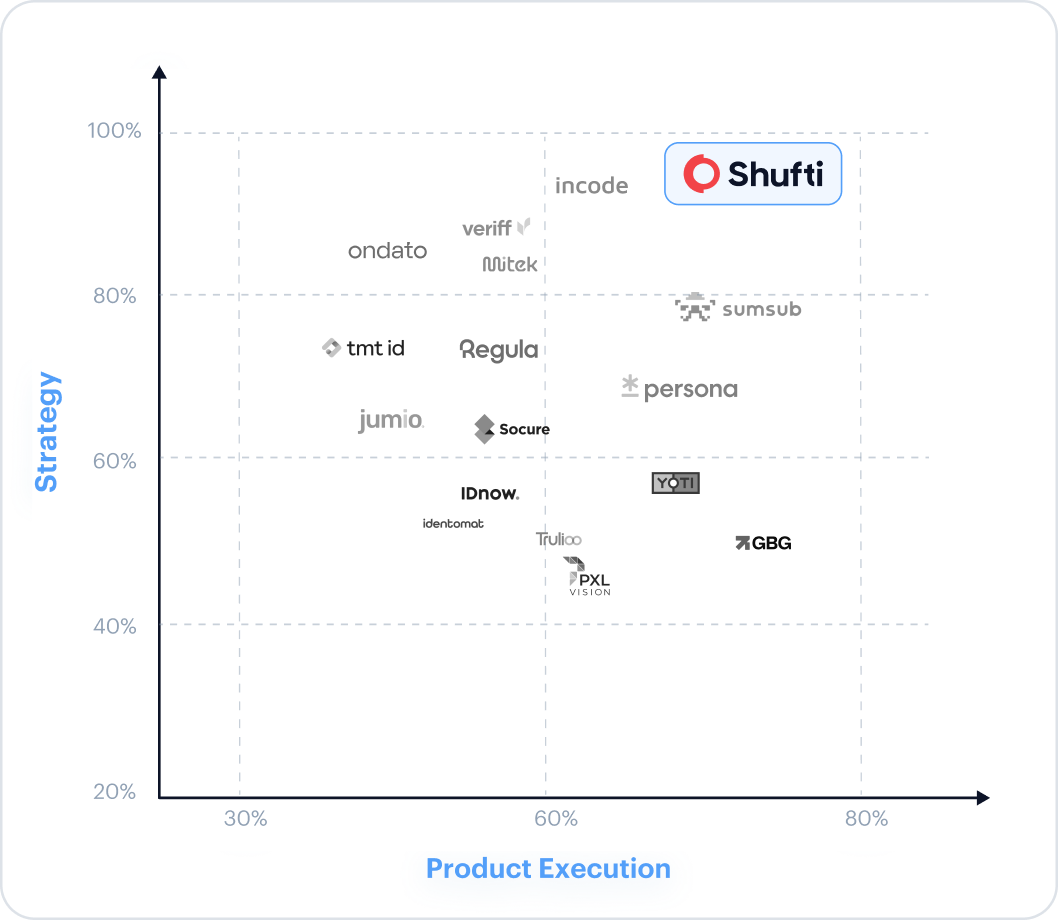
Top Vendor for Product Execution in the Liminal Index for KYC 2026
View Report
Ranked Exceptional for age verification by Liminal Index 2026
View Report
Recognised as a Leader in G2 Fall 2026 reports
Read More
Regulatory Update
Every Verification Route Algerian Firms Rely On, in One Platform
Article 10 bis 6 of Law 05-01 requires special and sufficient measures whenever a customer is not physically present for identification, without naming a specific route. Shufti supports every route Algerian firms use to meet that standard, from CNIBE chip reads to document, biometric and video routes for non-residents and customers without a CNIBE.
Passport NFC Chip Verification
LiveShufti reads the chip in the Algerian biometric passport and in most foreign biometric passports, giving expats and non-residents a chip-backed remote route when they hold no CNIBE, with the chip photo matched to a live selfie.
Document and Face Biometric
LiveThe customer photographs an ID and takes a selfie. Shufti runs forensic document checks, iBeta Level 3 certified liveness and a face match, the route most foreign customers and non-residents take.
Video Identification
LiveAn agent verifies the customer over a recorded video session, run in the language your customers use, for customers who need a live check or fail an automated route. The full session is stored in the case file as evidence.
Fraud Prevention Across the Algeria Customer Journey
Reduce fraud losses and protect customer trust across onboarding, account access, and payments. Shufti connects identity, behavioral, device, network, and transaction intelligence to help Algerian businesses act on risk while keeping legitimate customers moving.
Governance & Controls
Audit-Ready Decisions, Lower Operational Drag
Fewer Avoidable Re-submissions
Live capture guidance for the CNIBE, passport and Arabic-script documents catches glare, blur and cropping before submission, so fewer customers are asked to try again.
Cleaner Audit Trails
Shufti's case management records sources, results, timestamps, evidence, analyst notes and decision history, packaged as report-ready bundles for STR filing through the CTRF's e-DS platform.
One Workflow, One Back Office
Unify KYC, KYB, AML screening and transaction monitoring in one case file. Perpetual KYC/KYB tracks ownership, director and transaction changes, managing the full compliance lifecycle.
CNIBE-First Flow Design
Residents verify through the CNIBE chip first, while foreign nationals move to passport verification in the same flow, with no separate journey to build.
Shufti's IDV/KYC Solutions for Algeria
KYC Solutions
Identity verification in Algeria covers residents with a CNIBE, foreign nationals with a residence card and non-residents onboarding from abroad. One Shufti flow routes each by risk, so nobody faces checks they don't need.
Explore More
Face Verification
Remote onboarding has to prove that the person holding the CNIBE is the person on camera. Shufti matches a live selfie to the chip or document photo with iBeta Level 3 liveness and a false match rate below 0.001, so impersonation fails early.
.
Age Verification
Age-restricted services need to confirm a customer's age without slowing sign-up. Shufti estimates age from a selfie in under 5 seconds and falls back to the date of birth on the CNIBE or passport when the estimate is close to the limit.
.
Bank Account Verification
Payouts sent to an account that does not belong to the customer are hard to recover. Shufti validates the bank account details and matches the account-holder name in real time, so funds reach the verified person and nobody else.
.
Address Verification
Address proof in Algeria arrives as utility bills, bank statements and residence certificates in Arabic or French. Shufti's layout-aware extraction reads each format and fuzzy-matches the address to the ID, with a 99.3% pass rate.
.
Document Verification
Law 24-02 punishes forging an identity, travel or residence document with up to seven years in prison, yet forgeries still reach onboarding queues. Shufti verifies Algerian and foreign documents within seconds, so a fake is rejected before any analyst sees it.
.
Identity Verification
Different customers need different proof, from a chip read to a video call. Shufti runs document, biometric, NFC and address checks in one API session, so each Algerian customer completes a single journey and your team gets one result.
.KYB Solutions
Algerian companies register with the CNRC, declare their beneficial owners to the same body and often sit under holding structures. Shufti checks the commercial register live and maps ownership to the threshold set by Executive Decree 26-163.
Explore More
Business Verification
Onboarding an Algerian company means confirming its commercial register extract, NIF, signatories and everyone who owns or controls 20% or more. Shufti's live registry call pulls that picture together in one check, putting corporate onboarding under two minutes.
.
Enhanced Due Diligence
Law 05-01 requires enhanced measures for high-risk customers and politically exposed persons, including source of funds and senior approval before the relationship starts. Shufti's branching due diligence forms collect that evidence, score the answers and route the case to the decision-maker.
.AML Screening
A customer who is clean at onboarding can land on a list next week. Shufti's perpetual KYC rescreens every customer against 4,000+ watchlists, including Algeria's national list of terrorist persons and entities and UN Security Council lists, refreshes the data every 15 minutes and keeps each alert in one case file.
Explore More
Business AML Screening
Sanctions exposure often sits with an owner, not the company. Shufti screens every owner, director and signatory against sanctions lists, including Algeria's national terrorist list, PEP and adverse media sources and rescreens the portfolio through perpetual KYB, so a new designation surfaces the day it is published.
.
Transaction Monitoring
Article 10 bis 4 of Law 05-01 requires scrutiny of transactions throughout the relationship. Shufti's library of 500+ pre-built rules covers structuring, smurfing and mule activity, cuts false positives by up to 60% and builds case bundles ready for reporting to the CTRF.
.
AI Compliance Co-Pilot
One common name can return 140+ screening hits, and Arabic transliteration multiplies them. Shufti's AI Compliance Co-Pilot reviews each hit, gives a confidence score and a written reason, and leaves the final call with your compliance officer.
.Built To Fit Algeria's Compliance Landscape
Law 05-01 and the CTRF set AML duties for every reporting entity in Algeria, while the Bank of Algeria, COSOB, the insurance supervisor and sector authorities add rules of their own. Shufti maps its KYC, KYB, AML screening and transaction monitoring controls to every regime below, so one platform covers each license your group holds.
Law 05-01 on Money Laundering and Terrorist Financing
Amended most recently by Law 25-10 of 24 July 2025, the law requires customer and beneficial owner verification under Article 7, ongoing scrutiny under Article 10 bis 4, records kept for at least five years under Articles 14 and 10 bis 7, and suspicious transaction reports under Article 20.
Bank of Algeria and the Banking Commission
Under Monetary and Banking Law 23-09, the Banking Commission supervises banks, financial institutions, payment service providers and bureaux de change. Regulation 24-03 of 24 July 2024 replaced Regulation 12-03 and sets the risk-based approach, beneficial owner rules, PEP measures, transaction monitoring systems and record keeping.

Financial Intelligence Processing Unit (CTRF)
Algeria's CTRF is an independent administrative authority under the Ministry of Finance, governed by Executive Decree 22-36. It receives suspicious transaction reports through the e-DS secure online platform, disseminates lists of high-risk countries and issues guidelines on freezing and targeted financial sanctions to reporting entities.
Stock Exchange Operations Organisation and Surveillance Commission (COSOB)
COSOB Regulation 24-01, published in October 2024, sets AML duties for capital market intermediaries. It requires identification of each client, beneficial owner and agent under Articles 16 and 17, applies the same rules to remote securities account opening under Article 26 and requires five-year retention under Article 46.
Insurance Supervision Commission (CSA)
The CSA, attached to the Ministry of Finance, supervises insurers, reinsurers and insurance brokers. Its Regulation No. 01 of 6 November 2024, amended in October 2025, sets AML and counter-terrorist financing duties for the sector, backed by guidelines on asset freezing, beneficial owners, politically exposed persons and high-risk countries.
National Centre of the Commercial Register (CNRC)
The CNRC keeps the commercial register and the public register of beneficial owners. Executive Decree 26-163 requires companies to declare owners within 30 days of incorporation or any change, confirm the data before 31 December each year and give reporting entities access to the data for their due diligence.
Supervisors of Designated Non-Financial Businesses
Article 10 bis 3 of Law 05-01 names a supervisor for each profession. The national bar council oversees lawyers, the national chambers oversee notaries and bailiffs, the Ministry of Housing oversees real estate agents, and the Ministry of Finance oversees dealers in precious metals and stones.
Ministry of Interior, Local Authorities and Territorial Planning
The ministry issues the CNIBE under Presidential Decree 17-143, which provides one chip for holder data and one for an authentication application, valid for ten years for adults. Executive Decree 23-316 sets the 18-digit national identification number and limits its interconnection system to public administrations.
Law 26-02 on Trust Services and Electronic Identification
Adopted on 17 February 2026, Law 26-02 replaced the 2015 electronic signature and certification law. It sets low, substantial and high assurance levels for electronic identification means, requires certification of those means and creates a single national electronic certification authority to oversee trust service providers.
National Terrorist List and Targeted Financial Sanctions
Executive Decree 25-101 requires reporting entities to freeze funds of persons on UN Security Council lists without delay, within 24 hours of UN publication. Algeria's national list of terrorist persons and entities falls under Executive Decree 25-103 and is published in the Official Journal and on the CTRF website.
National Committee for ML/TF Risk Assessment
Created by Executive Decree 20-398, the committee assesses money laundering, terrorist financing and proliferation financing risks. Its first national risk assessment, published in June 2024, rated the money laundering threat medium-high. The FATF removed Algeria from its increased monitoring list in June 2026 after successful on-site visits.
Algeria Data Residency and Deployment
Clients choose cloud hosting on AWS or Azure, or an on-premises deployment inside Algeria delivered through local partners, which keeps identity data within the client's own infrastructure. Hosting locations, transfer arrangements and any ANPDP authorisation they need are defined in each client agreement.
Law 18-07 on Personal Data Protection
Law 18-07, enforced by the ANPDP and amended by Law 25-11 in July 2025, requires prior declaration of processing, a contract with each processor and ANPDP authorisation for transfers abroad. Shufti applies encryption, role-based access controls and configurable retention to identity and biometric data.
Data Protection Officer and Processing Records
Law 25-11 requires every controller to appoint a data protection officer and keep a register of processing activities. Shufti supports both with an audit log of each verification, a data processing agreement and documentation of the processing it performs for the client.
Retention Controls
Law 05-01 and Regulation 24-03 set a five-year minimum after a relationship ends, and that minimum is not an automatic deletion date. Shufti's retention is configurable by client and license, with legal holds for records linked to an investigation or a CTRF request.
Encryption and Security
Shufti encrypts data in transit and at rest, enforces role-based access and keeps audit logs of every action. Its ISO 27001:2022 certification and SOC 2 Type 2 reports give banks and their auditors the evidence a vendor risk assessment asks for.
Automated Decisions and Biometric Data
Law 25-11 added definitions of biometric data and profiling to Law 18-07. Shufti returns verification results and supporting details through the API and back office, so support teams can explain outcomes and escalate disputed results to a human reviewer.
Scope of Our Role
Shufti processes personal data only on the client's documented instructions as a processor (sous-traitant) under Law 18-07, while the client remains the controller responsible for its own compliance. Shufti's privacy notice identifies any activity where it acts as an independent controller.
Data Residency and Privacy Controls in Algeria
Algeria AML Sources That Strengthen Decisions
Financial Intelligence Processing Unit (CTRF)
Bank of Algeria and the Banking Commission
Stock Exchange Operations Organisation and Surveillance Commission (COSOB)
Insurance Supervision Commission (CSA)
Directorate General of Taxes (DGI)
Directorate General of Customs (DGD)
Directorate General of National Assets (DGDN)
Directorate General of the Treasury and Accountancy (DGTC)
General Inspectorate of Finance (IGF)
Central Office for the Repression of Corruption (OCRC)
Financial Action Task Force (FATF)
Middle East and North Africa Financial Action Task Force (MENAFATF)
Egmont Group of Financial Intelligence Units
International Monetary Fund (IMF)
United Nations Office on Drugs and Crime (UNODC)
Turn Algeria Verification Requirements into a Smoother Customer Journey
Share your customer types, risk rules and current onboarding process. A Shufti specialist will show you how to connect identity verification, KYB and ongoing monitoring, reducing operational hand-offs while keeping decision evidence organised for compliance review.
INDEPENDENTLY AUDITED. GLOBALLY CERTIFIED.
Certified to Global Standards



PROVEN WORKFLOWS
Identity Verification Built Around Your Industry in Algeria
Meet Regulation 24-03 From Onboarding To Monitoring
Banks must verify every customer and beneficial owner, refresh files by risk and block prohibited virtual-asset operations under Bank of Algeria Regulation 24-03. Shufti combines CNIBE chip checks, KYB on CNRC-registered firms, perpetual screening and transaction monitoring in one back office, with case files ready for Banking Commission inspections.
Frequently Asked Questions
Can Algerian customers verify remotely without a government login?
Yes. No government identity login is currently open to private firms in Algeria, so Shufti reads the CNIBE chip through the customer's phone and matches a live selfie. Customers without a CNIBE use passport NFC, document and face biometrics or an agent-led video session.
Is a CNIBE image enough, or should verification include its chip?
An image shows that a card looks right, not that it is genuine. Shufti reads the holder data stored on the CNIBE chip over NFC and compares it with the printed fields and a live selfie, which exposes cloned, altered or borrowed cards.
Can Shufti verify foreign documents or identity formats it has not encountered before?
Yes. Shufti's zero-shot document AI reads unfamiliar layouts on first sight, without a template, so a foreign worker's or investor's ID gets the same forensic checks as a CNIBE, including newly issued formats that have no training history yet.
How does Shufti OCR compare with Google OCR for Arabic identity documents?
In Shufti's published comparison, its OCR reached 94% accuracy on Arabic documents where Google Vision reached 64%. Shufti also reads the Latin-script fields on Algerian documents, so names and numbers extracted from both scripts line up in the case file.
How does Shufti verify ownership when an Algerian company has several corporate layers?
Shufti traces ownership through each holding company using statutes, shareholder records and CNRC beneficial owner data, then identifies every natural person holding 20% or more of capital or voting rights, or exercising control by other means, and screens each one.
Does Shufti's ongoing monitoring cover more than sanctions screening?
Yes. Shufti compares each transaction with the customer's profile, tracks ownership and director changes, and triggers a review when risk rises. That covers the ongoing scrutiny Law 05-01 requires, plus the yearly review cap for high-risk customers, alongside continuous sanctions and PEP screening.
How does Shufti keep screening current and handle Algerian name variations?
Shufti updates sanctions, PEP and adverse media data throughout the day, including Algeria's national terrorist list and UN lists that must be applied within 24 hours. Phonetic models match Arabic names across French and English spellings, so a transliteration difference does not hide a match.
Can we run verification inside our own infrastructure in Algeria?
Yes. Shufti offers on-premises deployment through local partners, including air-gapped setups, so identity data stays inside your environment. Cloud hosting on AWS or Azure is also available, with the hosting location and any ANPDP transfer authorisation reflected in the agreement.
What controls help us protect identity and biometric data?
Biometric templates and document images are encrypted, access is limited by role and logged, and retention is set per client. A data processing agreement documents Shufti's processor role, which supports your declarations to the ANPDP and the security duties in Law 18-07.
Can we configure different retention periods for different Algerian licenses?
Yes. Retention can be set by license, product and record type. A bank under Regulation 24-03 and a broker under COSOB Regulation 24-01 can each keep records for at least five years after the relationship ends, with longer periods or legal holds where needed.
What does Shufti provide when our compliance team needs to prepare an e-DS report?
Shufti exports the identity evidence, screening results, transaction history and analyst notes behind each alert as one report-ready bundle. Your compliance officer uses it to complete the suspicious transaction report on the CTRF's e-DS platform without rebuilding the case from separate systems.
Can we add verification checks without rebuilding our onboarding journey?
Yes. Shufti's AI Journey Builder adds or reorders checks, such as CNIBE NFC, address proof or enhanced due diligence questions, through configuration. Existing API integrations keep working, so a new rule for a product or risk tier goes live without new development work.
How does Shufti make verification queries easier for our customer support team?
The back office shows each verification step, the reason a check failed and the evidence behind it. Support agents can explain outcomes in plain terms, ask for a specific resubmission and pass disputed results to compliance without raising a ticket with engineering.
Let’s Build Trust Into Your Business
1B+Verifications Processed
240+Regions Actively Processed
99.7%Accuracy Rate
Samer Al Tamimi
CEO of Safwa Bank
“We take our client’s privacy very seriously and always look for new innovative solutions to ensure a safe banking experience. Working with Shufti feels like a breath of fresh air, as their 100% in-house tech keeps our customer’s data free from vulnerabilities and fully safe and protected.”
Trusted. Compliant. Certified
Explore Shufti For Your Business
Get a personalised demo from our experts.
PROVEN PLAYBOOKS
Explore Practical KYC & AML Resources
23 September, 2025
AML Screening: Middle East & Africa (MEA)
Gulf regulators are raising AML fines and FATF scrutiny, and Arabic transliteration trips up generic tools. How Shufti screens names accurately across MEA.
Regional Brief