

 AMLR Solutions
 AMLR Consultation
 EUDI Wallet
 Onboarding
 Ongoing Monitoring
 FRAML
 KYC
 KYB
 KYI
 Age Assurance
 Workforce IAM
 Candidate Verification
 Account Takeover
 Bonus/ Promotion Abuse
 Chargeback Fraud
 Deepfake
 Document Fraud
 Fraud Networks
 Impersonation Fraud
 Money Mule Activity
 Multi-Accounting
 Party Fraud
 Regulatory & Compliance Risks
 Synthetic Identity Fraud
 Adult Content
 Banking
 Crypto
 Fintech
 Forex
 Compliance
 Fraud prevention
 Trust & safety
 Global expansion
 Compliance Officers
 Developers
 Fraud Analysts
 Product Managers
 Journey Builder
 Global Trust Platform
 Customer Profiles
 Vendor Comparison
 IDV Case Management
 AML Case Management
 Regulatory Reporting
 Agentic Rule Builder
 AI Compliance Co-Pilot
 Fraud Analytics
 Fraud Hub
 OCR
 Shufti AI
 Bank Account Verification
 Biometric Duplication
 Database Checks
 Document Intelligence
 Government ID
 Mobile Driver's License
 NFC
 Selfie Liveness
 Brand Personalisation
 Deployment Options
 Identity Methods
 IDV Modes
 Multi-tenancy
 On-Premise IDV
 Secure Capture
 Shufti MCP


- Afghanistan
- Albania
- Algeria
- Andorra
- Angola
- Argentina
- Armenia
- Australia
- Austria
- Azerbaijan
- Bahrain
- Bangladesh
- Belarus
- Belgium
- Belize
- Bolivia
- Bosnia and Herzegovina
- Brazil
- British Virgin Islands
- Brunei
- Bulgaria
- Cambodia
- Cameroon
- Canada
- Chile
- China
- Colombia
- Costa Rica
- Croatia
- Curaçao
- Cyprus
- Czech Republic
- Denmark
- Dominican Republic
- Ecuador
- Egypt
- El Salvador
- Estonia
- Eswatini
- Ethiopia
- Finland
- France
- Germany
- Greece
- Haiti
- Hong Kong
- Hungary
- India
- Iraq
- Ireland
- Indonesia
- Italy
- Japan
- Jordan
- Kazakhstan
- Kenya
- Kosovo
- Kuwait
- Latvia
- Lithuania
- Luxembourg
- Malaysia
- Malta
- Mauritius
- Mexico
- Micronesia
- Moldova
- Monaco
- Mongolia
- Montenegro
- Morocco
- Mozambique
- Myanmar
- Namibia
- Nauru
- Nepal
- Nigeria
- Nicaragua
- Niue
- Norway
- Netherlands
- New Zealand
- Oman
- Pakistan
- Palau
- Palestine
- Panama
- Papua New Guinea
- Paraguay
- Peru
- Puerto Rico
- Philippines
- Portugal
- Poland
- Qatar
- Republic of Congo
- Romania
- Russia
- Rwanda
- Samoa
- San Marino
- Saudi Arabia
- Senegal
- Serbia
- Seychelles
- Sierra Leone
- Singapore
- Slovakia
- Slovenia
- Somalia
- South Africa
- South Korea
- South Sudan
- Spain
- Sri Lanka
- St Kitts and Nevis
- St Maarten
- St Lucia
- Sweden
- Switzerland `
- Syria
- Taiwan
- Tajikistan
- Tanzania
- Thailand
- Timor Leste
- Togo
- Tonga
- Trinidad and Tobago
- Turkey
- Turks and Caicos
- Turkmenistan
- Tunisia
- Tuvalu
- UAE
- Uganda
- Ukraine
- UK
- USA
- Vanuatu
- Vietnam
- Zambia
Scale Identity Verification and KYC Operations in Monaco
Verify Monegasque nationals and residents through MConnect digital identity, biometric passports and 10,000+ foreign ID document types, run KYB on RCI-registered companies and their beneficial owners, and monitor transactions and sanctions lists. One platform runs compliance and fraud prevention across the full customer lifecycle for AMSF-supervised firms.


Operational Performance for Monaco KYC
Our Numbers Speak Volumes
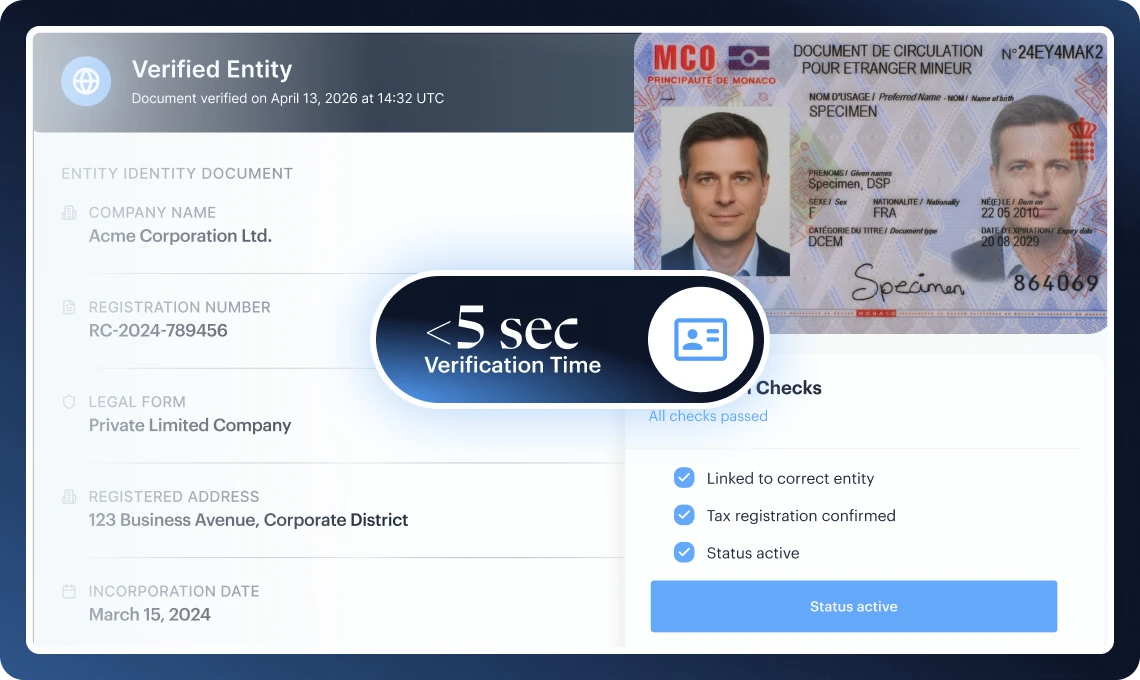
Under 5 secs
IDV
Verification
100%
Omni-format
Document Recognition
240+
Countries and
Territories Covered
Monaco IDV/KYC Challenges

Most Customers Onboard With Foreign Documents
KYC in Monaco starts with a mixed population. The 2025 census counted 144 nationalities among 38,857 residents, with Monegasque nationals at 24%, so most residents hold a foreign passport or ID. Shufti's zero-shot document intelligence verifies documents from 240+ countries, including formats it has never seen before.

Remote Onboarding Without Digital Identity Adds Extra Steps
Under Art. 13 of Law No. 1.362, a customer identified remotely without a qualifying electronic identity must provide copies of two official photo IDs and make a first payment from an account in their own name. Shufti runs both checks inside one onboarding session.

Grey-List Scrutiny Puts Every Report Under Review
FATF has listed Monaco under increased monitoring since June 2024, and since January 2024 AMSF has accepted suspicious transaction reports only through goAML. Under that scrutiny a thin case file weakens the report, so Shufti's case management builds report-ready bundles with every check and decision.

Beneficial Owner Records Must Match What Firms Find
Firms that pull an extract from the beneficial owner register must report any missing entry or discrepancy to the Direction du Développement Économique (Art. 22-2). Shufti's perpetual KYB flags registry, director and ownership changes as they happen, so mismatches surface before the next review.
Documents and Languages
Individual Documents Shufti Verifies in Monaco
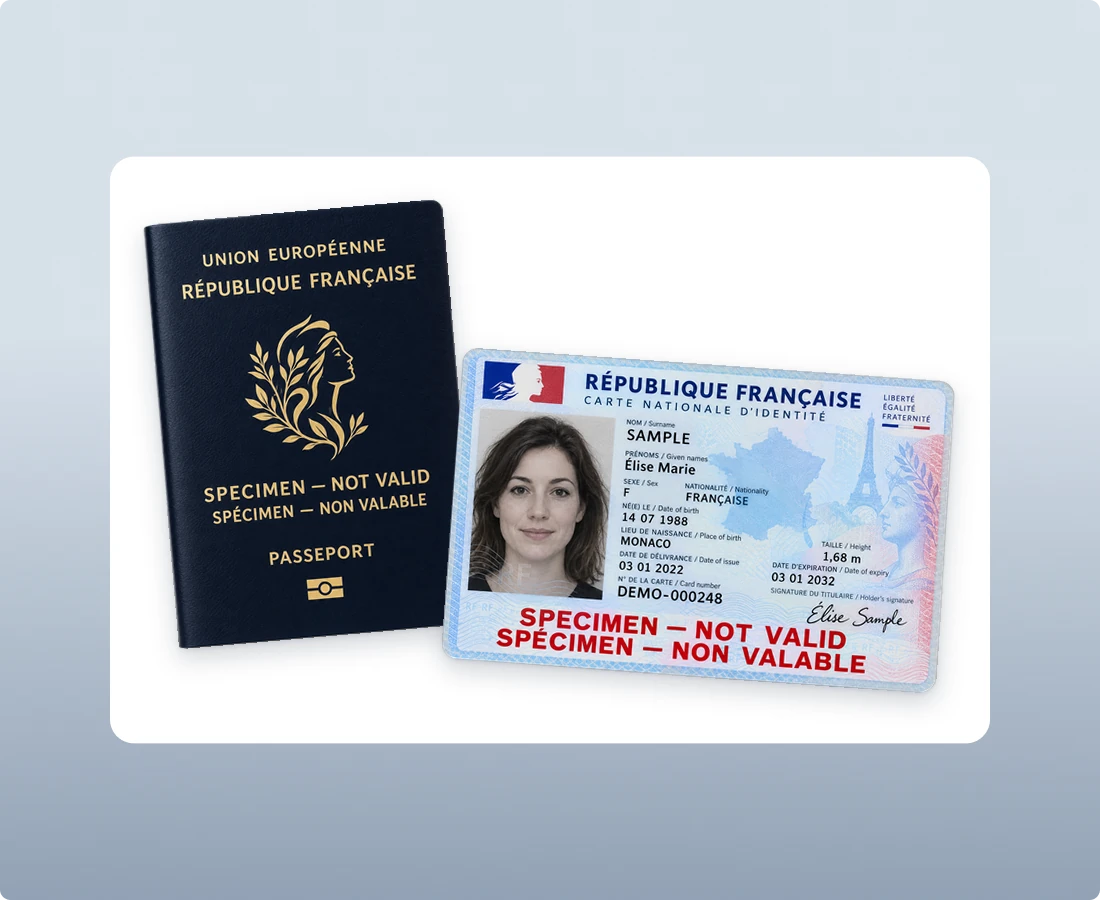
Shufti verifies Monaco's 2 core identity documents, the identity card and passport, plus residence cards, driving licences and passports and ID cards from other countries. The cards below cover the core documents Monaco onboarding relies on, with the full list on the supported documents page.
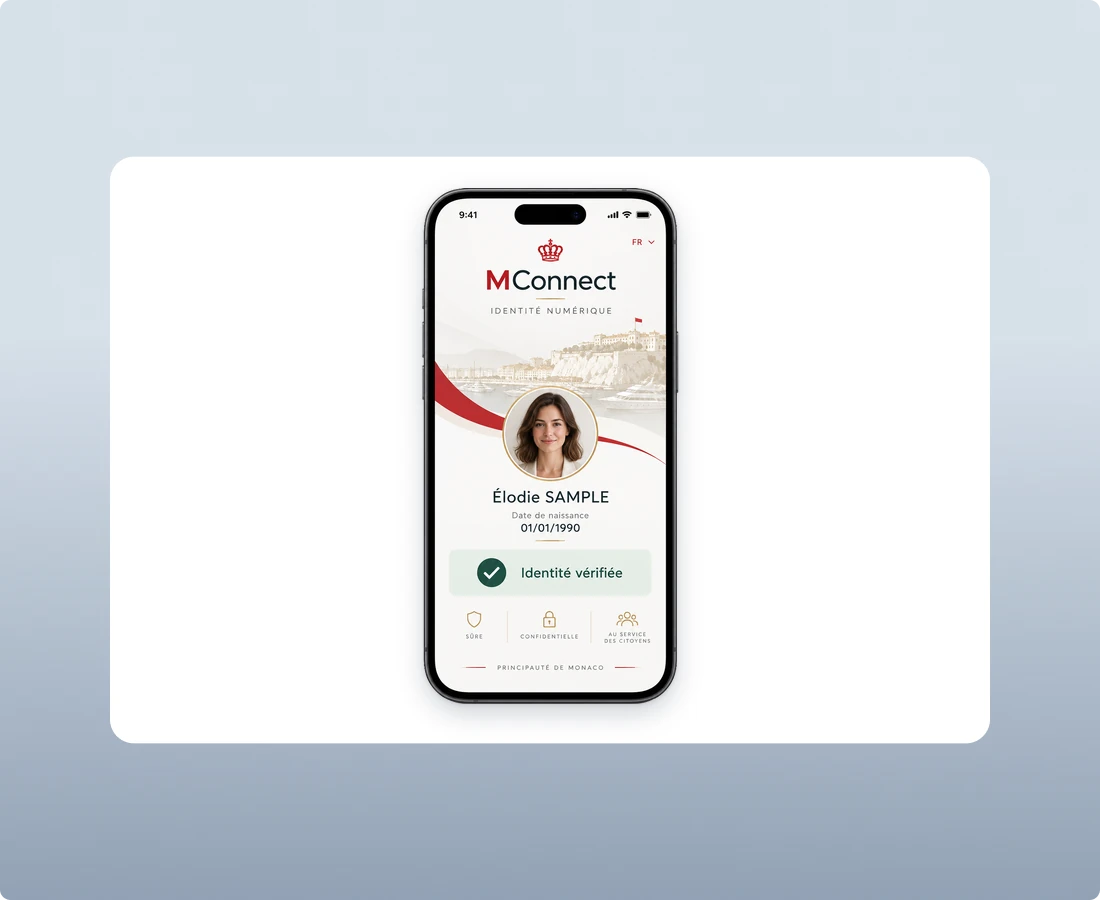
View All Supported DocumentsMonaco Digital Identity (MConnect)
Law No. 1.483 of 2019 gives every Monegasque national and residence card holder a high-assurance digital identity, carried on the card's chip and in the MConnect Mobile app. Shufti authenticates customers through your firm's MConnect partner integration and stores the verified name and date of birth in the case file.
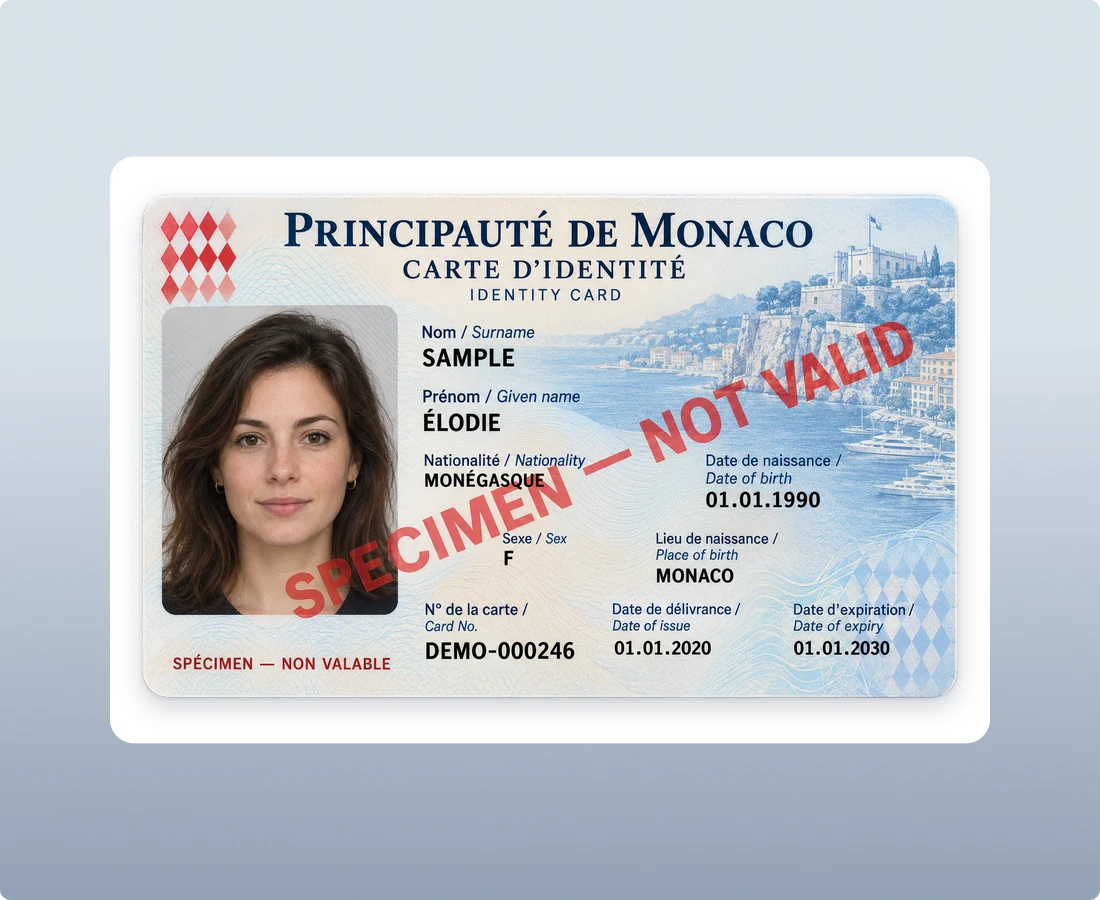
Monegasque Identity Card (Carte d'Identité Monégasque)
Issued by the Mairie de Monaco under Sovereign Ordinance No. 8.696 of 2021 and valid five years, with a chip whose data only authorised authorities may read. Shufti checks the card for tampering, matches the holder through biometric liveness and routes chip-based authentication through MConnect.
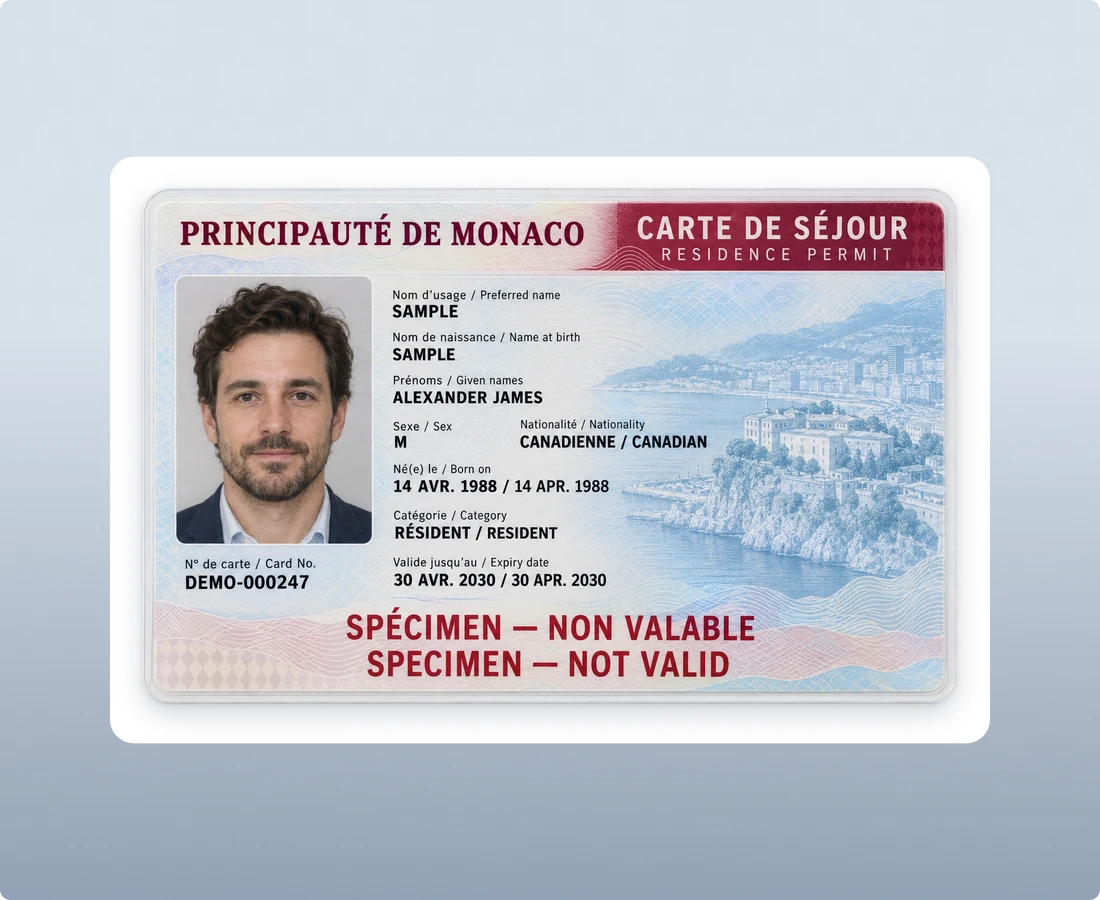
Residence Card (Carte de Séjour)
The Direction de la Sûreté Publique issues temporary, ordinary, privileged and spouse-of-a-Monegasque residence cards, each carrying the holder's digital identity. Shufti confirms the card's authenticity and expiry, then links it to the holder's passport and selfie in one session.
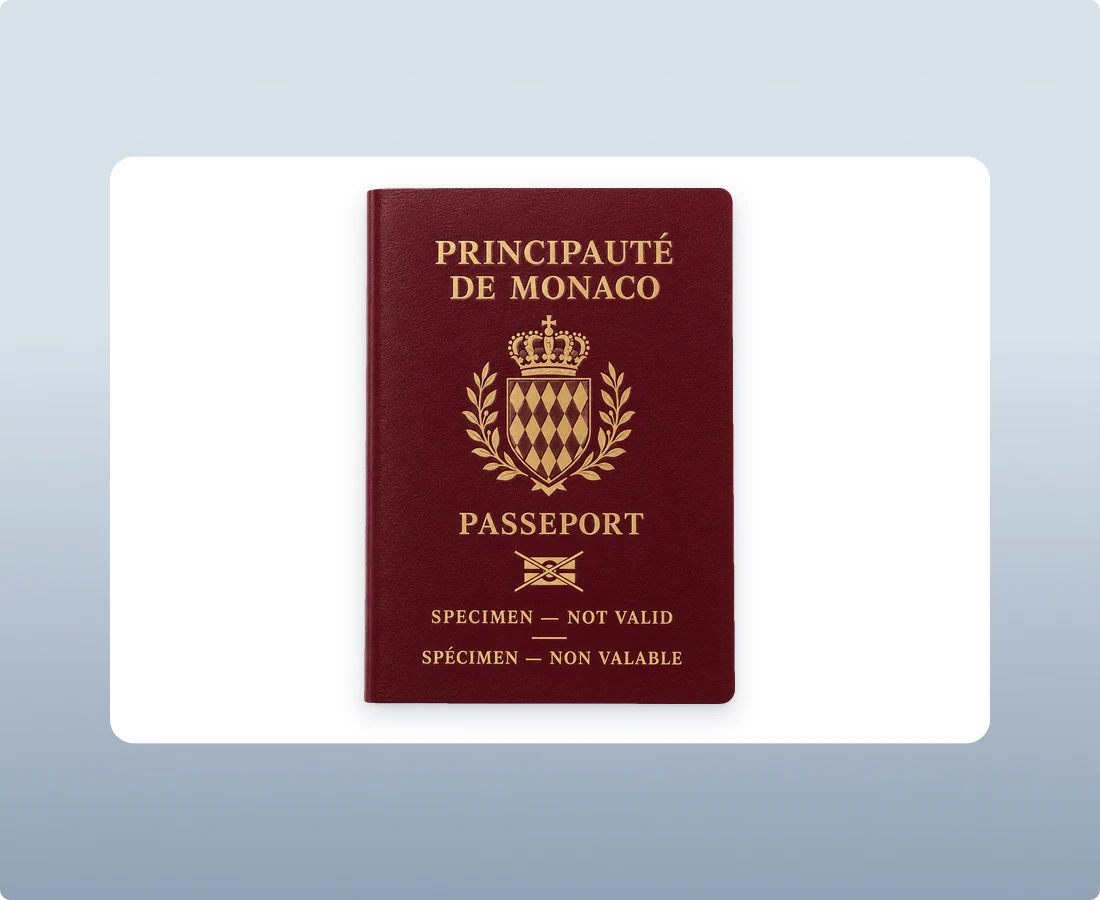
Monegasque Passport (Passeport Monégasque)
Monegasque nationals often present the passport as the second photo ID that remote onboarding without digital identity requires. Shufti reads the chip on biometric passports and runs nine forensic detection layers, from MRZ checksum validation to hologram analysis, so a cloned or altered passport fails before onboarding.
Foreign Passports and National ID Cards
Shufti actively processes 10,000+ ID document types from 240+ countries and territories, and its zero-shot AI learns new document formats in minutes. Foreign residents, private banking clients living abroad and buyers of yachts or property use these documents in the same flow.
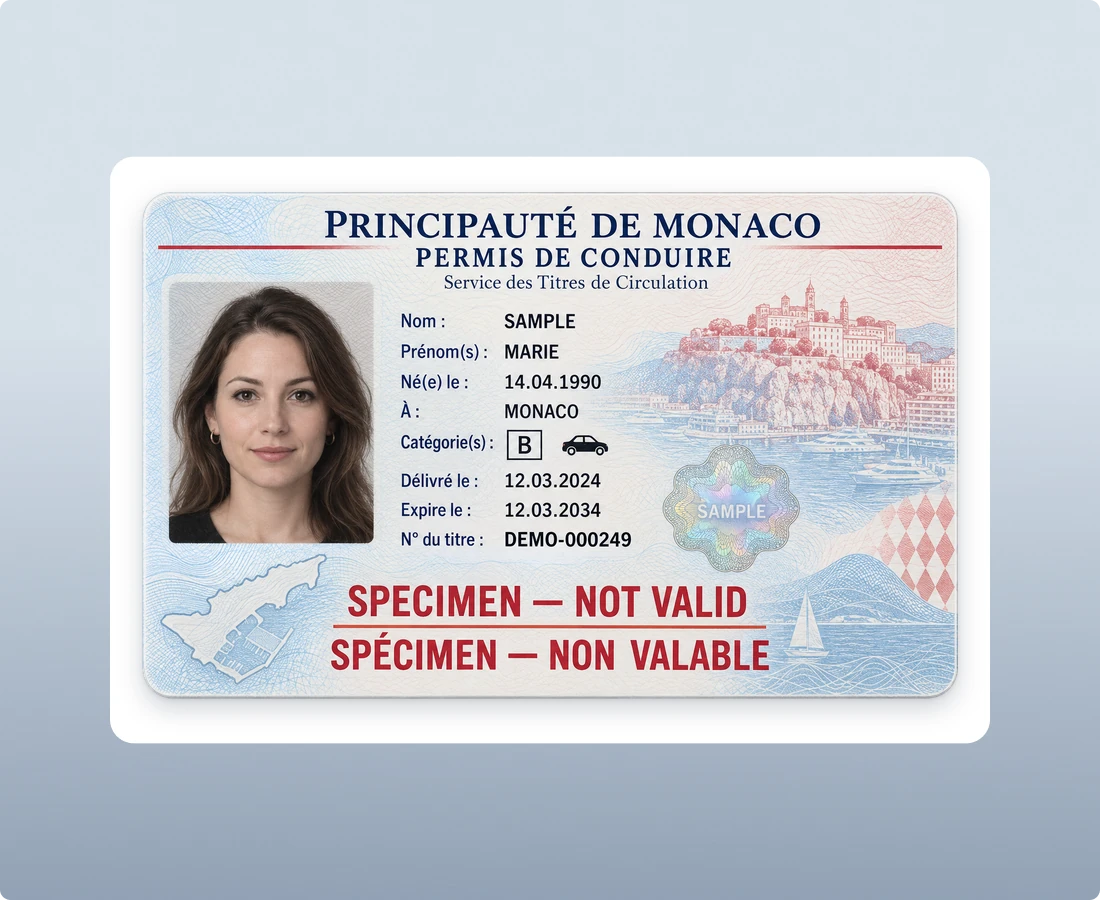
Monaco Driving Licence (Permis de Conduire)
Issued by the Service des Titres de Circulation, with a new bank-card format available since July 2026 and a 15-year renewal cycle. Shufti checks the licence's authenticity, expiry and photo match, and accepts it as a second photo ID where remote onboarding calls for one.
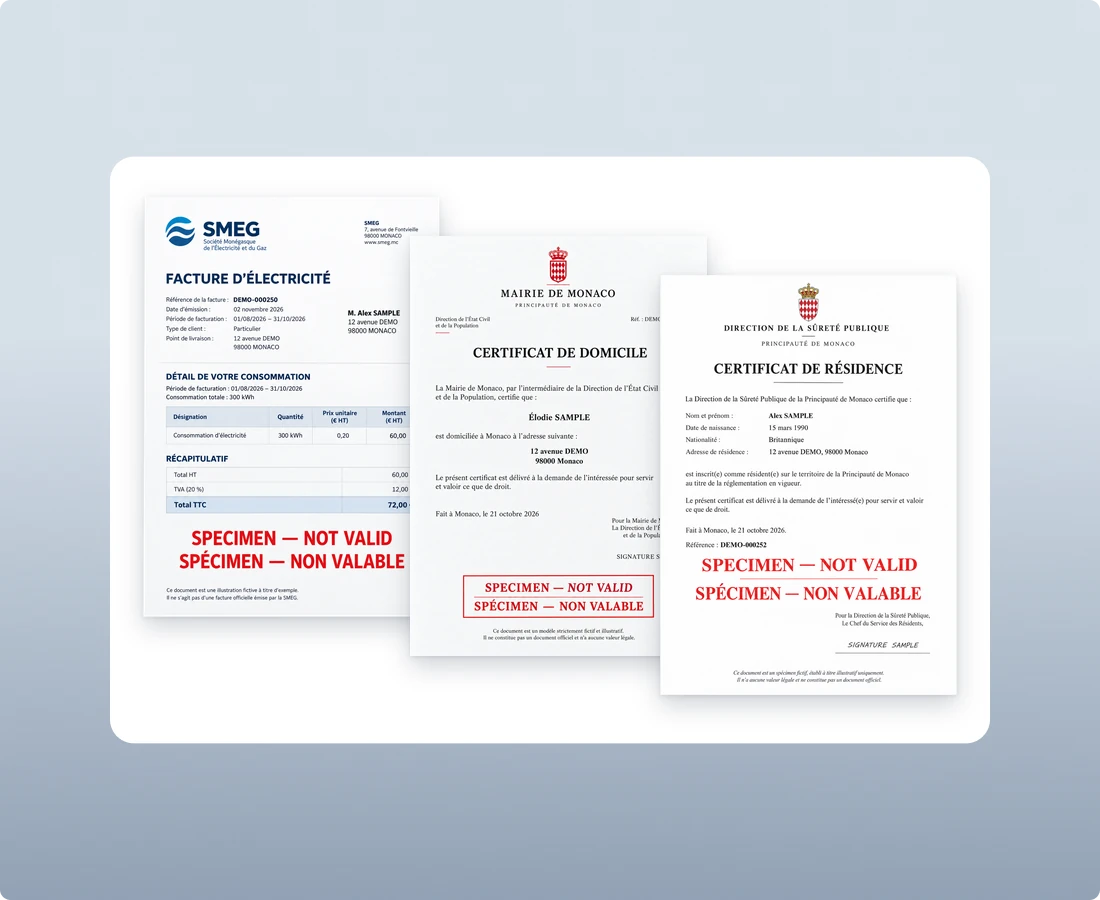
Proof of Address
Foreign residents obtain a certificat de résidence from the Direction de la Sûreté Publique, nationals a certificat de domicile from the Mairie, and SMEG utility bills show the current address. Shufti extracts the address from each document and matches it against the ID in the same step.
Entity Identity
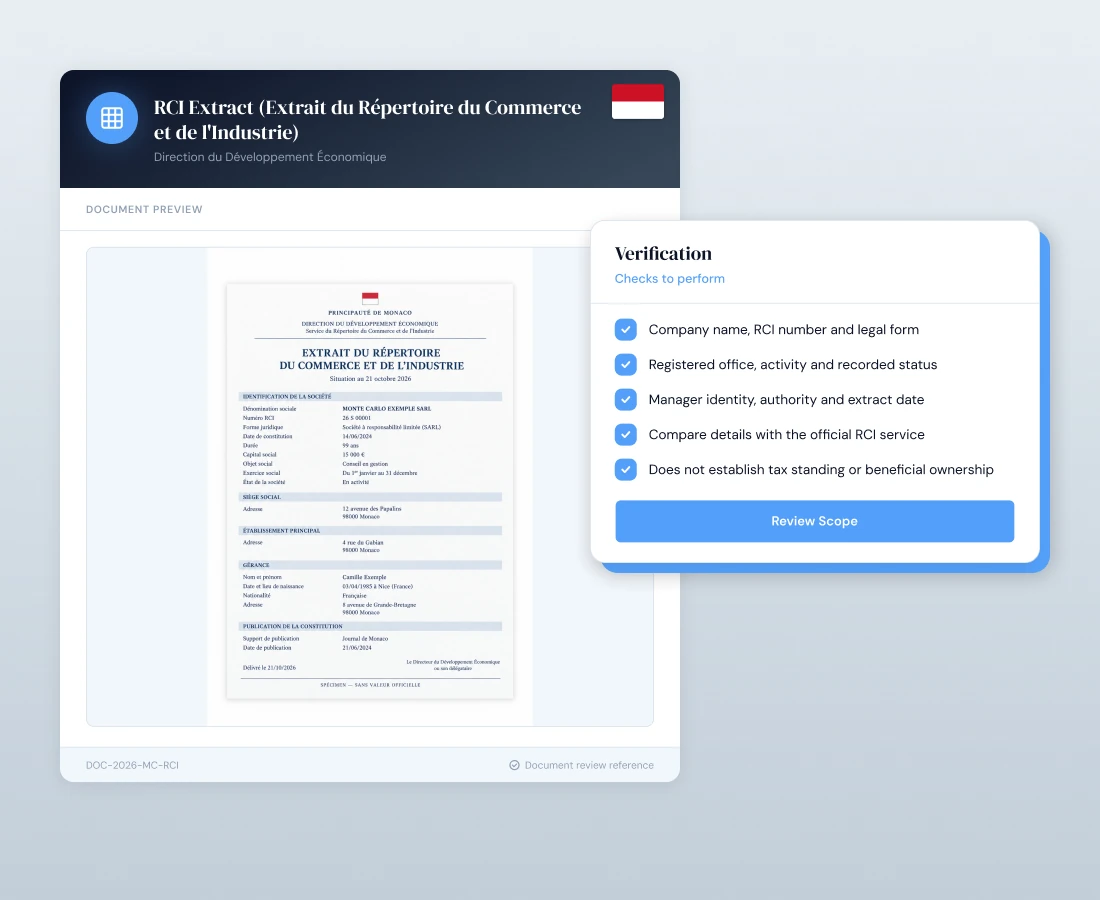
RCI Extract (Extrait du Répertoire du Commerce et de l'Industrie)
The Direction du Développement Économique keeps the RCI, whose extract shows the registration number, legal form, registered office, share capital, directors and beneficial owners. Shufti's live registry call confirms the entry at every check and reads the electronically sealed PDF extract.
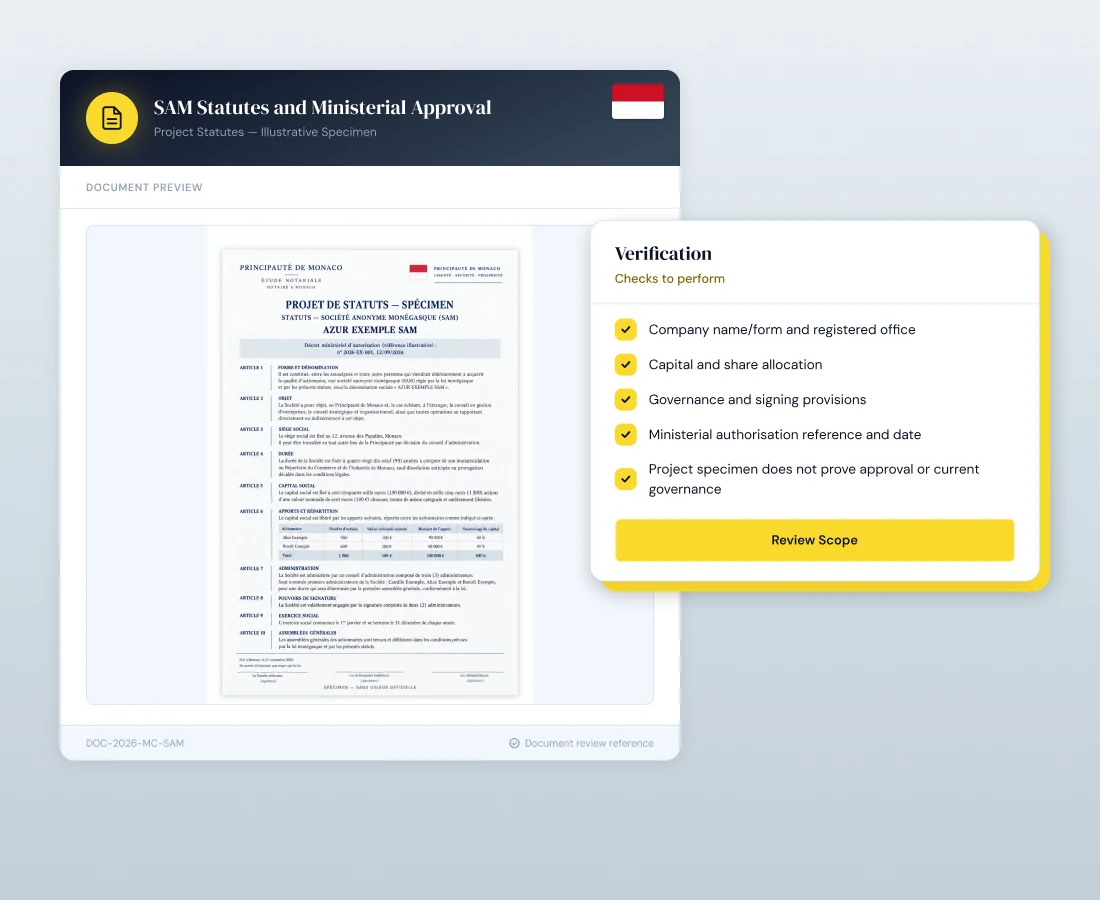
SAM Statutes and Ministerial Approval
A société anonyme monégasque (SAM) needs notarised statutes approved by ministerial decree and published in the Journal de Monaco, with at least €150,000 in share capital. Shufti's AI-OCR reads ownership, capital and signing authority, and flags GAN-generated or edited pages.
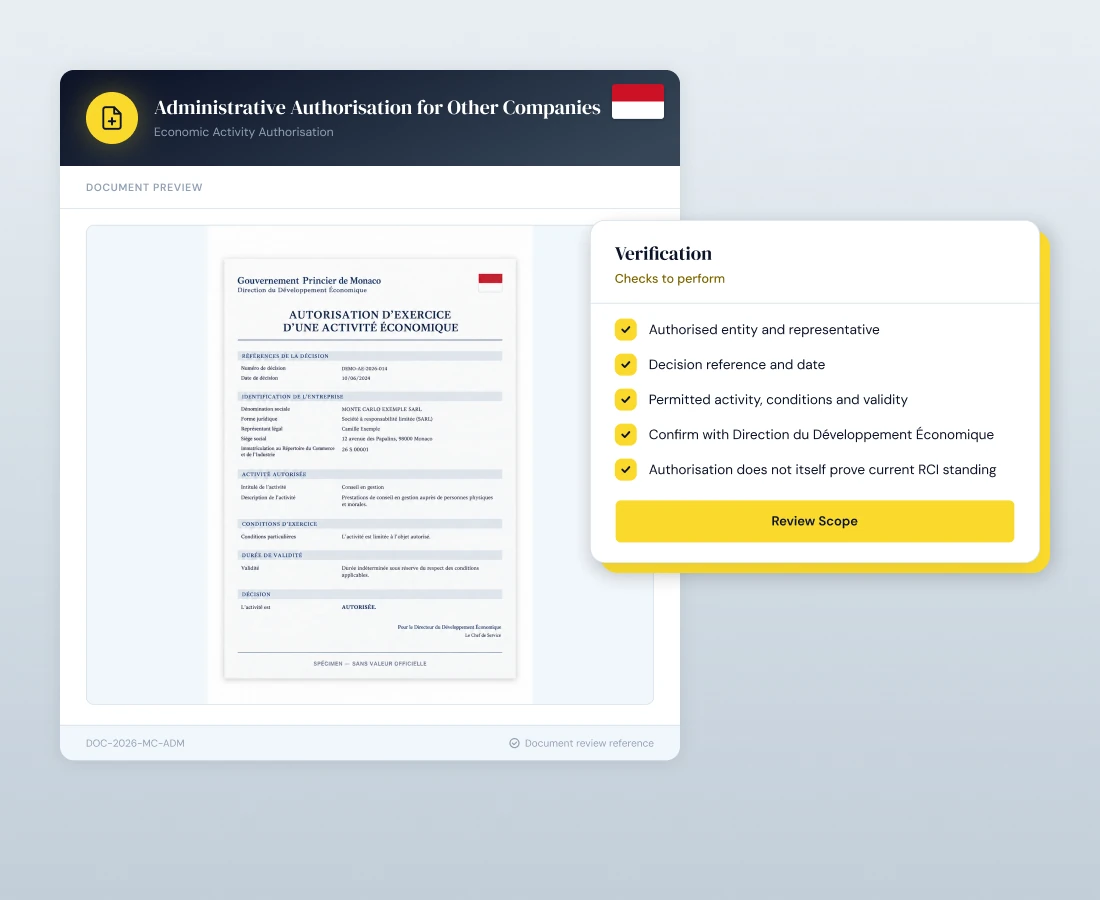
Administrative Authorisation for Other Companies
SARLs, partnerships and sole traders need an administrative authorisation or a receipt of declaration before they register with the RCI. Shufti checks that authorisation against the RCI entry, so the activity a company carries on matches what Monaco has allowed it to do.
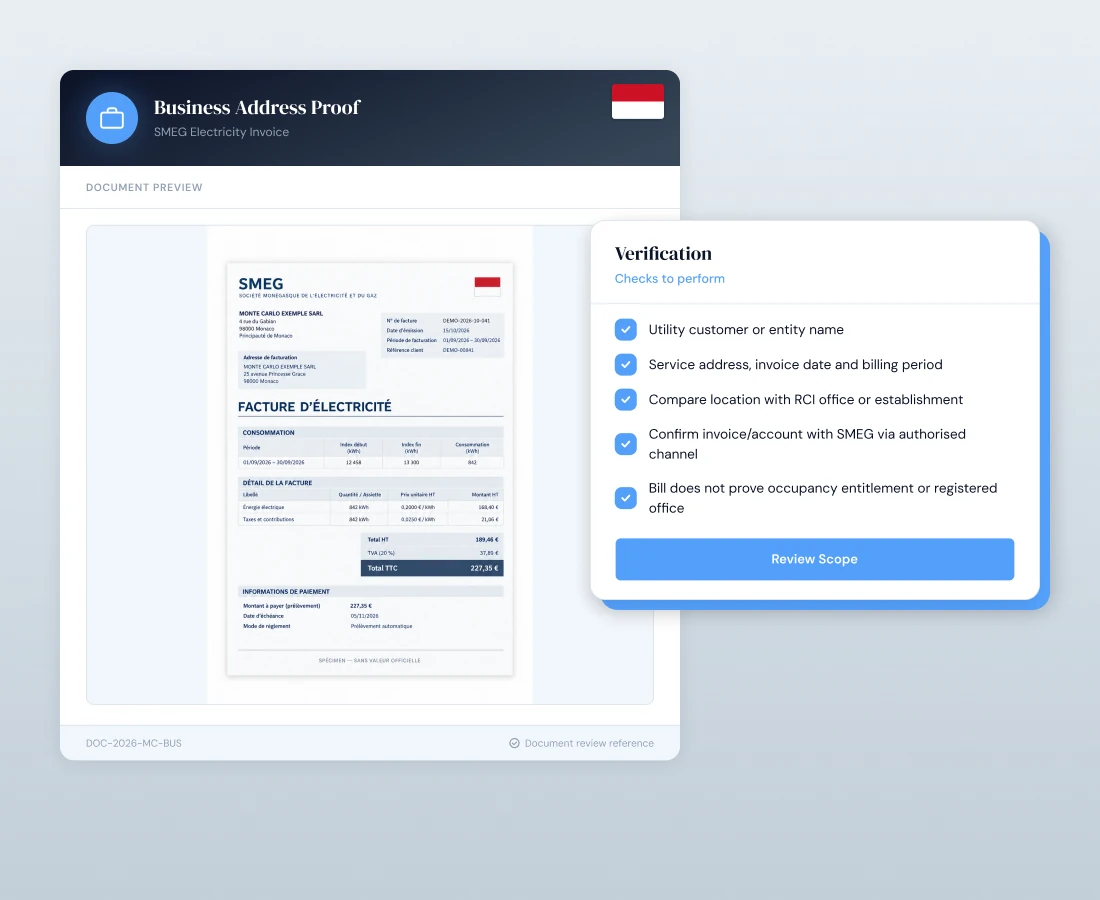
Business Address Proof
The registered office appears on the RCI extract, while the business may run from different premises. Shufti cross-checks the office against lease agreements and SMEG utility bills for the operating address, so the place the company works from matches its filings.
Tax Identity
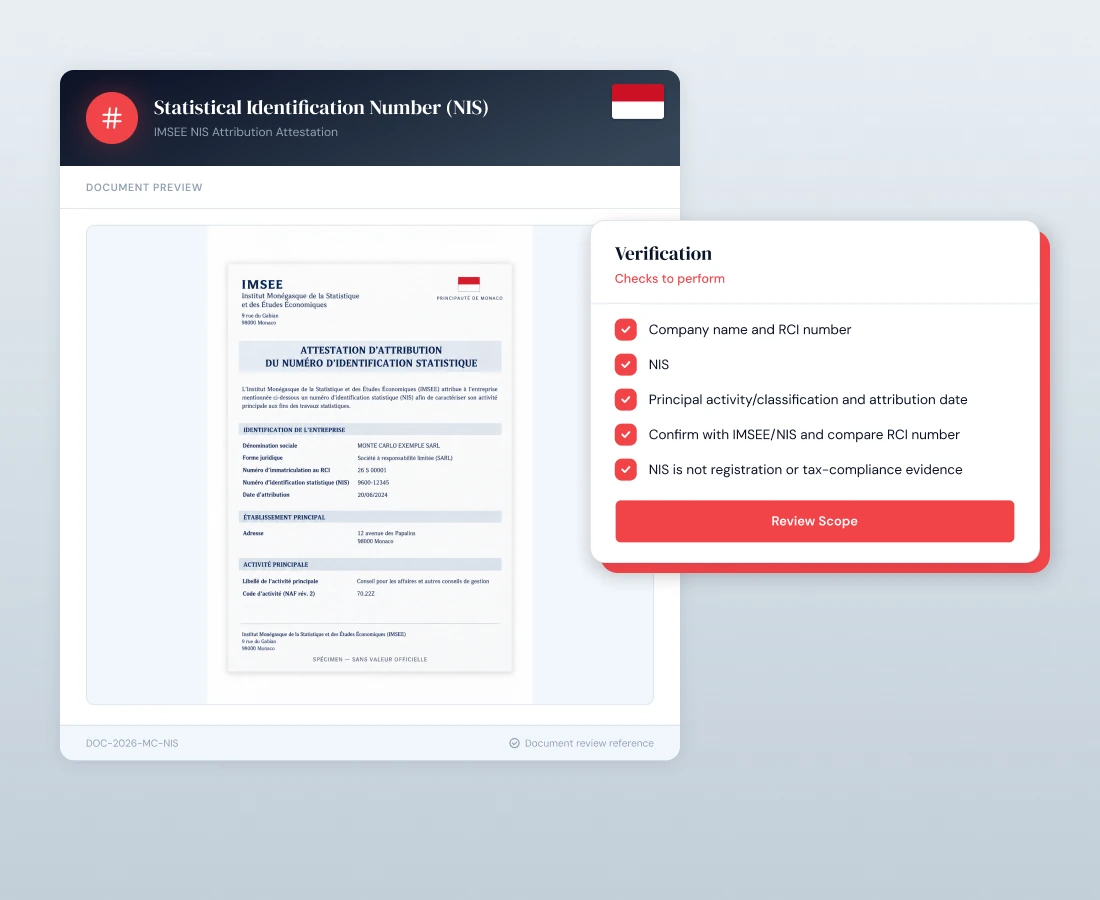
Statistical Identification Number (NIS)
IMSEE, Monaco's statistics institute, assigns every business a NIS built from its activity code and a five-digit sequence, and the NIS attestation is needed to open a business bank account. Shufti extracts the NIS and cross-checks it against the RCI, which can be searched by either number.
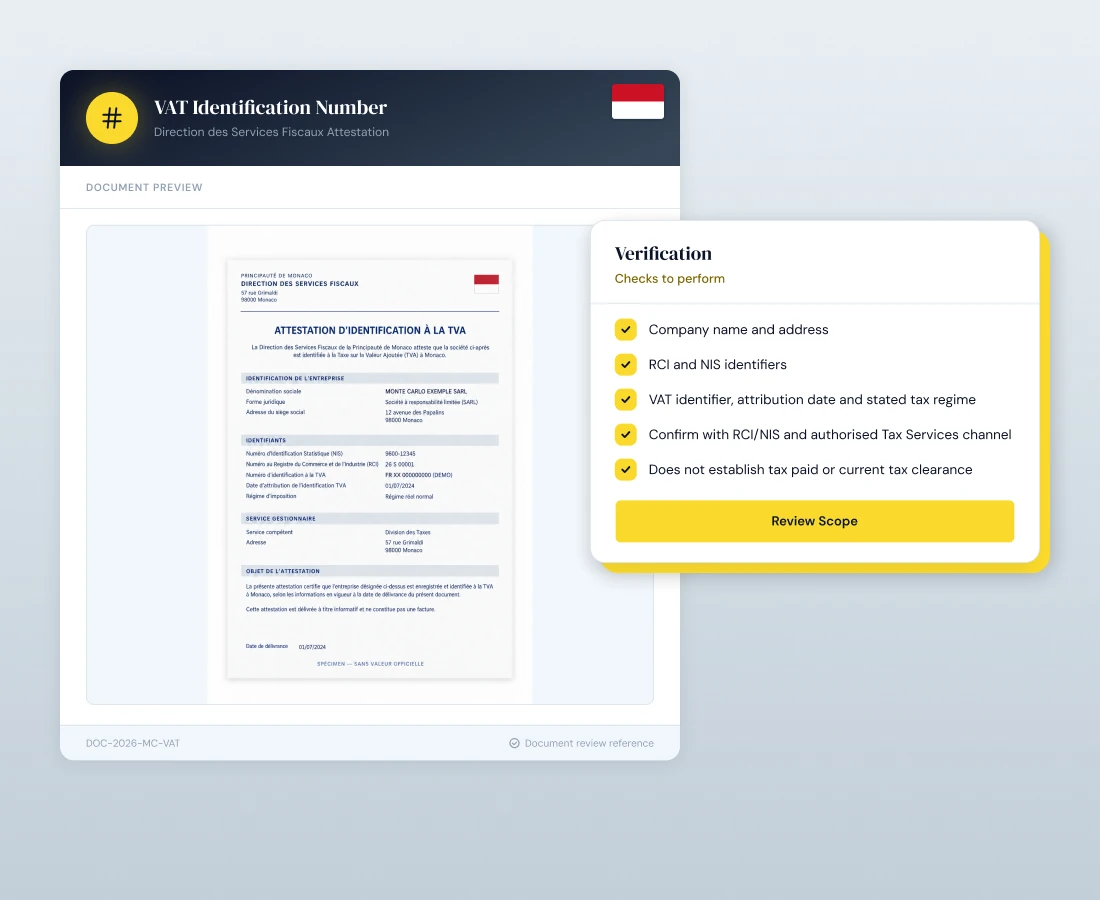
VAT Identification Number
The Direction des Services Fiscaux registers a business for VAT once it files its declaration of existence, and every invoice must carry the VAT number. Shufti reads that number and matches it to the RCI entry, and also handles foreign tax registrations and FATCA/CRS self-certification.
Ownership and Control
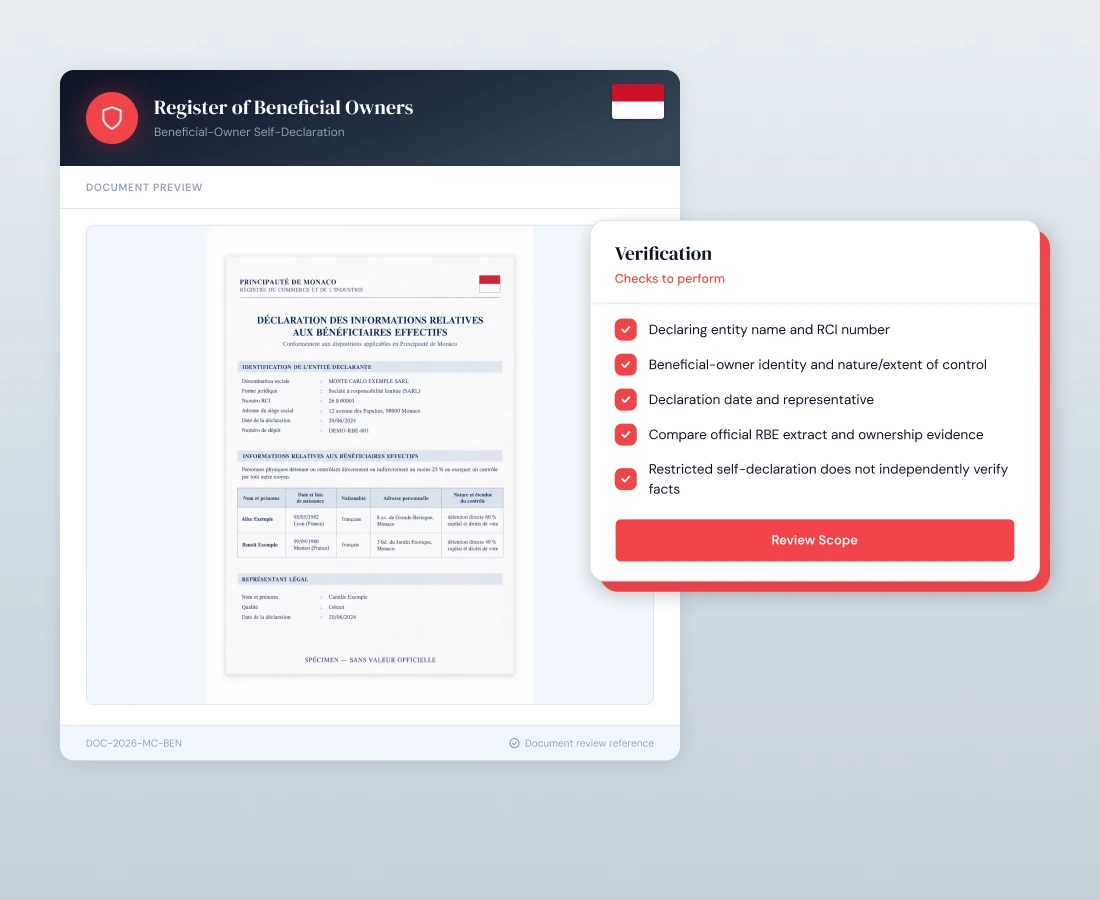
Register of Beneficial Owners (Registre des Bénéficiaires Effectifs)
Annexed to the RCI under Art. 22 of Law No. 1.362, the register takes a company's filing at registration or within 15 days, and any change within one month. Shufti extracts everyone who owns or controls 25% or more, screens them and flags any mismatch with the extract.
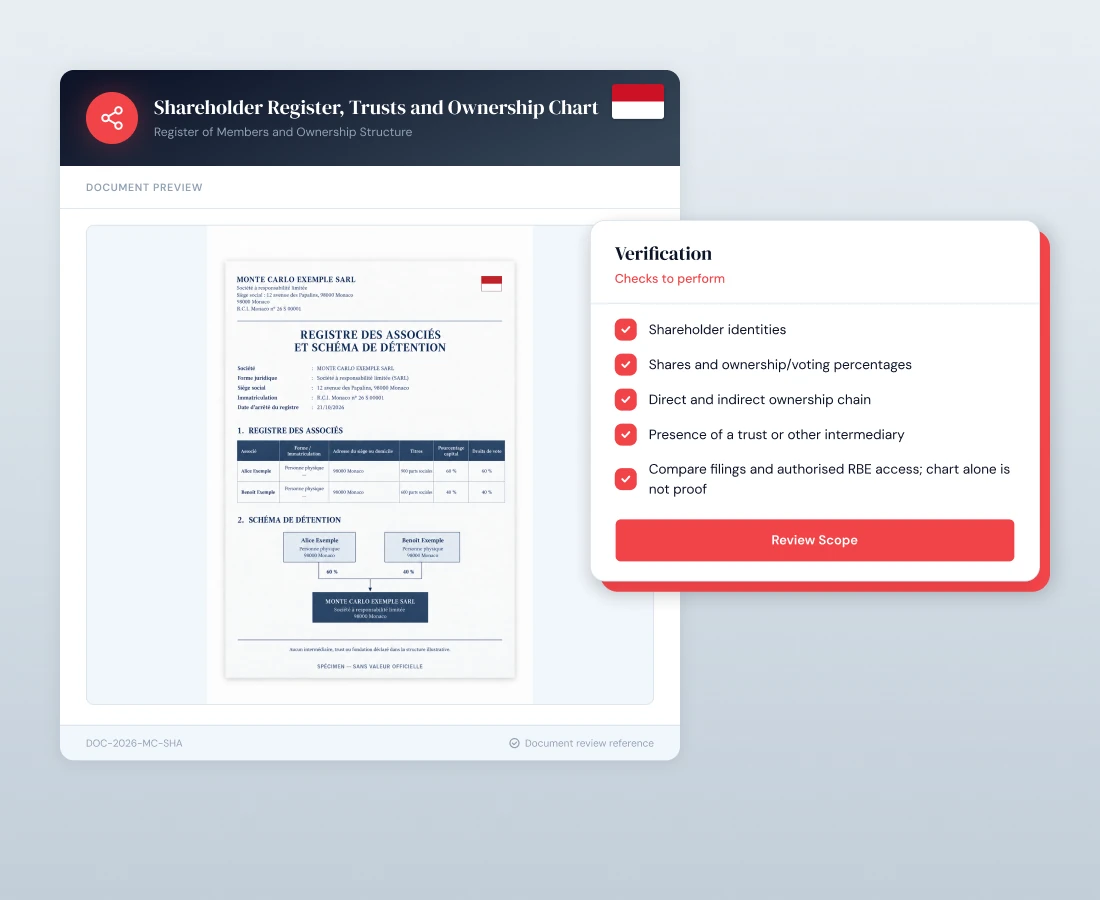
Shareholder Register, Trusts and Ownership Chart
Holding companies, foundations and trusts recorded in Monaco's trust register can sit between a client and its real owner. Shufti maps each layer to the natural person in control and screens every owner against sanctions, PEP and adverse media lists, so the structure cannot hide who benefits.
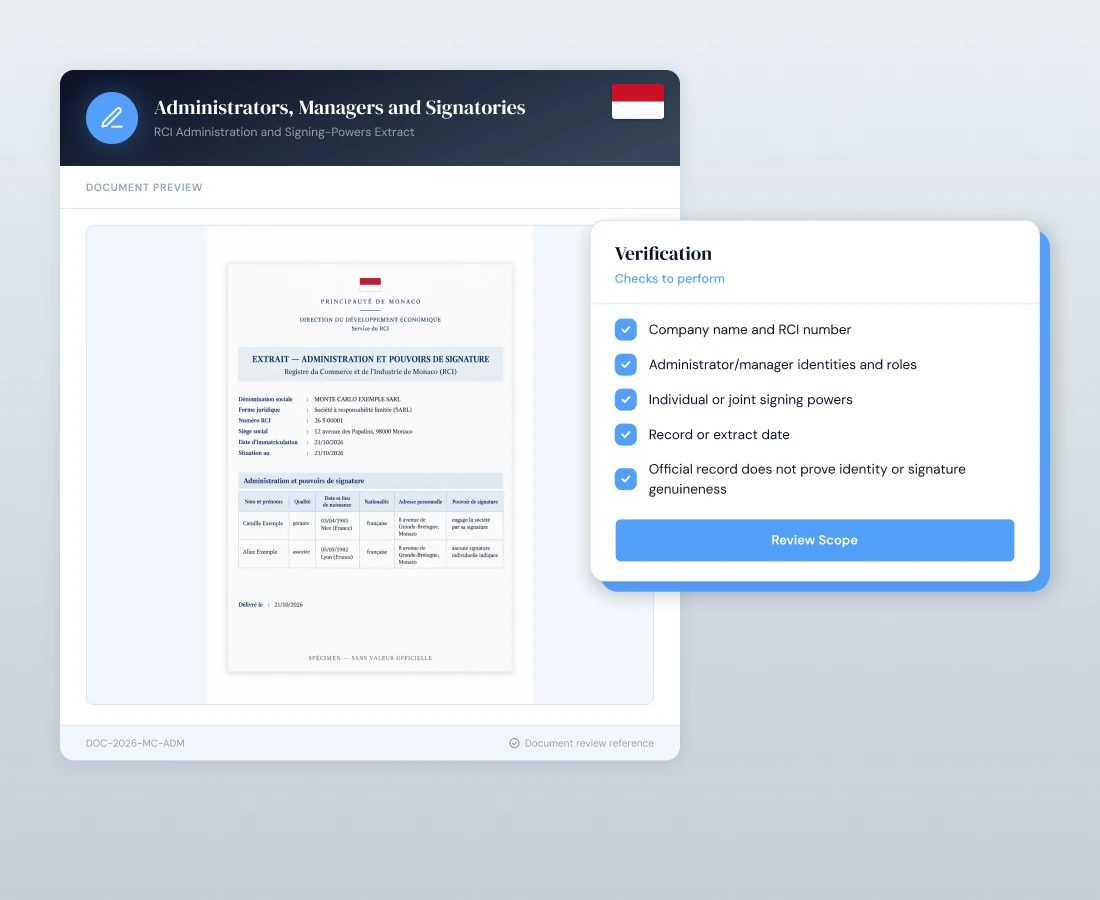
Administrators, Managers and Signatories
Administrators of a SAM and managers of an SARL appear on the RCI extract and can bind the company. Shufti verifies each one's identity document, screens them for sanctions and PEP exposure, and raises an alert when the board or management changes.
Languages We Cover
French, English and Expat Document Parsing
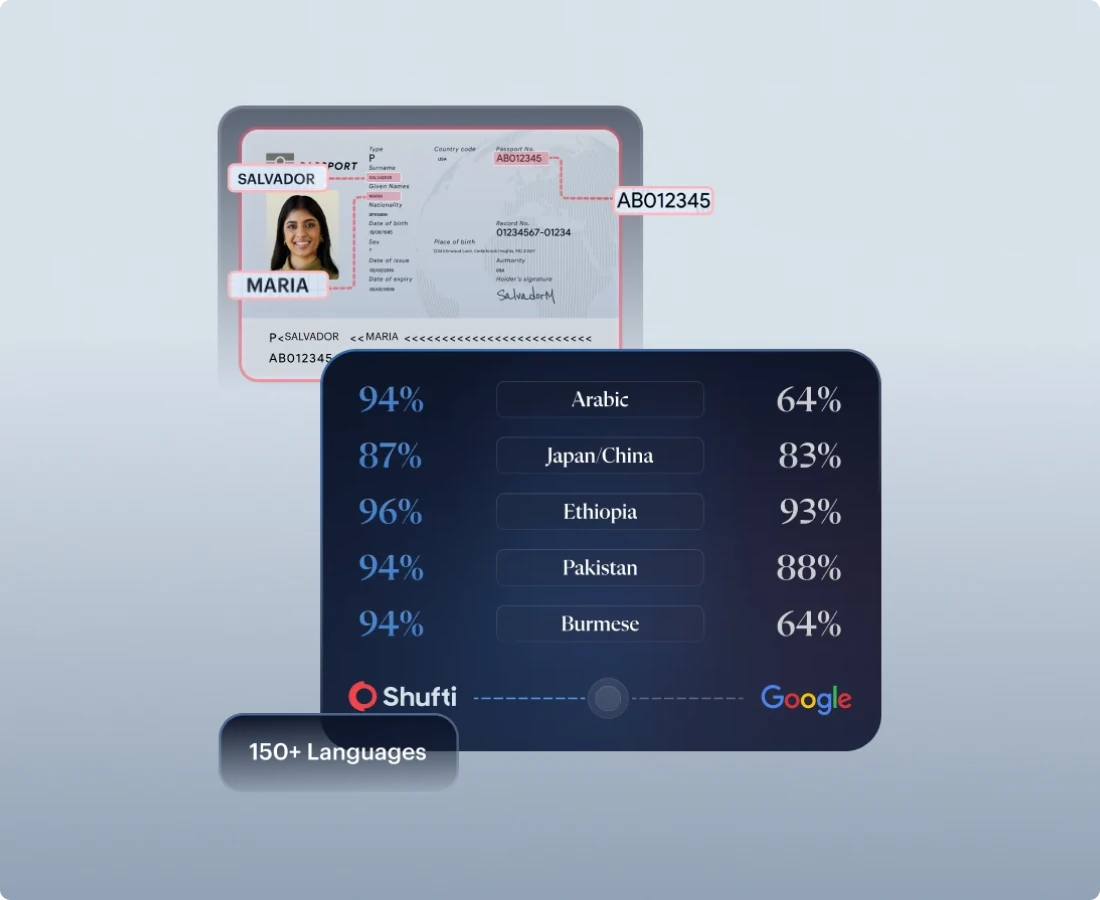
Monaco's identity cards, RCI extracts and statutes are in French with accented characters, while residents and clients from abroad bring documents in many other scripts. Shufti's OCR reads 150+ languages and scripts at 99.7% accuracy and averages 93% against Google Vision's 78.4% across the languages in its published benchmark. Its zero-shot document intelligence reads layouts it has never seen, such as a new ID card design, on first sight.
French Name Matching
Accents drop out on watchlists and bank records, compound first names lose their hyphens, and particles such as de move between documents. Shufti's phonetic matching treats these as the same person in sanctions and PEP screening.
Cross-Document Consistency Checks
Names, dates of birth and addresses are reconciled across the identity card, passport, residence card, MConnect result and beneficial owner register extract, so a mismatch surfaces before an analyst approves the customer.
Independent Validation
Shufti's Recognition Across Independent Evaluations
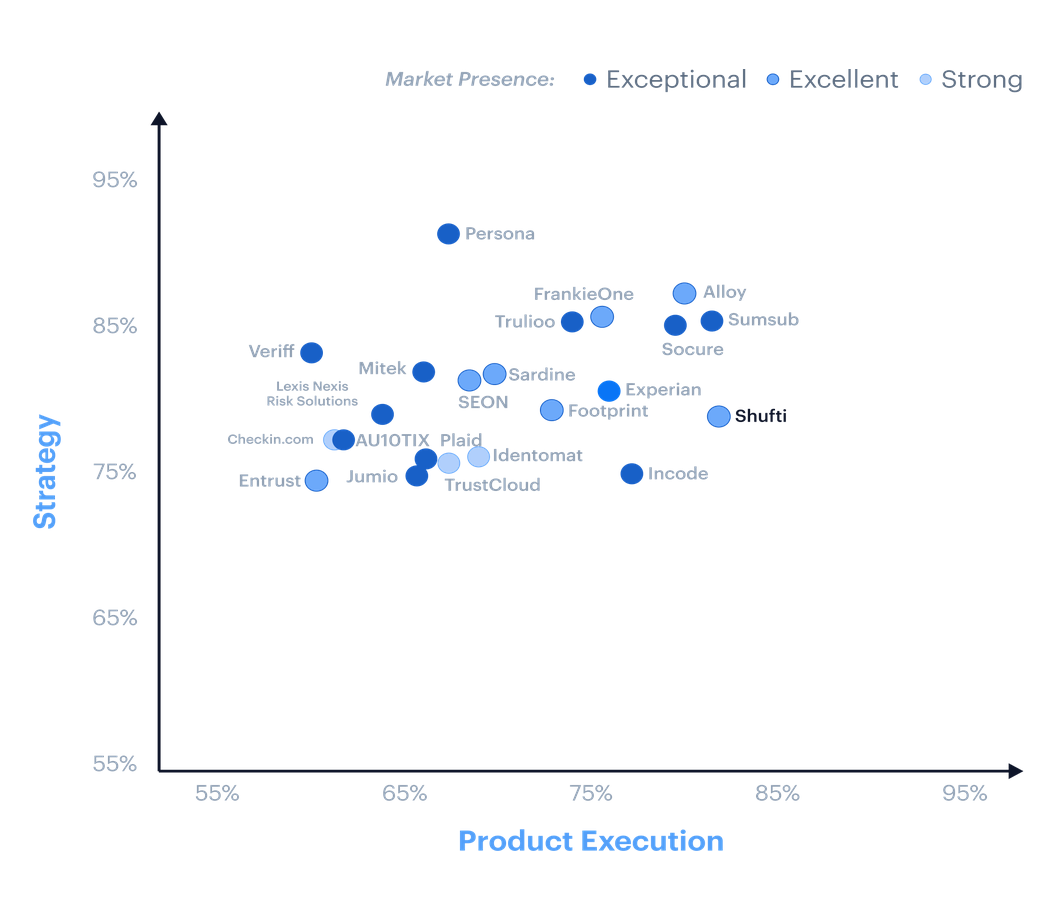
Ranked Exceptional in the Liminal Index 2026 for age estimation
View Report
Differentiated by Gartner on document diversity and country coverage
Read more
Certified at iBeta Level 3 PAD with 0% APCER
Read Blog
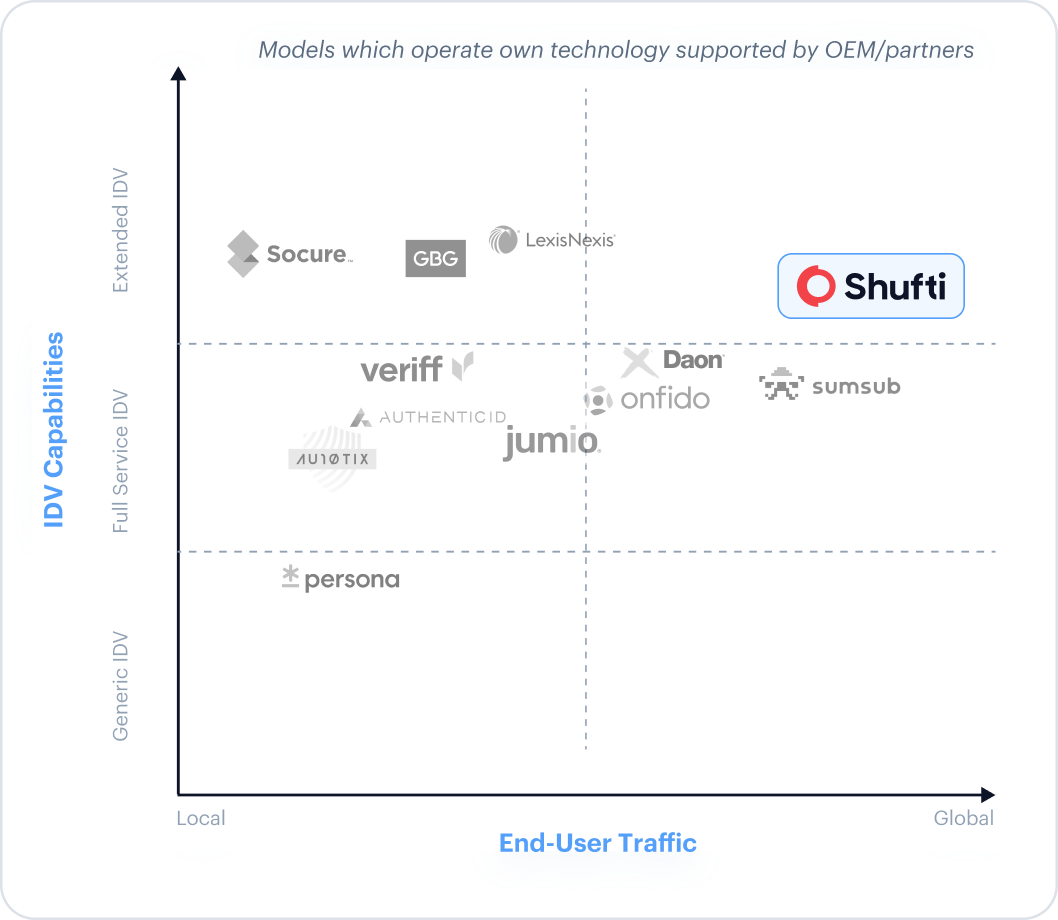
Broadest global reach in the 2025 KuppingerCole Extended IDV report
Download Report
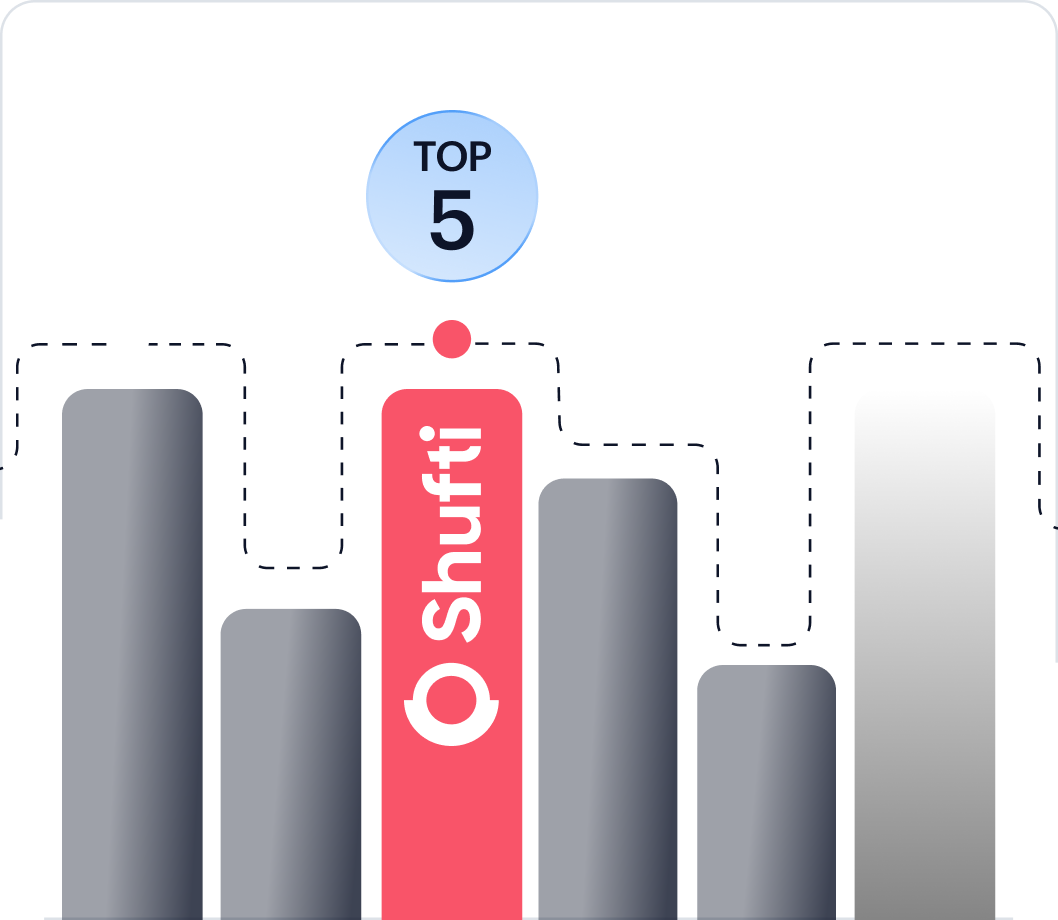
Ranked Top 5 in the DHS RIVR 2025 for identity validation
Read Blog
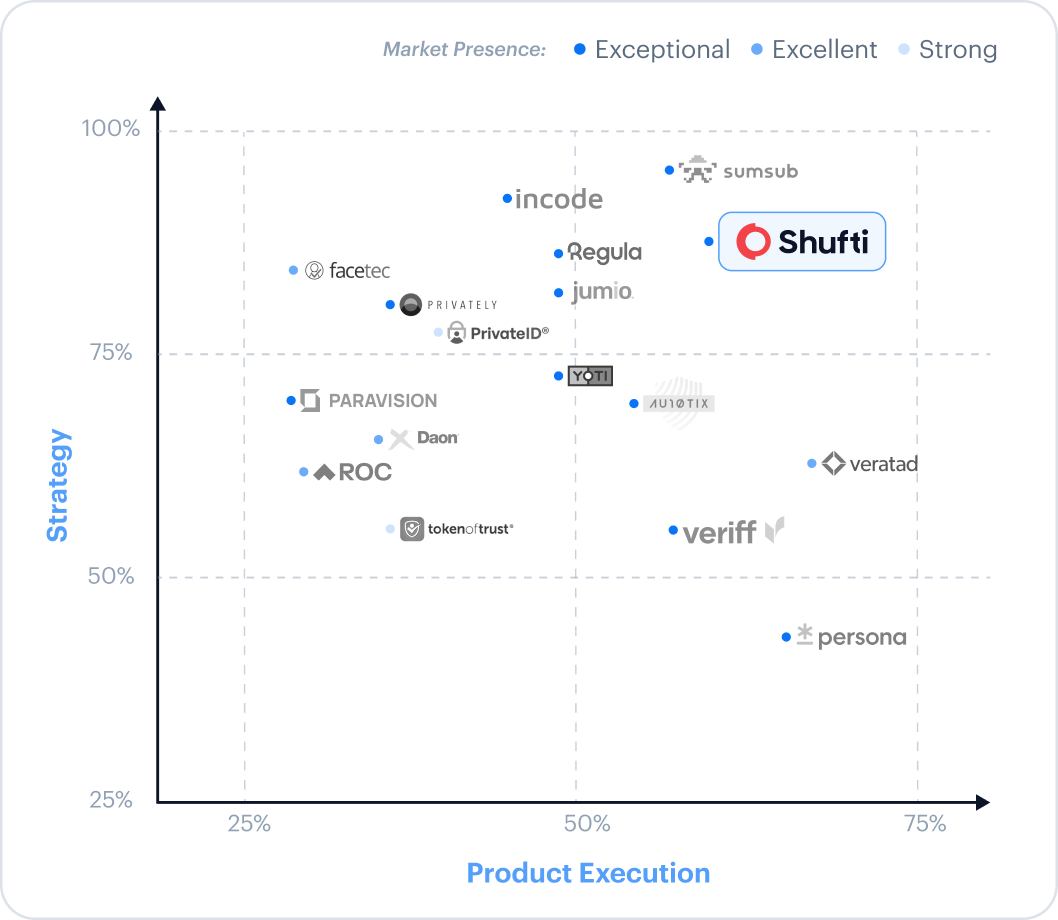
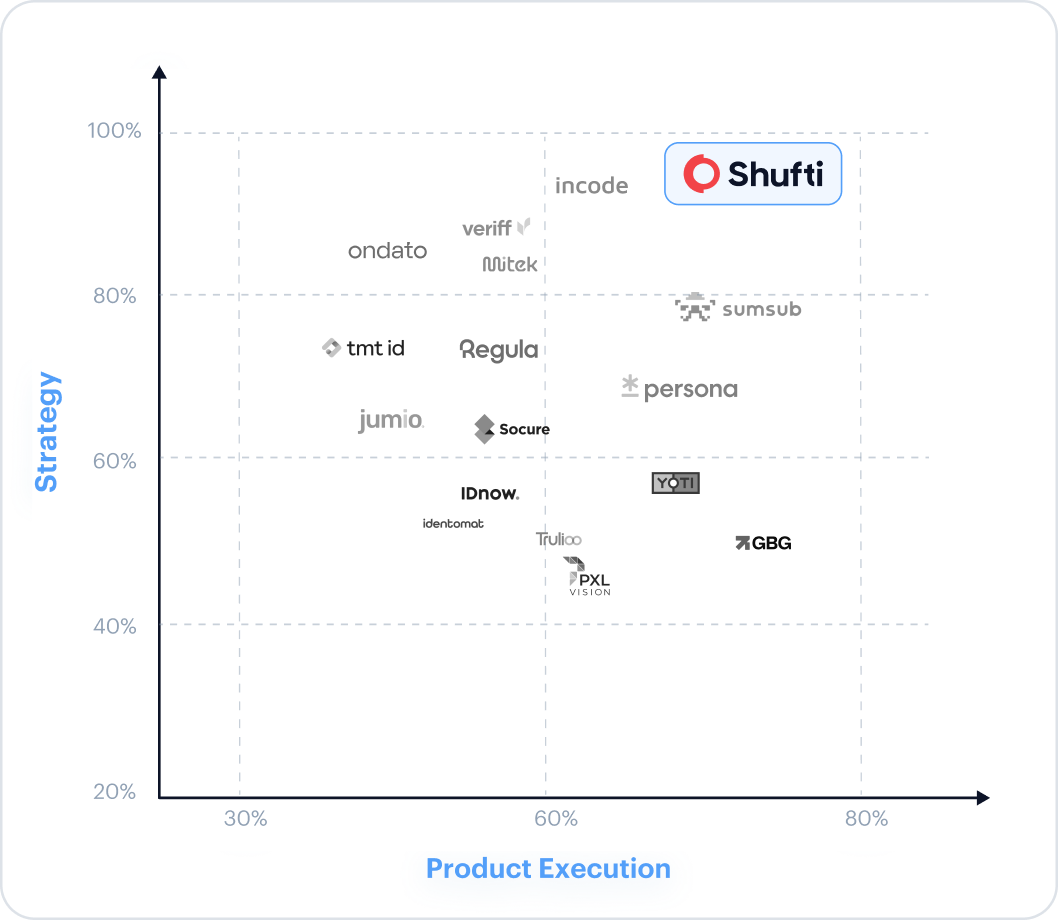
Top Vendor for Product Execution in the Liminal Index for KYC 2026
View Report
Ranked Exceptional for age verification by Liminal Index 2026
View Report
Recognised as a Leader in G2 Fall 2026 reports
Read More
Regulatory Update
Every Verification Route Monaco Regulators Recognize, in One Platform
Sovereign Ordinance No. 2.318 accepts electronic identification at a substantial or high assurance level for customers verified remotely (Art. 5), and Law No. 1.362 otherwise requires two photo IDs and a first payment from the customer's own account (Art. 13). Shufti supports each route, plus chip, document and video checks for non-residents.
MConnect Digital Identity Authentication
LiveThe customer confirms a login with MConnect through your firm's partner integration, and Shufti receives the verified name, given names and date of birth and stores the result in the case file. A high-assurance login lifts the extra Art. 13 steps for remote onboarding.
Two Official Photo IDs
LiveWithout a digital identity, Shufti verifies two valid photo documents, such as a passport and a residence card or driving licence, in one session. It compares names and dates across both and keeps the copies Art. 13 asks for.
First Payment From the Customer's Own Account
LiveArt. 13 also requires the first operation to pass through an account in the customer's name at a supervised bank or financial institution. Shufti's bank account verification confirms the account holder's name before that payment arrives.
NFC Chip Verification
LiveShufti reads the chip in biometric passports, including most foreign passports, and validates the issuer certificates. Monegasque identity and residence card chips are reserved for authorised authorities, so those holders authenticate through MConnect instead.
Document and Face Biometric
LiveThe customer photographs an ID and takes a selfie, and Shufti matches the two with iBeta Level 3 certified liveness. It is the route most non-residents and private banking clients abroad take.
Fraud Prevention Across the Monaco Customer Journey
Reduce fraud losses and protect customer trust across onboarding, account access, and payments. Shufti connects identity, behavioral, device, network, and transaction intelligence to help Monaco businesses act on risk while keeping legitimate customers moving.
Governance & Controls
Audit-Ready Decisions, Lower Operational Drag
Fewer Avoidable Re-submissions
Capture guidance for identity cards, residence cards and passports cuts glare, crop and blur rejections, so more customers pass on the first attempt.
Cleaner Audit Trails
Shufti's case management records sources, results, timestamps, evidence, analyst notes and decision history, packaged as report-ready bundles for STR filing through goAML.
One Workflow, One Back Office
Unify KYC, KYB, AML screening and transaction monitoring in one case file, with perpetual KYC/KYB tracking ownership, director and transaction behavior changes across the lifecycle.
MConnect and Identity Card-First Flow Design
Residents authenticate through MConnect first, while non-residents move to passport and second-document checks in the same flow.
Shufti's IDV/KYC Solutions for Monaco
KYC Solutions
Monaco's customers range from residents who log in with MConnect to private banking clients abroad and yacht owners passing through. One Shufti flow routes each by risk, so nobody faces checks they don't need.
Explore More
Face Verification
Remote onboarding rests on proving the person on camera owns the ID. Shufti's face match runs at a false match rate below 0.001 with iBeta Level 3 liveness, so impostors are stopped while 99.5% of genuine customers pass on the first try.
.
Age Verification
Law No. 1.103 bars anyone under 18 from gaming rooms and Monegasque nationals from playing at all. Shufti estimates age from a selfie in under 5 seconds and falls back to the ID document, which also shows nationality, blocking 99.8% of underage attempts.
.
Bank Account Verification
Payouts, direct debits and first-payment checks go wrong when the account belongs to someone else. Shufti validates Monaco IBANs, including the check digits, and matches the account-holder name in real time, so money moves only to and from the verified customer.
.
Address Verification
Sovereign Ordinance No. 2.318 calls for a separate address document whenever the ID shows no address (Art. 5). Shufti's layout-aware extraction reads residence certificates and SMEG bills at a 99.3% pass rate, with docless checks in under 3 seconds.
.
Document Verification
Forged and altered IDs remain a common route into high-value accounts. Shufti checks Monegasque identity cards, residence cards, passports and licences within seconds, flagging GenAI edits, screenshots, replays and print-and-scan copies before approval.
.
Identity Verification
A single check is rarely enough for a private banking client. Shufti combines document, biometric, NFC, address and eIDV checks in one API session, so a firm can add a second ID or video step to an MConnect login without restarting onboarding.
.KYB Solutions
Monaco companies register with the RCI, and many sit inside holding, trust or family office structures. Shufti pulls RCI data and the beneficial owner register extract at every check, applies the 25% test in Sovereign Ordinance No. 2.318 and ties each owner to a verified identity.
Explore More
Business Verification
Onboarding a Monegasque company means confirming its RCI entry, NIS, signatories and everyone who owns or controls 25% or more. Shufti's live registry call pulls that picture together in one check, putting corporate onboarding under two minutes.
.
Enhanced Due Diligence
PEPs, complex structures and clients linked to high-risk states call for enhanced measures under Arts. 14-1 to 17 of Law No. 1.362, including source of wealth and funds for PEPs. Shufti's branching questionnaires collect those answers, score them and send UBO verification links.
.AML Screening
A customer who is clean at onboarding can land on a list next week. AML screening in Monaco runs on Shufti's perpetual KYC, which rescreens customers against 4,000+ watchlists, including Monaco's national list of freezing measures and UN Security Council lists, refreshed every 15 minutes.
Explore More
Business AML Screening
Sanctions exposure often sits with a beneficial owner, trustee or administrator rather than the company itself. Shufti screens every entity, owner and director against Monaco's national freezing list, UN lists, PEP data and 50,000+ adverse media sources, and perpetual KYB rescreens the whole portfolio.
.
Transaction Monitoring
Art. 5 of Law No. 1.362 requires constant vigilance over every relationship, from private banking flows to digital asset transfers. Shufti's library of 500+ pre-built rules covering structuring, smurfing, and mule activity flags unusual transactions with 60% fewer false positives and builds report-ready case bundles for goAML.
.
Travel Rule
Art. 9 of Law No. 1.362 extends originator and beneficiary data rules to digital asset transfers, and Sovereign Ordinance No. 2.318 applies them to service providers (Art. 39-1). Shufti's single integration connects to major Travel Rule networks, exchanges IVMS101 data and supports four ownership methods for unhosted wallets.
.
AI Compliance Co-Pilot
One common name can return 140+ screening hits. Shufti's AI Compliance Co-Pilot reviews each hit, gives it a 0 to 100 confidence score with a written reason and logs every override, while the MLRO keeps the final call on each match.
.Built To Fit Monaco's Compliance Landscape
AML compliance in Monaco starts with Law No. 1.362 and AMSF, while the CCAF, the Direction du Développement Économique and sector authorities each run part of the regime. Shufti maps its KYC, KYB, AML screening and transaction monitoring controls to every regime below, so one platform covers each licence your group holds.
Law No. 1.362 on Money Laundering, Terrorist and Proliferation Financing and Corruption
Monaco's primary AML law, reshaped by Law No. 1.549 of 2023, requires firms to identify and verify customers before a relationship begins (Art. 4-1), keep constant vigilance (Art. 5), identify beneficial owners (Art. 21), report suspicions to AMSF (Art. 36) and keep records for five years (Art. 23).
Autorité Monégasque de Sécurité Financière (AMSF)
An independent administrative authority since 30 September 2023, AMSF replaced SICCFIN and acts as Monaco's financial intelligence unit, supervisor and sanctioning body (Art. 46). It received 1,479 suspicious transaction reports in 2025, all through goAML, and can fine banks and insurers up to €10 million (Art. 65-8).
Commission de Contrôle des Activités Financières (CCAF)
Licenses and supervises financial activities under Law No. 1.338 of 2007, including portfolio and fund management, investment advice, order transmission, custody and multi-family offices. Its licensees remain subject to AMSF for anti-money laundering supervision, and the two authorities signed a cooperation agreement in February 2026.
Direction du Développement Économique (DDE)
Keeps the Répertoire du Commerce et de l'Industrie, the beneficial owner register for companies and economic interest groupings, and the trust register. Obliged entities obtain register extracts for a fee and must report any missing entry or discrepancy they find (Law No. 1.362, Arts. 22-2 and 22-6).
National List of Freezing Measures
The Direction du Budget et du Trésor applies asset freezes under Sovereign Ordinance No. 8.664 of 2021 and keeps this national list. UN Security Council designations take effect in Monaco automatically (Art. 6), and ministerial freezing decisions apply from publication on the government's freezing measures site.
Law No. 1.528 on Digital Asset Service Providers
Digital and crypto-asset service providers need an authorisation from the Minister of State under this 2022 law, with the CCAF licensing services on financial tokens. These providers are obliged entities under Law No. 1.362, and a bill filed in August 2026 would move all licensing to the CCAF.
Gambling Authority (Service de Contrôle des Jeux)
Oversees gaming houses under Law No. 1.103 of 1987, which bars under-18s and Monegasque nationals from playing. Casinos are obliged entities under Law No. 1.362 and must identify any player who buys or exchanges chips worth €2,000 or more at tables or slot machines.
Law No. 1.483 on Digital Identity
Gives Monegasque nationals and residence card holders a digital identity at a high assurance level (Art. 4). The Mairie issues identity cards under Sovereign Ordinance No. 8.696, the Direction de la Sûreté Publique issues residence cards, and both cards carry that identity on a chip reserved for authorised authorities.
National Strategy Coordination and Monitoring Committee
Created by Sovereign Ordinance No. 9.729 of 2023 and chaired by the Minister of State, the committee steers Monaco's national AML strategy. MONEYVAL evaluated Monaco in 2022, and FATF has listed it under increased monitoring since June 2024, finding the action plan substantially completed in June 2026.
Monaco Data Residency and Deployment
Shufti offers on-premises deployment in Monaco, including air-gapped setups, or other hosting set in your agreement. The agreement defines hosting locations and transfer arrangements, which Arts. 96 to 99 of Law No. 1.565 govern whenever data leaves Monaco.
Law No. 1.565 on Personal Data Protection
In force since December 2024 and supervised by the APDP, the law treats biometric data used to identify a person as sensitive (Art. 7) and expects breach notice within 72 hours where possible (Art. 32). Shufti applies encryption, role-based access and configurable retention to identity and biometric data.
Purpose Limits on Due Diligence Data
Art. 25 of Law No. 1.362 restricts data gathered for due diligence to the fight against money laundering, terrorist and proliferation financing and corruption. Shufti processes verification data only on each client's instructions and only for the checks that client switches on.
Retention Controls
Art. 23 of Law No. 1.362 sets five years after a relationship ends, extendable by up to five more on the firm's initiative or at the request of AMSF or the Procureur Général. Shufti makes retention configurable by client and licence, with legal holds to match.
Encryption and Security
Art. 31 of Law No. 1.565 calls for security matched to the risk, including encryption. Shufti encrypts data in transit and at rest, applies role-based access and audit logging, and holds ISO 27001:2022 certification and SOC 2 Type 2 reports for vendor assessments.
Automated Decisions and Biometric Data
Art. 19 of Law No. 1.565 lets people contest decisions based solely on automated processing, and Art. 35 calls for an impact assessment on large-scale sensitive data. Shufti returns results and supporting details through the API and back office, so teams can explain outcomes and escalate disputed results.
Scope of Our Role
As a KYC provider to Monaco firms, Shufti acts as processor on each firm's written instructions (Law No. 1.565, Art. 26). Sovereign Ordinance No. 2.318 treats an outsourced provider as part of the firm, which keeps due diligence responsibility (Art. 17), and Shufti's privacy notice names any independent-controller activities.
Data Residency and Privacy Controls in Monaco
Monaco AML Sources That Strengthen Decisions
Autorité Monégasque de Sécurité Financière (AMSF)
Direction du Budget et du Trésor
Commission de Contrôle des Activités Financières (CCAF)
Direction du Développement Économique (DDE)
Parquet Général
Gambling Authority (Service de Contrôle des Jeux)
Mairie de Monaco
Direction des Services Fiscaux
UN Security Council Sanctions Committees
Direction de la Sûreté Publique
Financial Action Task Force (FATF)
Council of Europe – MONEYVAL
Turn Monaco Verification Requirements into a Smoother Customer Journey
Share your customer types, risk rules and current onboarding process. A Shufti specialist will show you how to connect identity verification, KYB and ongoing monitoring, reducing operational hand-offs while keeping decision evidence organised for compliance review.
INDEPENDENTLY AUDITED. GLOBALLY CERTIFIED.
Certified to Global Standards



PROVEN WORKFLOWS
Identity Verification Built Around Your Industry in Monaco
Faster Account Opening For Residents And International Clients
Monaco's banks serve residents, private banking clients abroad and holding structures, with AMSF supervising their anti-money laundering controls and the CCAF their financial activities. Shufti runs MConnect, passport and second-document checks, video identification, KYB on companies and trusts, sanctions screening and transaction monitoring in one case file.
Frequently Asked Questions
Does Shufti support Monaco digital identity through MConnect, and what happens when customers cannot use it?
Yes. Customers confirm an MConnect login through your firm's partner integration, and Shufti receives their verified name and date of birth. Customers without it, including non-residents, move to passport, second-document, selfie or video checks, plus a first payment from their own account, in the same onboarding flow.
Is scanning a Monegasque identity card enough, or should verification include its chip?
The chip is not open to private readers. Sovereign Ordinance No. 8.696 reserves its data for authorised authorities and border control, so Shufti pairs forensic checks on the card with liveness, and uses MConnect, which the chip powers, wherever the holder has activated it.
Can Shufti verify foreign documents or identity formats it has not encountered before?
Yes. Shufti's zero-shot document intelligence reads unfamiliar layouts and checks them for tampering, so foreign residents and clients abroad onboard without waiting for a template. Law No. 1.362 asks for a valid official document bearing the customer's photograph, which foreign passports and ID cards provide.
How does Shufti OCR compare with Google OCR for Monaco identity documents?
Monaco documents are in French with accented characters, which Shufti reads at the accuracy it publishes for all supported languages. Across the languages in its public benchmark, Shufti averages 93% accuracy to Google Vision's 78.4%, which matters for the documents foreign clients present.
How does Shufti verify ownership when a Monegasque company has several corporate layers?
Shufti pulls the company's RCI record and beneficial owner register extract, reads statutes, shareholder registers and trust deeds, and traces each layer to the natural person in control. It applies the 25% test in Sovereign Ordinance No. 2.318 and flags any mismatch with the register.
Does Shufti's ongoing monitoring cover more than sanctions screening?
Yes. Law No. 1.362 asks for constant vigilance over the whole relationship (Art. 5), well beyond list checks. Shufti measures transactions against each customer's expected activity, rescreens sanctions, PEP and adverse media data, and sends registry, director and ownership changes to an analyst.
How does Shufti keep screening current and handle Monegasque name variations?
Watchlists, including Monaco's national list of freezing measures and UN Security Council lists, refresh every 15 minutes. Native phonetic models across 80+ languages match unaccented spellings, compound first names and particles in surnames, so listed persons are caught without flooding analysts with false hits.
Can we choose Monaco hosting or run verification inside our own infrastructure?
Yes. Shufti can run on-premises inside your own infrastructure in Monaco, including fully air-gapped deployments, or in other hosting set in your agreement. The agreement records the hosting location and any transfer safeguards that Law No. 1.565 requires when data leaves Monaco.
What controls help us protect identity and biometric data?
Encryption in transit and at rest, role-based access, audit logs and configurable retention protect identity and biometric data, which Law No. 1.565 treats as sensitive. Shufti's ISO 27001:2022 certification and SOC 2 Type 2 reports support vendor reviews, and its consent capture records how each customer agreed to biometric checks.
Can we configure different retention periods for different Monaco licences?
Yes. Retention is set per client, product and licence, so a bank, a management company and a digital asset firm in one group each keep records for at least the five years Law No. 1.362 sets, with longer periods where AMSF asks for them.
What does Shufti provide when our compliance team needs to prepare a goAML report?
Shufti assembles a report-ready bundle with verification results, screening hits, transaction history, analyst notes and the decision trail, so the MLRO can review the evidence and file the report with AMSF through goAML before the transaction goes ahead, as Art. 36 requires.
Can we add verification checks without rebuilding our onboarding journey?
Yes. Shufti's AI Journey Builder lets your team insert MConnect, NFC, a second photo ID, video identification or EDD questionnaires for a product or risk tier through your existing API and SDK. Current journeys carry on unchanged, and new steps reach only the customers who need them.
How does Shufti make verification queries easier for our customer support team?
The back office shows support agents every verification result together with its reason, the captured documents and each passed or failed check. Agents can then explain a decline to the customer, ask for a fresh upload or escalate a dispute without waiting on engineering.
Let’s Build Trust Into Your Business
1B+Verifications Processed
240+Regions Actively Processed
99.7%Accuracy Rate
Samer Al Tamimi
CEO of Safwa Bank
“We take our client’s privacy very seriously and always look for new innovative solutions to ensure a safe banking experience. Working with Shufti feels like a breath of fresh air, as their 100% in-house tech keeps our customer’s data free from vulnerabilities and fully safe and protected.”
Trusted. Compliant. Certified
Explore Shufti For Your Business
Get a personalised demo from our experts.
PROVEN PLAYBOOKS
Explore Practical KYC & AML Resources
17 September, 2026
What Is SEPA? Schemes, Countries and Regulations
SEPA now spans 41 countries and territories, including EU candidate countries added since 2025. Covers its payment schemes, instant payment rules and fraud controls.
Knowledge Base